Hackett Group Hits The Whisper On Cost Leverage, But Revenue, Gross Margin And Cash Flow Still Lag The AI Pivot
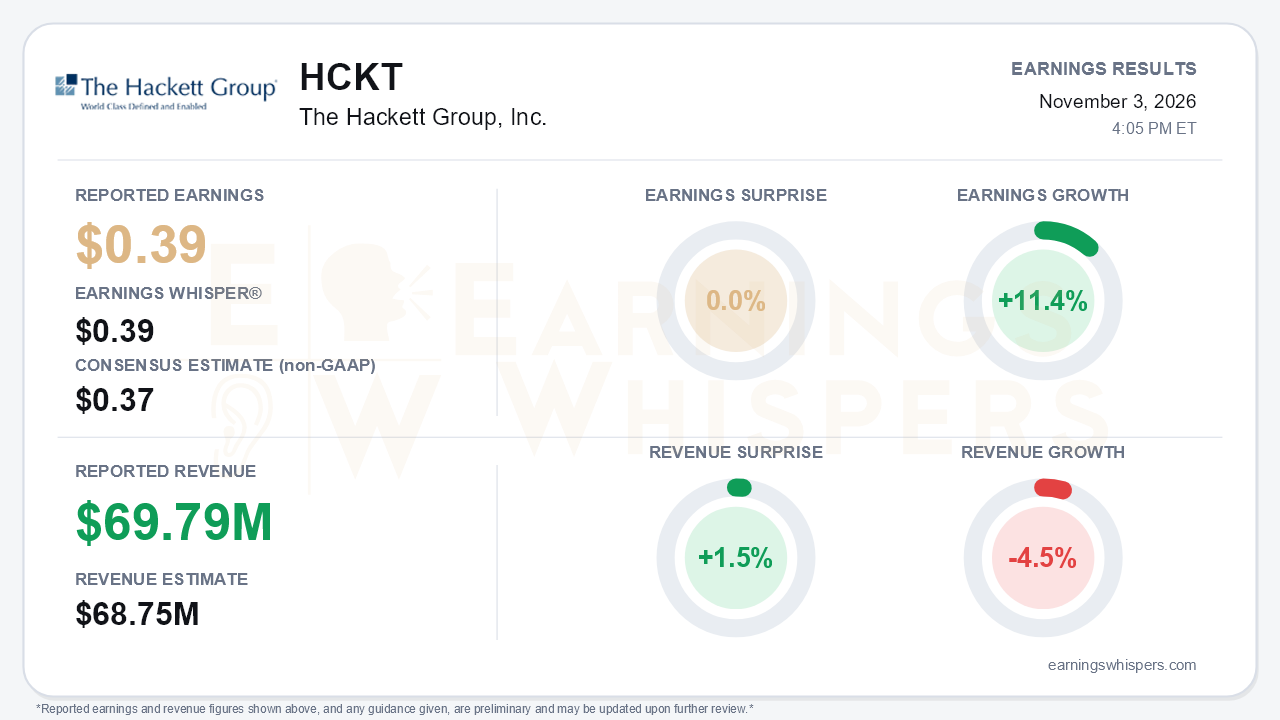
The Hackett Group (NASDAQ: HCKT) delivered exactly what the most informed expectations required, and little more. Adjusted earnings of $0.39 per share beat the $0.37 consensus and matched the $0.39 Earnings Whisper number, a 0.0% surprise against the whisper. Revenue of $69.79 million topped the $68.75 million consensus by 1.5%. The direction of change matters more than the size of the beat. Earnings grew 11.4% year over year, the first year-over-year adjusted EPS gain after a stretch that left nine-month adjusted EPS at $1.07 versus $1.15 a year ago. Revenue, however, still fell 4.5%. That is the central tension: profitability is inflecting while the top line has only stopped shrinking sequentially. It has not started growing.
The quality of the beat deserves scrutiny. Adjusted net income actually fell to $9.7 million from $10.2 million. Per-share growth came from a diluted share count that dropped to 25.0 million from 27.6 million after aggressive buybacks. The operating improvement was also uneven. Adjusted gross margin rose to 44.9% from 44.1% in Q2 and 42.6% a year ago, but it missed the 46% to 47% management guided on the prior call. The EPS result leaned on SG&A discipline instead: adjusted SG&A fell to 24.1% of revenue from 25.5%, and adjusted EBITDA margin climbed to 22.4% from 20.3%. GAAP EPS improved to $0.14 from $0.09, helped by sharply lower stock-price award expense and smaller restructuring charges.
Beneath the headline, the segment mix tells a mixed story. Global S&BT, the core transformation business, rose 3% sequentially to $36.6 million, reversing its Q2 decline. It remains well below the $42.4 million of a year ago. Oracle Solutions grew 4% sequentially to $15.9 million, and its segment contribution nearly doubled year over year to $5.0 million, a clear sign of delivery-efficiency gains. SAP Solutions, the year-over-year growth engine, slipped 6% sequentially to $16.4 million on lower reseller software sales. Management expects Q4 software to fall well short of last year's record of more than $10 million. Consultant headcount of 1,210, versus 1,317 a year ago, underscores that margins are improving on a smaller base.
The call preserved a credible forward story, and the tone shifted noticeably. Management framed results as "early evidence" of operating leverage, a change from earlier talk of disruptive transition. It also set its first explicit target: year-over-year net revenue growth "as early as possible" in 2027. XT version 2 has launched, and the XT/AIX platforms are expected to cover more than 90% of engagements heading into 2027. Management says it is only about 10% of the way to realizing platform leverage. Q4 guidance stepped up again. Revenue is guided to $68 million to $70 million and adjusted EPS to $0.39 to $0.41, despite a $0.03 hit from the 53rd week. Adjusted gross margin is guided to roughly 48.5% and EBITDA margin to 23% to 24%.
Bears have legitimate ammunition, however. Operating cash flow collapsed to $1.8 million from $15.2 million in Q2, and DSO rose to 64 days from 56. Cash fell to $12.6 million while debt climbed to $86.1 million, up from about $76 million at year-end, and quarterly interest expense more than doubled year over year. Management guides Q4 operating cash flow to $15 million to $20 million and has amended the credit facility to $125 million, so the cash shortfall looks like timing for now. Execution on that collection matters. The partner narrative also remains thin. The IBM relationship is dormant, channel deal volume is below original expectations, and JV licensing for AI Explorer and ZBrain is "still further away." Client decisions remain elongated on macro and AI-ROI concerns, and another roughly $1 million AI transition charge is coming in Q4.
The market setup is more complicated than the in-line print implies. Investor sentiment improved from -0.39 to -0.23 ahead of the report, which is meaningfully less negative but still skeptical. Price action has been far more enthusiastic. Shares rose 23.9% from the $10.65 open after the August report to $13.20. They entered earnings within about 1% of the inter-earnings high of $13.33, 37% above the late-September low of $9.63, and 7.3% above the 200-day moving average. With the stock already near its highs, a result that merely matched the whisper leaves less room for upside surprise.
The bottom line is that Hackett's margin narrative is gaining credibility, and Q4 guidance points to further leverage. The quarter's weak spots sit exactly where the investment case must eventually be proven: gross margin execution, cash conversion and actual revenue growth. Until the 2027 growth target shows up in the top line, the rally has priced in more confidence than the revenue line has yet earned.
Read our earnings preview for The Hackett Group, Inc.: https://www.earningswhispers.com/article/HCKT/21581
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-13 | |
| Oct-12 | |
| Oct-06 | |
| Oct-05 | |
| Sep-22 | |
| Sep-18 | |
| Aug-19 | |
| Aug-14 | |
| Aug-05 | |
| Aug-05 |
