Cricut's Hardware Revival Delivers A Big Beat, But Platform Slowdown And One-Time Margin Help Cloud The Quality
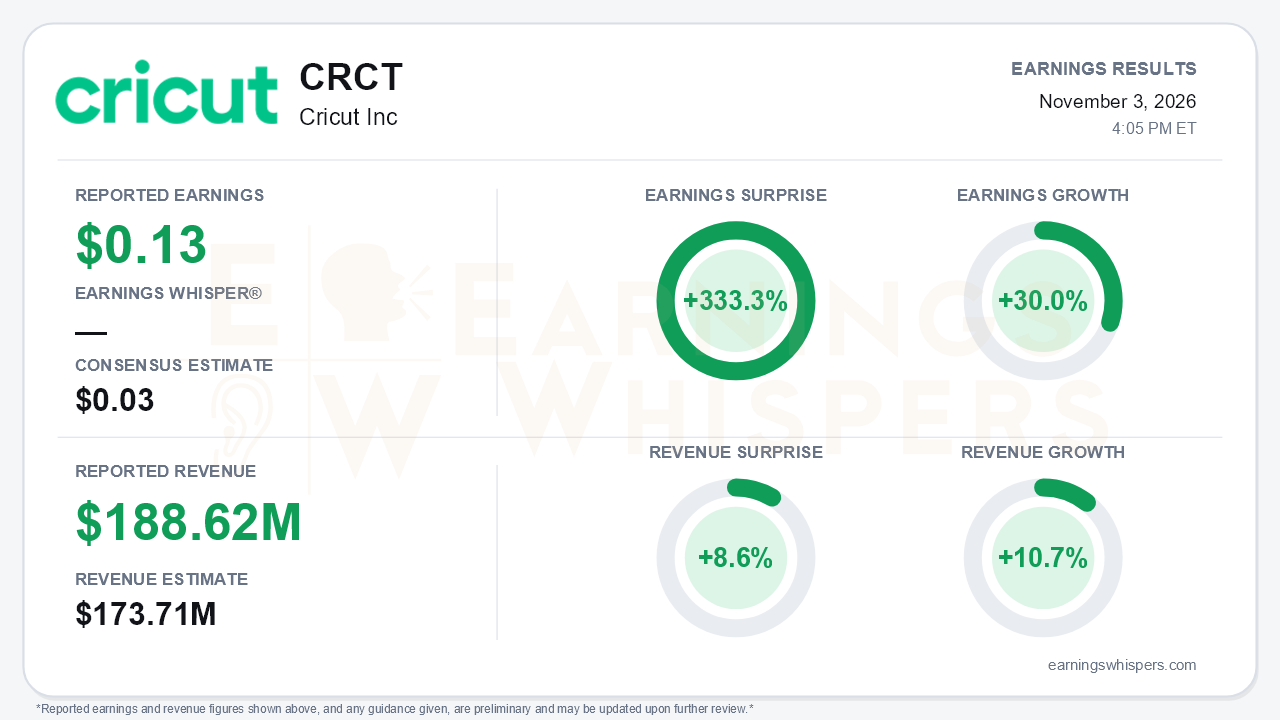
Cricut delivered the second-half inflection management had been promising, and it arrived more forcefully than expected. The company earned $0.13 per share against a $0.03 consensus estimate, a 333.3% surprise, while revenue of $188.62 million beat the $173.71 million consensus by 8.6%. Earnings grew 30.0% year over year and revenue rose 10.7%. The trajectory matters more than the beat: revenue had declined 2% in the first quarter and 9% in the second before swinging to double-digit growth. Management now expects the first full-year revenue increase since 2021. The central tension is that the growth is coming from hardware, while the subscription platform that underpins the long-term thesis keeps decelerating.
The hardware turn was sharp. Products revenue jumped 17% to $102.7 million after falling 22% in the second quarter. The gains were driven by Maker 5, the new StickerPix line, Joy 2 and Explore 5, and machine sell-out grew by double digits for a second straight quarter. International revenue rose 30% to $52.8 million, lifting its share of sales to 28% from 24%. Profitability improved even faster. Gross margin widened to 57.7% from 55.2%, products gross margin reached 30.8% versus 23.1% a year earlier, and operating income climbed 50% to $33.9 million. That put operating margin at roughly 18% versus 13.3%, the first operating-expense leverage since the second quarter of 2024. A higher tax provision kept net income growth to 36%.
The quality of the beat deserves scrutiny. On the call, management acknowledged that part of the products strength reflected channel fill ahead of the launches. It also reflected an easy comparison against the tariff-driven pull-forward in the second quarter of 2025. Third-quarter margins also benefited from several items: capitalized procurement costs, monetization of excess and obsolete inventory, and the final IEEPA tariff refunds. The CFO flagged that these one-time benefits, along with a legal settlement, will not recur in 2027. He also guided fourth-quarter product margins lower on typical holiday promotions and marketing. Notably, reported gross margin of 57.7% sits below the roughly 58.9% underlying figure cited for the second quarter. That suggests the year-over-year margin expansion is less clean than the headline implies.
The platform is where bears have legitimate ammunition. Platform revenue growth has eased from about 6% in the first quarter to just over 5% in the second and roughly 4% now, at $85.9 million. Paid subscribers rose only 2% year over year to 3.07 million and declined sequentially. Platform ARPU growth slowed to about 3% from about 5%, and 90-day engaged users were flat at 3.5 million. Active users ticked up to 2% growth, offering some hope that new machines will eventually feed the subscription base. Management also expects its Premium tier rollout in major international markets to help. For now, though, hardware is carrying the story. Other risks include tariff exposure from China-made StickerPix, investment needs in the competitive dye-sublimation category, and potential AI-related cost pressure on platform margins. Management also stated it remains cautious about the consumer.
Capital return is a meaningful part of the setup. The board declared a $0.70 special dividend alongside the $0.10 semi-annual payout, together worth roughly 13% of the pre-report share price. It also replenished the buyback to $50 million and renewed the $300 million credit line through 2031. Cricut ended the quarter with $273 million in cash and marketable securities. However, inventories rose to $146.9 million from $102.7 million at year-end, and nine-month operating cash flow trailed last year's pace. The special payout will therefore draw down a balance sheet that is also funding a launch-driven inventory build.
Investors moved toward the improvement ahead of the print. Earnings Whispers sentiment edged from slightly negative to slightly positive, a modest shift rather than a wholesale change in conviction. The shares were up 16.6% from the open following the August report and sat about 24% above their 200-day moving average. They had, however, pulled back about 11% from the 52-week high of $6.82 set in mid-October. Price and AVWAP trend readings are positive, while sequential growth and momentum readings are neutral. That mix fits a stock that has already priced in part of the recovery.
The bottom line is that Cricut's new-machine cycle has reversed a multi-quarter revenue decline and produced a decisive beat, backed by a generous capital return. The quarter's best numbers, however, lean on channel fill, easy comparisons and non-recurring margin benefits. Meanwhile, subscribers, ARPU and engagement continue to lose momentum. The fourth-quarter holiday sell-through will show whether the hardware launches can rebuild the platform, or whether this was primarily a product-cycle sugar high.
Read our earnings preview for Cricut Inc: https://www.earningswhispers.com/article/CRCT/21559
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Oct-27 | |
| Oct-26 | |
| Oct-13 | |
| Sep-24 | |
| Sep-03 | |
| Aug-26 | |
| Aug-05 | |
| Aug-04 | |
| Jul-28 | |
| Jul-14 | |
| Jun-11 | |
| May-05 | |
| Apr-14 |
