InnovAge Beats Handily On Record-Level Margins, But A Merely Reaffirmed Guide Keeps The Rest Of Fiscal 2027 In Question
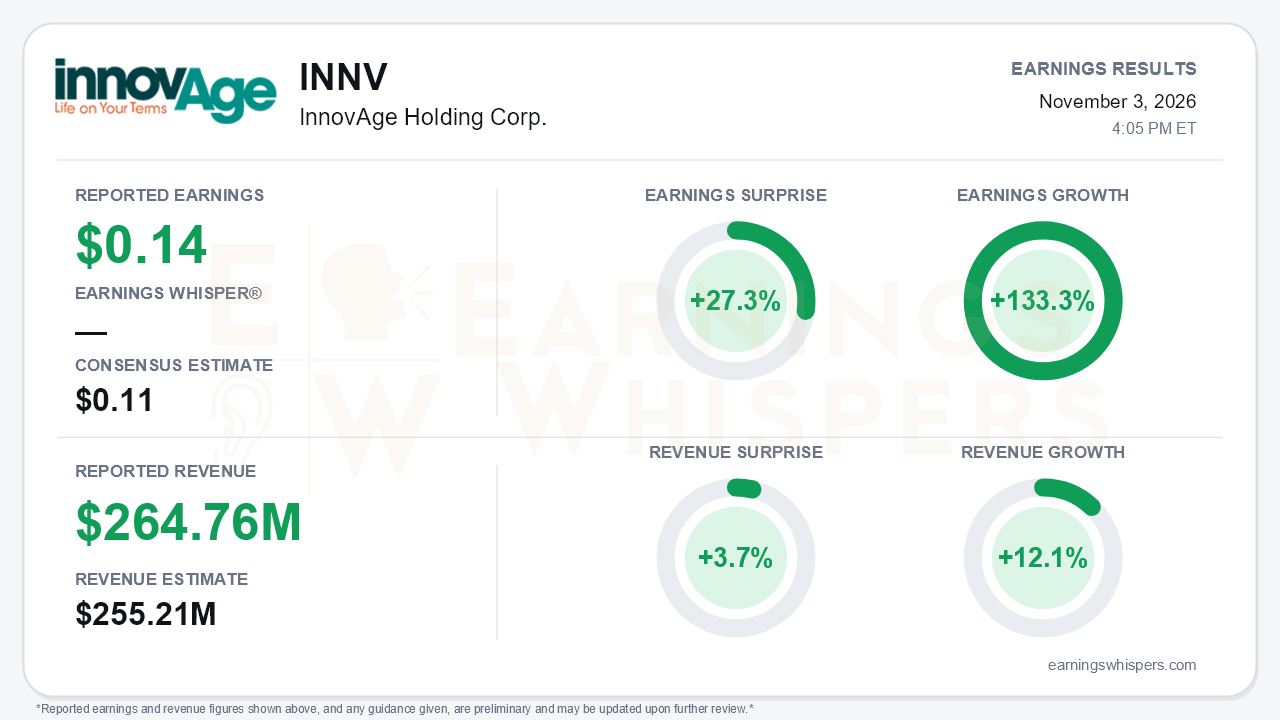
InnovAge opened fiscal 2027 with a clean beat. It earned $0.14 per share against a $0.11 consensus, a 27.3% surprise, and earnings grew 133.3% from the year-ago $0.06. Revenue of $264.76 million topped the $255.21 million estimate by 3.7% and grew 12.1% year over year. Yet management only reaffirmed full-year guidance after raising it repeatedly through fiscal 2026. That is the central tension: the quarter showed what the PACE model can earn at scale, while the outlook implies Q1 was close to a high-water mark.
The quality of the beat is mostly solid. Center-level contribution margin reached 24.0%, up from 21.8% a year ago and edging past the 23.9% posted in Q4. External provider costs rose only about 6% while revenue climbed 12%, helped by lower assisted-living and nursing-facility utilization and lower pharmacy spend. Corporate G&A fell 3.7% to $29.1 million. De novo losses nearly disappeared, at $0.1 million versus $4.3 million a year ago. Adjusted EBITDA jumped to $31.3 million from $17.6 million, a margin of 11.8% versus 7.5%.
GAAP results were less flattered by adjustments than is often the case. Pretax income rose 153% to $20.0 million. A small tax benefit, versus a provision last year, gave net income a modest assist. Operating cash flow of $28.7 million, up from $3.9 million, was strong but leaned on working capital. Receivable collections and amounts due to Medicaid and Medicare contributed meaningfully, so that pace should not be extrapolated. Cash rose to $119.3 million, plus $43.7 million in short-term investments, against $61.4 million of debt.
The call explains why management did not raise guidance. Executives stressed that Q1 is seasonally the strongest quarter and should not be annualized. They flagged three headwinds:
- risk-score decay, flu season and January payroll resets;
- the V28 Medicare risk-adjustment blend moving from 90/10 to 50/50 in January, with "softer" diagnosis codes down-weighted and the Medicare rate increase held at 1.5% to 2%;
- California Medicaid rates that are still pending. California and Colorado together account for roughly 70% of census, and both states face fiscal pressure.
The math is stark. The $105 million to $115 million adjusted EBITDA range leaves roughly $74 million to $84 million for the final three quarters, or about $25 million to $28 million per quarter, well below Q1's $31.3 million. The guide still implies growth over the $94.6 million delivered in fiscal 2026, but at a sharply slower pace.
Cost pressures also showed up beneath the headline. Inpatient utilization is rising, and assisted-living and nursing-facility unit costs are climbing. Cost of care grew 12.7% on headcount, wages and restructuring, slightly faster than revenue.
Management's posture has shifted from margin repair to growth. With margins near the 10%-plus long-term target, the emphasis is on reinvestment rather than further expansion. The company described an M&A pipeline being cultivated, de novo market screening benchmarked against Florida, and adjacencies such as a pre-PACE Medicare-only population. No deals were announced. Census reached 8,420, up 6.7% year over year and from 8,230 in Q4, but it must reach 8,625 to 8,850 by year-end to hit guidance. The company also said it will now emphasize year-over-year comparisons over sequential ones, a reasonable change that also softens attention on the quarter-to-quarter deceleration the guide implies.
The market had already priced in skepticism. Shares fell 23.8% from the $11.70 open after the September report to $8.92. That leaves them about 1.6% below the 200-day moving average of $9.06 and near the bottom of the inter-earnings range, roughly 6% above the $8.40 low and about 27% below the $12.20 high. The completed 11.5 million-share secondary by sponsor Welsh Carson/Apex improves float and liquidity, but sponsor selling continues, and the remaining supply is a legitimate overhang. Investor sentiment improved from 0.07 to 0.23, more constructive but hardly euphoric. The Earnings Whispers trend signals are mixed: sequential growth and momentum readings are positive, while AVWAP remains negative, consistent with a stock whose fundamentals have firmed faster than its price.
The bottom line is that InnovAge delivered a high-quality quarter, with real margin gains, near-zero de novo drag and strong cash generation. The decision to hold guidance tells investors to treat Q1 as a seasonal peak rather than a new run rate. With V28 and California rates still to land, upside depends on whether the remaining quarters hold closer to $28 million in EBITDA than $25 million, and on whether the growth agenda produces tangible deals.
Read our earnings preview for InnovAge Holding Corp.: https://www.earningswhispers.com/article/INNV/21587
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-20 | |
| Sep-22 | |
| Sep-22 | |
| Sep-09 | |
| Sep-08 | |
| Aug-26 | |
| May-12 | |
| May-05 | |
| May-04 | |
| Apr-21 | |
| Mar-09 | |
| Mar-06 |
