CorVel's Margins Accelerate Faster Than Revenue, But Visibility Stays Thin Without Guidance
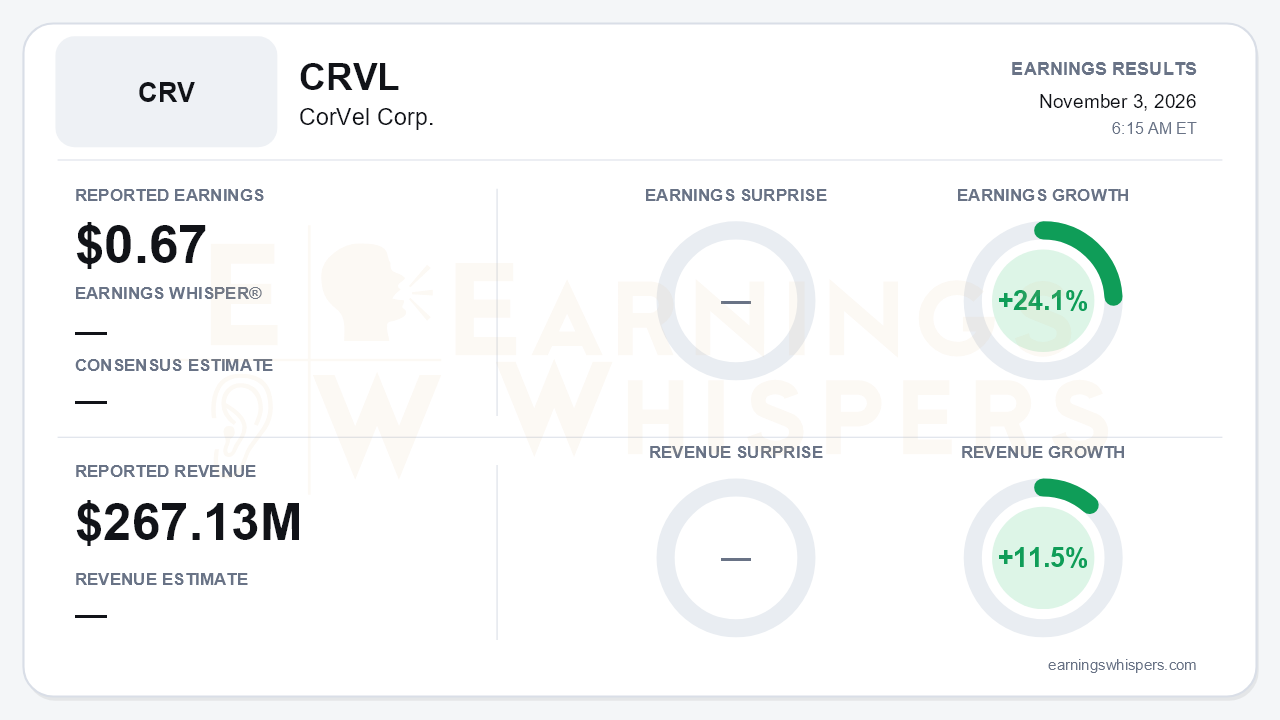
CorVel Corp. (NASDAQ: CRVL) earned $0.67 per share in its fiscal second quarter ended September 2026, up 24.1% from a year ago, on revenue of $267.13 million, up 11.5%. No consensus estimate or Earnings Whisper was available, so the quarter has to be judged on its own trajectory. On that basis it was strong. Revenue growth held at the double-digit pace reached last quarter, but profit growth ran at more than twice that rate. The story has shifted from a top-line recovery to one of operating leverage.
The income statement supports that reading. Gross profit rose 24% to $72.3 million, and gross margin widened to 27% from 24% a year earlier and from 23.3% as recently as the December 2025 quarter. General and administrative expense grew about 19%, slower than gross profit, so operating income climbed roughly 28% to $45.8 million. Operating margin expanded from about 15% to just over 17%. Net income rose a more modest 22% because the effective tax rate increased to roughly 25.6% from about 22% a year ago. A diluted share count about 2% lower helped close the gap to the 24.1% EPS gain. The sequential picture is cleaner than it first appears. The prior quarter's $0.63 included about $0.07 from a one-time CERIS receivables settlement, so underlying earnings stepped up meaningfully from roughly $0.56 to $0.67.
The call analysis shows a demand engine that is still gaining speed even though headline growth has leveled off. Year-over-year revenue growth has run 3%, 7%, 11% and now 11% over the past four quarters, and trailing twelve-month revenue passed $1 billion. Underneath that plateau, claims volume growth accelerated to 11.5% from 8% in the prior quarter. Sales closures more than doubled year over year, following a 60% gain in new sales last quarter and 56% bookings growth the quarter before. That pipeline suggests revenue growth has not peaked. Management also changed how it frames artificial intelligence. Earlier calls presented AI as a prospective benefit. Management now ties AI-assisted claim summarization and workflow automation directly to operating leverage and better margins. Days sales outstanding improved to 37 from 39 in the prior quarter.
CERIS, the payment-integrity business, delivered the most notable new catalysts. It implemented another top-10 national health plan, signed a strategic partnership that opens access to the Blue Cross Blue Shield market, and introduced Hospital Bill Audit and Professional Claims prepayment products. Marketwise Repricing for out-of-network bills, an expanded pharmacy benefits program and the MyCare self-service portal broaden the managed-care offering. The risks are real, if less dramatic:
- **Capacity strain:** Claims volume growing faster than revenue raises the question of whether service quality and staffing can keep pace.
- **Slower buybacks:** Repurchases fell to $18.1 million from $21.8 million in the prior quarter and $20 million the quarter before.
- **Limited visibility:** The company again offered no formal guidance and took no analyst questions.
There is a disclosure discrepancy worth noting. The call analysis flags cash and free cash flow as missing from the transcript, but the press release reports $270 million in cash and no borrowings, up from $233 million in March. Customer deposits of $130 million are part of that cash position. Free cash flow was not disclosed in either source.
Market context is sparse this cycle. Investor sentiment readings, a current share price and inter-earnings range data were not available. Shares opened at $59.06 after the August report, below the current 200-day moving average of $62.65. That suggests the stock entered this period trading under its longer-term trend even as fundamentals improved, though whether it has since recovered that level cannot be determined from the supplied data. The absence of guidance and analyst Q&A means the market must rely on reported trends rather than management targets. That favors a company producing consistent results, but it can amplify reactions to any stumble.
The bottom line is that CorVel's quarter was better than its steady 11.5% revenue growth implies. Gross margin up three points, operating income up roughly 28%, and accelerating claims volume and sales closures point to a business converting growth into profit more efficiently than it was a year ago. Bears can point to the revenue-growth plateau, slower buybacks, a higher tax rate and a near-total lack of forward commentary. Still, the sales pipeline and CERIS expansion give the growth story credible support, and margin leverage is now the variable to watch.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Sep-22 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-27 | |
| Jul-08 | |
| Jun-17 | |
| Jun-02 | |
| Jun-01 | |
| May-20 | |
| May-20 | |
| May-20 |
