ECARX Holds Its Revenue Guide, But A 7% Gross Margin And A Drained Cash Balance Undercut The Growth Story
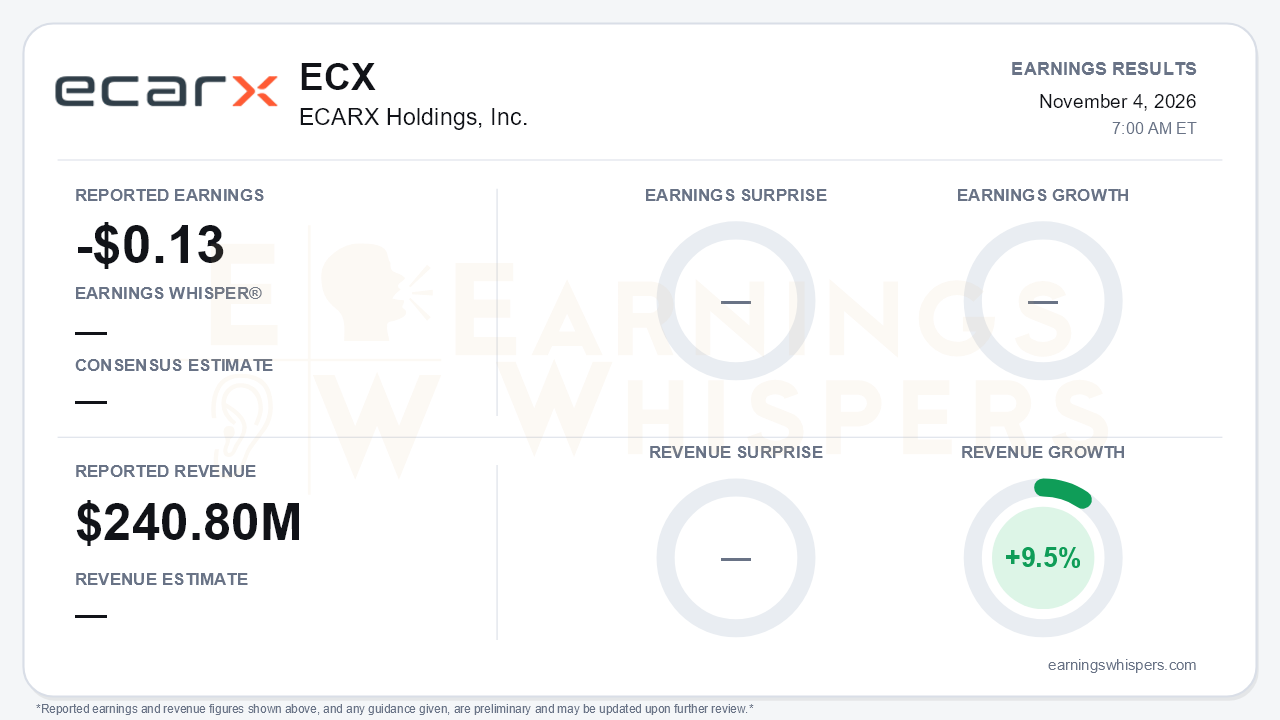
ECARX (NASDAQ: ECX) delivered the volume, but the economics of that volume broke down in the third quarter. The company lost $0.13 per share on revenue of $240.8 million, with revenue up 9.5% year over year. No consensus EPS or revenue estimate was available, so there is no surprise to measure. The more telling comparison is internal. The loss per share widened from $0.03 a year ago, and net loss grew to $48.6 million from $8.4 million. Management reiterated full-year revenue guidance of $1.0-$1.1 billion. The central tension is that ECARX is shipping more units into a declining China market while earning far less on each one, and it made a large cash acquisition at the same moment.
The top line overstates the health of the business. Sales of goods rose 23% to $222.7 million, but the release attributes much of that to price increases meant to offset higher memory costs, not purely to demand. Those price increases fell short. Cost of goods sold jumped to $213.2 million from $153.3 million, and gross profit fell 65% to $16.9 million. Gross margin dropped to 7.0%, compared with 21.9% a year earlier.
Higher-margin revenue also weakened:
- Service revenue fell 53% to $17.7 million, which the company attributed to slower model-launch timing after a second-quarter peak.
- Software license revenue was down 56%.
Cost discipline was real but could not offset the gross-profit shortfall. R&D fell 12%, and SG&A excluding a $6.7 million DreamSmart convertible-bond impairment declined 18%. Even so, operating loss widened to $36.2 million from $6.3 million, and interest expense more than doubled to $8.0 million. Investors should also note that prior periods were restated for the common-control Qiguang combination and for corrected subsidy accounting. That complicates year-over-year comparisons.
The call made the margin deterioration look worse. Gross margin had been 21.4% in Q1 and 19.8% in Q2. It is now well below the 15-18% full-year range management had floated earlier. In the second quarter, the CEO had suggested memory increases were largely being passed through with little margin impact, and the third quarter contradicted that. Adjusted EBITDA swung to a $37.7 million loss after positive results in each of the prior four quarters, including +$0.5 million in Q2. The earlier commitment to positive operating income throughout 2026 was not repeated. Management offered no fourth-quarter margin view, no 2027 outlook and no breakeven timeline. It also warned in the release that memory costs will weigh on margins for the next few quarters.
The operating pipeline is the bullish counterweight, and it is substantial:
- Shipments reached about 721,000 units, up 31% sequentially.
- High-end Antora solutions rose to 30% of shipments from 25% a year ago.
- 21 new models entered mass production, versus 9 in Q2, with six destined for overseas markets.
- The company secured 23 design wins.
- The Flyme software acquisition closed on September 30, bringing cumulative Flyme Auto deployments above 3.5 million.
Additional catalysts include the non-binding Arm MOU, a pending cockpit AI lab with a European luxury automaker, the Volkswagen Latin America program still on track for 2027, and the termination of the remaining convertible facility, which limits dilution. The risks, however, are concrete:
- **Cash:** Cash fell to $53.7 million from $165.5 million after the $191.5 million Flyme payment, which was partly funded with roughly $98 million of new bank borrowing.
- **Debt:** Long-term borrowings rose to $181.8 million from $5.6 million at year-end.
- **Working capital:** Inventories ballooned to $244.5 million.
- **Equity:** The shareholders' deficit widened to $566.9 million.
- **Guidance execution:** The reiterated guide implies roughly $400-$500 million of fourth-quarter revenue, nearly double Q3's level. The inventory build may be positioning for that ramp, but execution risk is high.
- **Concentration:** Geely still accounts for about 75% of revenue.
The market had already turned skeptical before the release. Investor sentiment collapsed from a mildly positive 0.15 after the prior report to -0.58 heading into this one, a genuinely large negative swing. Shares closed at $0.89 before the report, down 19.1% from the open after the August release and 25.6% below the 200-day moving average of $1.20. The stock set a 52-week low of $0.78 on October 27 and entered the print about 14% above that level, near the lower end of its $0.78-$1.15 inter-earnings range. Price and AVWAP trends remain negative, consistent with a market that has been selling into the margin story.
The bottom line is that ECARX is growing volumes and building a credible software and AI platform, but the quarter showed it cannot yet protect profitability against input-cost inflation. It is also financing its strategic ambitions with debt while operating losses mount. The reiterated revenue guide keeps the growth narrative alive. However, it depends on an aggressive fourth-quarter ramp, and management offered no view of margins for that quarter. Until gross margin recovers toward the high teens and cash burn stabilizes, bears have legitimate ammunition, and the deeply negative sentiment looks earned rather than excessive.
Read our earnings preview for ECARX Holdings, Inc.: https://www.earningswhispers.com/article/ECX/21998
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-02 | |
| Oct-30 | |
| Oct-28 | |
| Oct-21 | |
| Oct-06 | |
| Oct-05 | |
| Sep-22 | |
| Sep-17 | |
| Sep-10 | |
| Sep-02 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 |
