Criteo Misses On EPS As Stabilizing Performance Media Collides With A Sharp Retail Media Slowdown
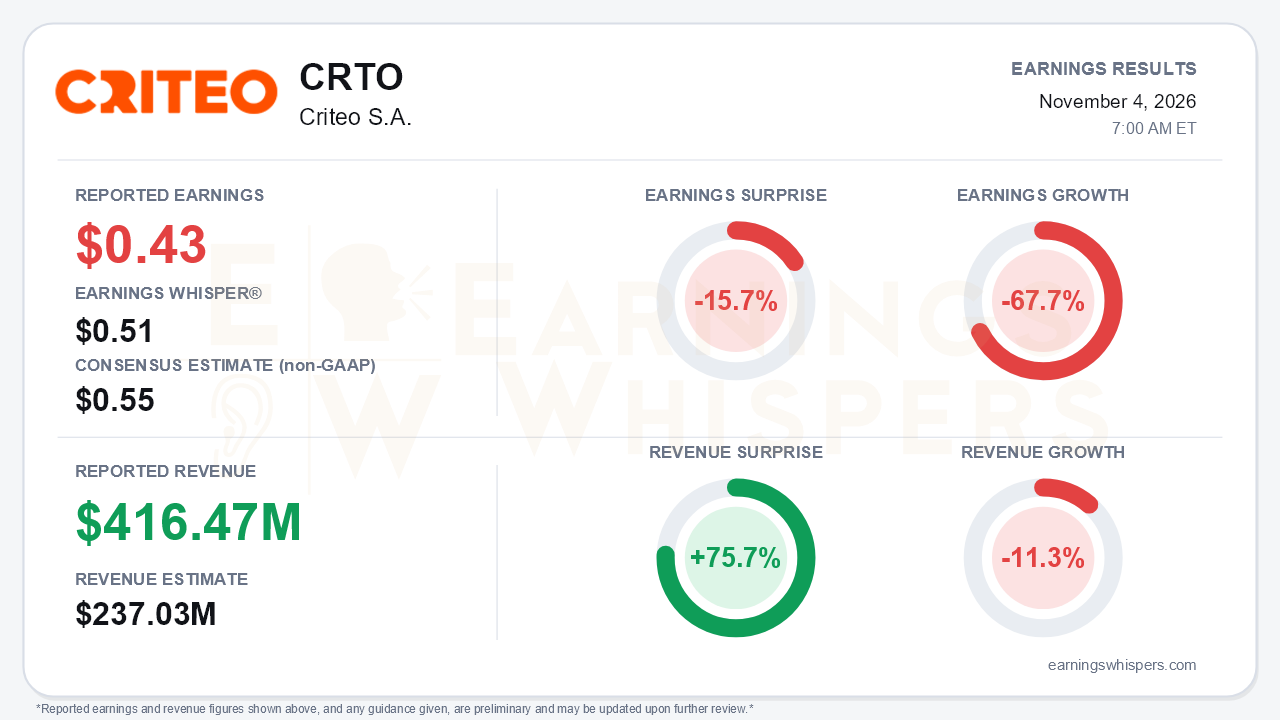
Criteo (NASDAQ: CRTO) delivered a quarter in which stabilization and deterioration arrived together. Adjusted EPS of $0.43 fell short of the $0.55 consensus and the $0.51 Earnings Whisper number, a 15.7% miss, and was down 67.7% from a year ago. Revenue of $416.47 million fell 11.3% year over year. The headline revenue surprise of +75.7% needs context: the $237.03 million consensus sits almost exactly on management's $237–241 million guidance range for Contribution ex-TAC, not reported revenue. On that like-for-like basis, Contribution ex-TAC of $240 million landed near the top of guidance rather than beating it. That is a solid in-line result, not a blowout. The central tension is that management held full-year guidance after two consecutive cuts, while the Retail Media growth engine meant to anchor the recovery lost momentum.
The quality of the quarter deserves scrutiny. Adjusted EBITDA of $65 million beat the $54–58 million guidance range, but the call acknowledged that a one-time bonus accrual reversal helped, so not all of the upside is structural. The EBITDA beat also did not carry through to EPS. GAAP pre-tax income was $22 million, yet the tax provision was $15.9 million. Management flagged an effective tax rate in the high 30s tied to the redomiciliation. As a result, GAAP net income fell to $6 million, or $0.11 per diluted share, from $0.70. Adjusted EBITDA margin compressed to 27% of Contribution ex-TAC from 36%, and gross margin slipped to 50% from 55%. Cash generation weakened as well:
- Quarterly free cash flow fell to $21 million from $67 million.
- Trailing 12-month free cash flow dropped to $134 million from $180 million a quarter earlier.
- Buybacks slowed to $4 million from $30 million in Q2.
Beneath the totals, the two segments moved in opposite directions from what the bull case needs. In Performance Media, spending from large clients was broadly stable versus Q2, ending the downward drift that forced guidance cuts in Q1 and Q2. Yet segment Contribution ex-TAC still fell 13% at constant currency, worse than the 10% decline in Q2 and the 2% decline in Q1. The U.S. remains the weakest market, travel is decelerating and fashion was down 14%. Retail Media is the bigger disappointment. Excluding the $20 million headwind from scope changes at two large clients, underlying Contribution ex-TAC growth slowed to 10% from 20% in Q2 and 24% in Q1. Retail Media media-spend growth eased to 22% from 31%. Management lowered its full-year underlying Retail Media growth outlook to the low teens from the high-teens-to-20% range it had held for three quarters. It also widened the expected reported segment decline, citing launches with larger retailers slipping into 2027 and a slow October start.
The forward catalysts are real but early:
- Performance Connected TV expands to Brazil and Mexico by year-end and to Europe, Canada and Australia in 2027, with the CTV run rate expected to double in Q4.
- The OpenAI advertising integration now covers 89 countries, up from 7, though management still describes ChatGPT budgets as tests.
- Open pipeline opportunities in Performance Media rose 72%, new business spend grew 13%, and the share of spend from new enterprise clients doubled, ramping into the first half of 2027.
- Four of the largest retail partners renewed on multi-year terms.
The risks are more immediate. There is no preliminary 2027 outlook. FX adds roughly $2 million of extra Q4 headwind. Q4 Contribution ex-TAC guidance of $292–298 million implies a 9% to 11% constant-currency decline. New CFO Connor McGogney struck a candid tone, calling it a challenging year and promising a cost-structure review. That is credible, but it is not yet growth.
Investors entered the report already skeptical. Earnings Whispers sentiment fell from -0.15 to -0.24, a meaningful but not dramatic move deeper into negative territory. Shares closed at $15.17 before the release, down 7.8% since the open after the August report. That leaves them 16% below the $18.05 200-day moving average and 20% below the August 14 inter-earnings high of $19.04. The stock set a 52-week low of $13.95 on October 26 and has bounced only about 9% from it. The Earnings Whispers trend readings are mostly negative, with price, momentum and AVWAP all pointing lower and sequential growth neutral.
The bottom line is that Criteo bought itself time rather than a re-rating. Holding full-year guidance, steadier large Performance Media clients and a fast-growing pipeline give the turnaround story a pulse. However, the EPS miss, a partly one-off EBITDA beat, shrinking free cash flow and a sharp slowdown in underlying Retail Media give bears legitimate ammunition. Until CTV, AI channels and the delayed retailer launches show up in Contribution ex-TAC, the market is likely to keep weighing what Criteo is losing today against what it promises for 2027.
Read our earnings preview for Criteo S.A.: https://www.earningswhispers.com/article/CRTO/21691
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-29 | |
| Oct-27 | |
| Oct-21 | |
| Oct-16 | |
| Oct-05 | |
| Sep-16 | |
| Aug-25 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-29 | |
| Jul-22 |
