Aquestive Misses As Suboxone Order Timing Hits Q3 Revenue, But The Quarter Matters Less Than The March 2027 Anaphylm Decision
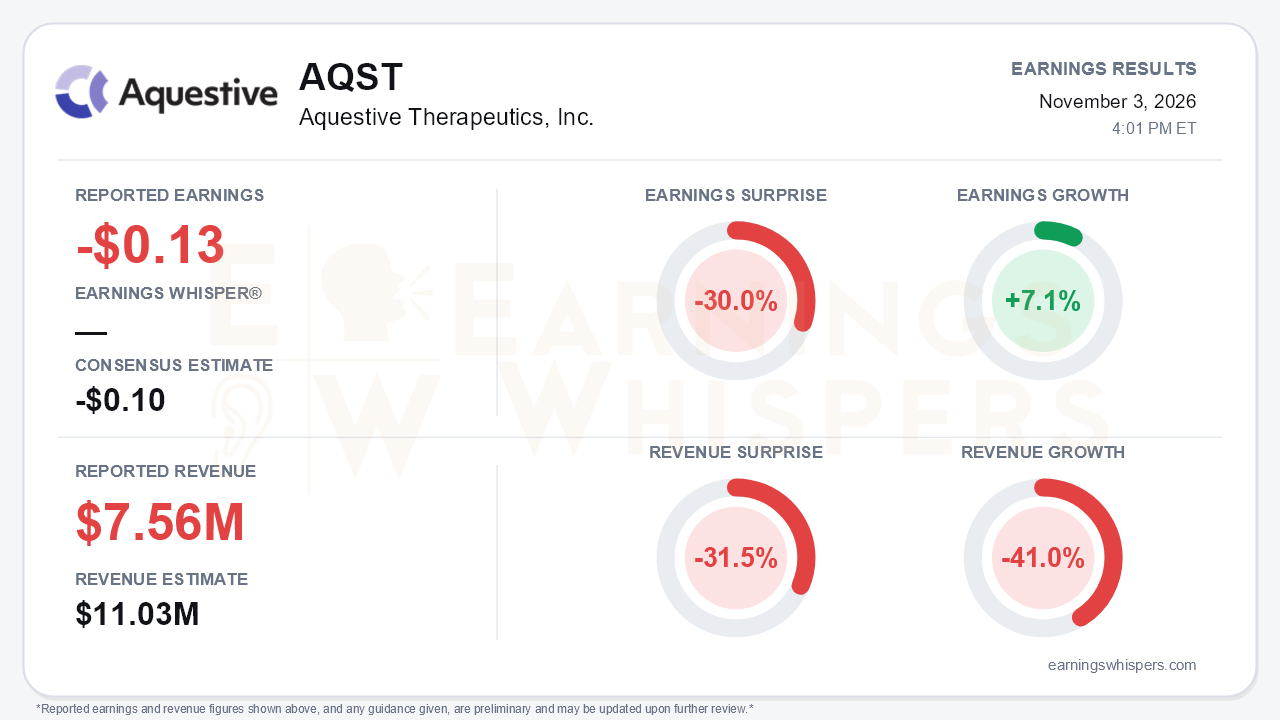
Aquestive Therapeutics delivered a weak third quarter on both lines. The company posted a loss of $0.13 per share, missing the -$0.10 consensus by 30.0%. Revenue of $7.56 million fell 31.5% short of the $11.03 million estimate and dropped 41.0% from a year ago. Reported earnings grew 7.1% year over year, but that figure flatters the quarter. Net loss actually widened to $16.5 million from $15.4 million. The per-share loss narrowed only because the weighted share count rose to about 125.5 million from 110.6 million. The central tension is that the operating quarter deteriorated while the regulatory story advanced. With the FDA now reviewing the Anaphylm resubmission, the quarter's numbers are secondary to a binary event roughly four months away.
The quality of the miss deserves context. The revenue shortfall stems almost entirely from the timing of Suboxone orders. Manufacture and supply revenue fell to $6.7 million from $11.5 million, partly offset by higher Ondif sales. Dose volume supports the timing explanation. Aquestive made about 26 million doses in the quarter versus 44 million a year earlier, yet year-to-date output of 107 million is nearly identical to 2025's 108 million. Nine-month revenue is actually up 14% to $35.8 million. Still, lumpiness has a cost. Gross margin compressed to 52% from 65%, and adjusted EBITDA loss widened to $12.2 million. That is the worst result of the year, versus $8.6 million a year ago, $5.2 million in Q2 and $1.7 million in Q1. Sequentially, revenue fell from $14.4 million in Q1 and $13.8 million in Q2. Bears have legitimate ammunition here: the base business remains dependent on a royalty-era Suboxone franchise whose market share the company itself flags as eroding.
Guidance offered little new information. Management reaffirmed full-year revenue of $46 million to $50 million and an adjusted EBITDA loss of $30 million to $35 million, unchanged across every call this year. That implies a Q4 revenue rebound to roughly $10 million to $14 million and a Q4 loss of about $11 million to $16 million. Cash fell to $90.3 million from $98.5 million in Q2 and $121.2 million at the end of 2025. Part of the decline reflects a sharp drawdown in accounts payable. Management now expects year-end cash of "more than $70 million," up from "approximately $70 million." That improvement is largely bookkeeping, since the new figure includes the $10 million Eton upfront payment. More meaningful is that $75 million from RTW and $20 million from Oaktree remain contingent on approval, which ties the balance sheet's next leg directly to the FDA.
The call was an execution checkpoint rather than an inflection. Aquestive delivered the resubmission it had promised since early in the year, and the FDA accepted it as a Class 2 response with a March 16, 2027 goal date. However, earlier talk of a potentially faster review has faded, and management now anchors on the full six months. The European filing also slipped to Q1 2027, while Canada remains targeted for Q4 2026. On the positive side, the launch build has moved from planning to hiring. District managers are being recruited for a roughly 75-rep force targeting 8,000 to 8,500 allergists, high-prescribing pediatricians and ENTs, and pre-approval discussions have been held with the top four PBMs. Pricing and formulary strategy remain undisclosed, and management acknowledged that payer contracting is difficult. The FDA could also inspect clinical sites or the manufacturing plant before approval. Messaging is pivoting toward pharmacodynamic speed, with new OASIS data due at ACAAI.
The Libervant out-license to Eton adds genuine non-dilutive value. The deal brings $10 million upfront, up to $47.5 million in milestones and a mid-teens royalty, and Aquestive keeps the role of exclusive manufacturer under a 20-year supply agreement. It also stacks the calendar. Libervant's PDUFA date for patients twelve and older is March 23, 2027, and its pediatric label expansion is due March 29, just days after the Anaphylm decision.
Investors are not leaning in. Earnings Whispers sentiment weakened meaningfully, falling to -0.25 from roughly neutral at -0.04 after the prior report. Shares stood at $3.88, down 9.1% from the $4.27 open following the August report and about 7.8% below the 200-day moving average of $4.21. The trend readings are mixed, with momentum positive but price and AVWAP negative. That fits a stock awaiting a catalyst rather than trading on quarterly fundamentals.
The bottom line is that Aquestive's Q3 was a genuine miss with a defensible explanation. Order timing, not collapsing volume, drove the revenue drop. Still, the widest EBITDA loss of the year, continued cash burn and a slipped EU timeline give skeptics something concrete to point to. The investment case now rests almost entirely on the March 2027 decisions for Anaphylm and Libervant, approval-contingent financing, and the company's ability to secure payer access for a novel oral epinephrine product.
Read our earnings preview for Aquestive Therapeutics, Inc.: https://www.earningswhispers.com/article/AQST/21665
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-05 | |
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-27 | |
| Oct-27 | |
| Oct-15 | |
| Sep-29 | |
| Sep-17 | |
| Sep-01 | |
| Aug-12 | |
| Aug-11 | |
| Aug-11 |
