GeoPark's Q3 Earnings Collapse 76% As Differentials And Costs Squeeze Margins, Even As Venezuela And Vaca Muerta Expand The Growth Story
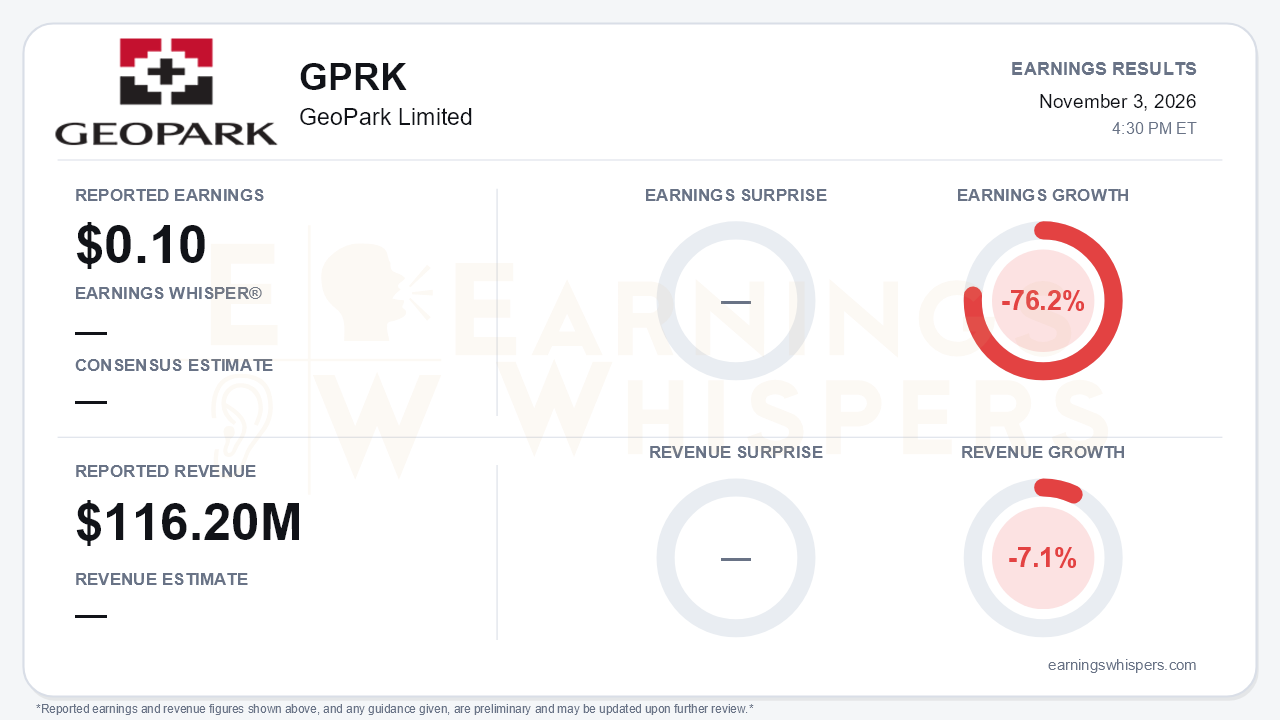
GeoPark Limited (NYSE: GPRK) reported third-quarter earnings of $0.10 per share, down 76.2% year over year, on revenue of $116.2 million, down 7.1%. No consensus estimate was available. The comparison with expectations matters less than the shape of the quarter. Strategically, it may have been GeoPark's most consequential period in years. Financially, it was the weakest quarter of 2026. That is the central tension. The company is adding acreage, a Venezuelan redevelopment project and a fresh $550 million of debt just as margins on its existing barrels compress sharply.
The quality of the earnings deserves scrutiny. Net income of $6.6 million included a $12.4 million income tax benefit, tied mainly to deferred tax adjustments in Argentina. That benefit was larger than the entire bottom line, so the quarter was in the red before taxes. Operating profit fell to $11.6 million from $40.8 million in the second quarter. Adjusted EBITDA dropped 37% sequentially to $45.8 million, and the margin fell to 39% from 51% in Q2 and 56% in Q1.
The pressure came from both price and cost:
- Brent averaged a healthy $91.4, yet the combined realized price fell to $56.2/boe from $67.2.
- The Vasconia discount widened to $6.67 from $1.43.
- Argentina's Medanito swung from a $1.79 premium to a $3.50 discount.
- Hedges subtracted another $36.4 million from revenue because Brent stayed above contracted ceilings.
The per-share decline also reflects a share count that rose to roughly 64.9 million from 51.6 million a year ago.
Costs are the more troubling trend because they are drifting rather than spiking. Operating expense rose to $20.70/boe from $17.90 in Q2 and $14.70 in Q1. The original guidance was $13 to $15, and the latest figure is now above even the revised $17 to $19 range management offered last quarter. Management attributed the increase to electricity costs, well interventions and stronger local currencies; about 85% of the cost base is in local currency. On the call, management pointed to relief in the fourth quarter from fixed-price energy contracts, a roughly 30% grid-rate discount and electricity hedges at about a third of the Q3 rate. Until that relief appears in reported numbers, it remains a management expectation.
Beneath the margin damage, volumes and the growth pipeline moved in the right direction:
- Production rose 3% sequentially to 27,973 boepd. Colombia was stable, and Argentina jumped 51% to about 2,100 boepd, with Pad 1030 producing more than 5,000 boepd gross.
- Argentine operating costs have fallen below $10/boe, versus $29 to $32 at takeover.
- Factory-mode drilling is set to begin in December.
- The Corralera Noreste award expands the Vaca Muerta position to roughly 39,000 acres.
- The Milano 1X discovery is testing around 1,000 boepd.
- In Venezuela, the Bare Block contract became effective in about 65 days, versus the 120 allowed. Management targets operational control before year-end and plans 100 to 150 well reactivations in 2027. Venezuela has moved quickly from an "assessment" in Q1 to a live asset.
Bears still have legitimate ammunition:
- **Cash and leverage.** Free cash flow before debt service was negative $55.5 million, and operating cash flow fell to $16.3 million from $108.4 million. Cash dropped to $253.4 million, and net leverage climbed to 1.6x from 1.2x.
- **Cost of new funding.** The new 2033 notes carry a 9.5% coupon. They reduce near-term refinancing risk and, by management's account, fund 2027 in aggregate, with about $600 to $700 million of liquidity. But they make the balance sheet more expensive.
- **Softer guidance language.** In Q2, management said hedges supported full-year EBITDA above $250 million. This quarter it said only that results should remain within guidance ranges, a quieter message.
- **Capped upside.** The hedge book extends through 2028, with ceilings near $79 to $80, which limits upside if crude stays strong.
- **Dilution and governance.** Possible additional shares for Grupo Gilinski, tied to Venezuelan tax terms, raised dilution and conflict-of-interest questions.
- **Political risk.** Venezuela adds execution and political risk that no hedge covers.
Market data for this report is limited, with no current price or sentiment reading available. For reference, shares opened at $9.44 after the prior report, below the current 200-day moving average of $9.80.
The bottom line is that GeoPark traded near-term earnings quality for long-term optionality this quarter. The tax-aided profit, falling margins, cost overruns and rising leverage show a business absorbing the cost of transition. Venezuela, Corralera Noreste and accelerating Vaca Muerta output keep a credible growth story intact. The next few quarters hinge on whether differentials normalize, whether the promised energy-cost relief brings unit costs back toward guidance, and whether Argentine production ramps fast enough to replace the cash the legacy business is no longer delivering.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Sep-30 | |
| Sep-23 | |
| Sep-15 | |
| Sep-07 |
