Geron Turns Profitable As RYTELO Demand Accelerates, But The Myelofibrosis Failure Leaves A One-Product Story
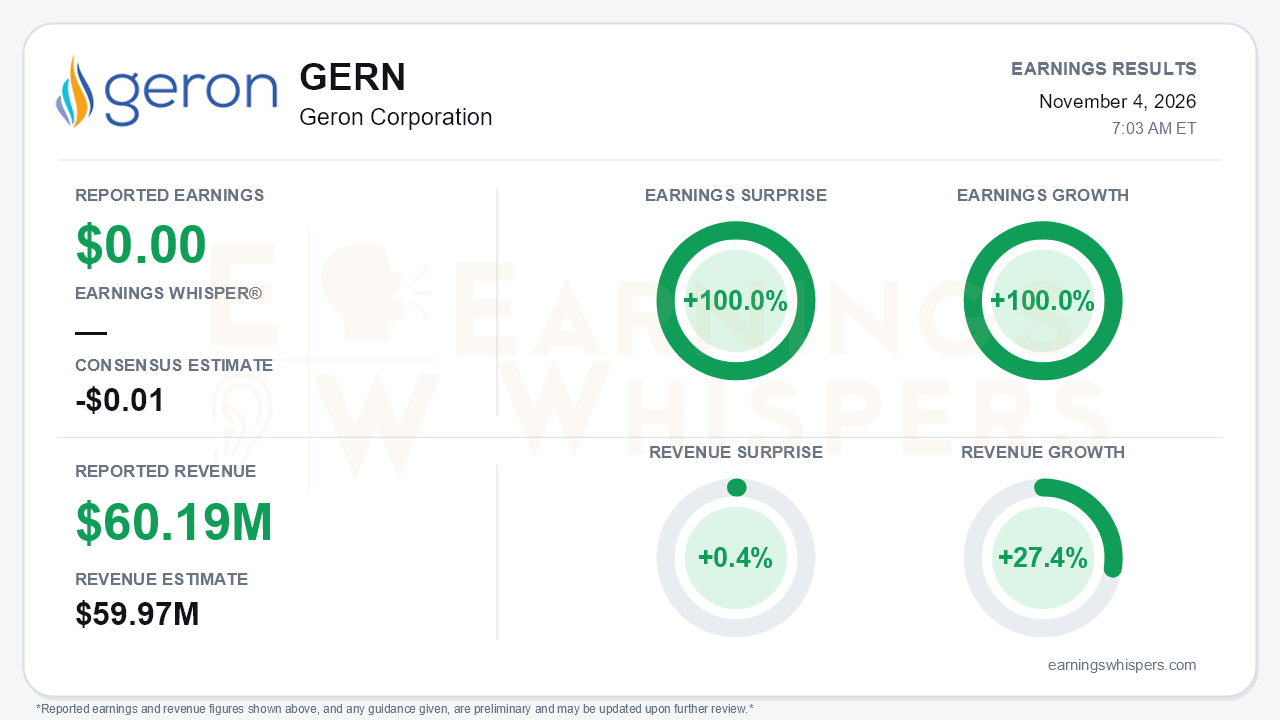
Geron crossed a milestone in the third quarter, reporting breakeven EPS of $0.00 against a consensus estimate for a $0.01 loss. That is a 100.0% earnings surprise and 100.0% year-over-year earnings growth from a $0.03 per-share loss a year earlier. In dollar terms, Geron swung from an $18.4 million net loss to $1.4 million of net income, and operating income reached $5.8 million versus a $13.9 million operating loss. Revenue of $60.19 million edged past the $59.97 million consensus by 0.4% and grew 27.4% year over year. The central tension is that the commercial business is getting better while the pipeline has largely disappeared. The same release that showed Geron's first profit also confirmed the discontinuation of the Phase 3 IMpactMF trial in myelofibrosis. That leaves RYTELO in lower-risk MDS as the entire investment case.
The quality of the profit deserves some scrutiny, because it was driven more by cost cuts than by revenue. Total costs and operating expenses fell to $54.4 million from $61.1 million a year ago. R&D dropped to $12.7 million from $21.1 million, down from roughly $22 million in Q2, as personnel and clinical costs came out. SG&A also declined. Cost of goods sold, however, jumped to $6.1 million from $1.0 million on non-cash inventory-related charges, which shows the headline still carries some noise. Below the operating line, $7.2 million of interest expense against $3.0 million of interest income remains a real drag. A $1.4 million profit is a thin cushion, not yet a durable earnings stream.
The call told a more encouraging story about demand than the revenue line did. Year-over-year net revenue growth improved to 27% from 17% in Q2, but sequential growth slowed to 5% from 11%. That slowdown came even as underlying demand accelerated to 10% quarter over quarter, up from 5% in Q2 and 6% in Q1. The supplied materials do not explain the gap between demand and net revenue. It is a timing question worth watching, especially since gross-to-net actually improved to 19.3% from 20.7%. Breadth is clearly expanding:
- Ordering accounts rose to roughly 1,700 from about 1,575 in Q2 and 1,450 in Q1.
- First- and second-line patient starts climbed to 38% on a rolling 12-month basis, up from 34%, 33% and 30% over the prior three quarters.
- Management attributed the acceleration to community practices, which it views as evidence of a long U.S. growth runway.
Guidance moved in a constructive but measured direction. Geron reaffirmed 2026 RYTELO revenue at the mid-to-high end of $220 million to $240 million. Against $169.4 million of nine-month product revenue, that implies fourth-quarter sales of roughly $61 million to $71 million. Operating expense guidance was cut to $220 million to $230 million from $230 million to $240 million. Europe has moved from exploration to execution, with a gated launch putting RYTELO in Germany by year-end and France in 2027. On the call, management noted that orphan drugs such as RYTELO are excluded from the CMS GLOBE model, which supports ex-U.S. pricing flexibility. Business development has also become explicit, with Geron now hunting for community-focused heme/onc assets carrying a few hundred million dollars in peak sales each. Six ASH abstracts provide a near-term scientific calendar.
Bears still have legitimate ammunition. The myelofibrosis interim analysis had been framed as an upside catalyst as recently as Q2, and it is now gone along with the label-expansion thesis. MF wind-down costs will linger, and management flagged higher operating expenses in 2027 for the European rollout and post-marketing commitments. That could compress the newfound profitability just as it arrives. Future diversification depends on deal execution that has not yet happened.
The market had already priced in much of that disappointment. Shares closed at $0.93 ahead of the report, down 32.1% from the $1.37 open after the August release and 34.6% below the 200-day moving average of $1.42. The stock hit a 52-week low of $0.84 on October 28 and sits only 10.7% above it, far from the $1.65 quarterly high set in mid-August. Investor sentiment remained negative and weakened modestly, slipping to -0.417 from -0.352. The Earnings Whispers trend signals are mixed: sequential growth and momentum readings are positive, while price and AVWAP trends remain negative. That split mirrors the gap between improving operations and a damaged share price.
The bottom line is that Geron delivered the operating proof points RYTELO bulls wanted: accelerating demand, broader account penetration, deeper early-line use, lower spending and a first profitable quarter. But the pipeline failure turns Geron into a single-product company whose next leg depends on European execution and business development. The sequential slowdown in net revenue and the expected 2027 spending increase mean the profit milestone has to be defended, not simply celebrated.
Read our earnings preview for Geron Corporation: https://www.earningswhispers.com/article/GERN/21704
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Oct-30 |
Geron winds down Phase III rare blood cancer trial after muted efficacy
GERN -5.47%
Clinical Trials Arena
|
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-21 | |
| Oct-19 | |
| Oct-13 | |
| Oct-12 | |
| Sep-25 | |
| Sep-18 | |
| Sep-02 |
