Greif Misses Q4 EPS By 20% As Demand Relapses, But Bigger Cost-Savings Target Keeps The Self-Help Story Alive
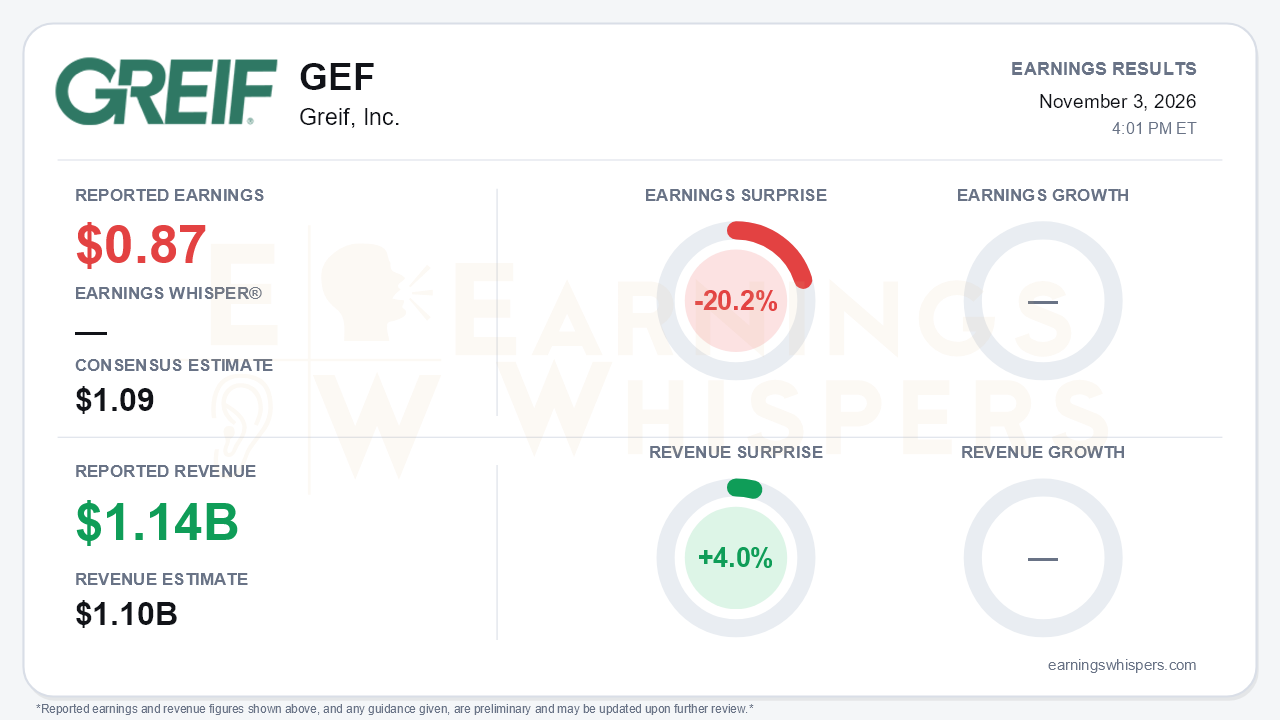
Greif delivered a fiscal fourth quarter that split cleanly into two stories. Adjusted earnings of $0.87 per share fell well short of the $1.09 consensus, a 20.2% miss. Revenue of $1.144 billion beat the $1.10 billion estimate by 4.0%. The revenue beat came mostly from pricing rather than demand. Volumes, which had turned positive across every segment in the third quarter, rolled over again. Management responded by leaning harder on cost-cutting. It reported $105 million of run-rate savings and raised the target to $150 million by the end of fiscal 2027. That is the central tension: Greif's self-help engine is accelerating while the end markets it was meant to bridge are weakening again.
The quality of the quarter deserves scrutiny. Adjusted EPS did rise from $0.58 a year ago, and net income excluding adjustments climbed 46.1%. But adjusted pre-tax income was essentially flat at $89.3 million versus $90.9 million. The year-over-year gain came largely from a lower adjusted tax rate, which fell to 42.2% from 53.9%, and from a smaller share count after $225 million of buybacks during the year. A 42.2% adjusted tax rate is itself an obvious contributor to the miss against consensus. Adjusted EBITDA fell 3.1% to $163.0 million. Management attributed $18.2 million of the drag to the timing of prior-year incentive accrual changes, and excluding that item EBITDA grew 8.7%. Even on that friendlier basis, the comparison is a sharp slowdown from roughly 25% growth in the third quarter. On a GAAP basis, the continuing-operations loss narrowed to $0.11 per share from $0.42. The current-period loss was weighed down by $36.5 million of impairments tied to the Sweetwater paperboard mill closure.
The segment detail shows a pricing story masking soft demand. Customized Polymer Solutions grew sales 10.4% on a 12.4% price/mix contribution, but volume fell 2.3% and segment EBITDA was flat at $44.5 million. Resin cost flow-through compressed gross margin. Durable Metal sales were flat, with volume also down 2.3%. Sustainable Fiber EBITDA dropped $9.5 million to $52.0 million on higher raw material and manufacturing costs. Innovative Closure Solutions was the clear bright spot. EBITDA roughly doubled to $10.3 million, and gross margin widened by about 490 basis points despite a 3.5% volume decline. On the call, management blamed small-container destocking and a weak agricultural season tied to elevated resin costs. Its tone shifted noticeably. Last quarter it was "encouraged by the direction of travel"; now it sees "no convincing signs of a broad recovery." Year-over-year EBITDA margin expansion slowed to about 60 basis points excluding the accrual, down from 260 basis points in the third quarter.
The forward setup offers real catalysts but also some quiet retreats. Fiscal 2027 low-end guidance calls for $645 million of adjusted EBITDA, up from $625.7 million in fiscal 2026, and $290 million of adjusted free cash flow. The bridge includes about $60 million of price-cost benefit, $33 million of it from the September uncoated recycled board price increase relative to OCC costs. Offsetting that are roughly $20 million of non-raw-material inflation and $30 million of SG&A headwinds. The cost-savings target also needs context. The release frames $150 million as a 50% increase over the original $100 million commitment, while the call notes the interim target had already been reiterated at $120 million. The retreats are concrete:
- Fiscal 2026 adjusted free cash flow of $279.3 million missed the third-quarter guide of $305 to $325 million, reflecting a deliberate resin inventory build amid Middle East supply disruptions.
- The long-standing $1 billion EBITDA ambition was reframed to roughly $750 million normalized, with no fixed timeline.
- Leverage ticked up to 1.2x from 1.1x last quarter, although it remains well below the 1.7x of a year ago.
- Capital spending rises to $185 million for growth projects in polymers and closures.
The market had already been cooling on the name. Shares were at $81.25, down 6.1% from the $86.53 open following the July report. They still sit about 8.9% above the 200-day moving average of $74.58, so the longer-term uptrend has not been broken. Investor sentiment remained modestly negative and edged slightly lower, from -0.13 to -0.15. That reflects mild disappointment rather than capitulation. The Earnings Whispers trend readings are mixed, with momentum positive while AVWAP remains negative.
The bottom line is that Greif is increasingly a pure execution story. Its earnings growth is now being manufactured by cost savings, pricing, a lower tax rate and buybacks rather than by volume. That approach can keep the fiscal 2027 floor credible. However, the fourth-quarter demand relapse, the cash-flow miss and the softened long-term target give bears legitimate ammunition. Investors will need visible progress toward the $150 million savings goal to offset a market that management itself no longer expects to help.
Read our earnings preview for Greif, Inc.: https://www.earningswhispers.com/article/GEF/21577
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-13 | |
| Sep-30 | |
| Sep-17 | |
| Sep-16 | |
| Aug-25 | |
| Jul-29 | |
| Jul-28 | |
| Jun-30 | |
| Jun-17 | |
| Jun-16 | |
| Jun-10 |
