Insulet Beats On Record Margins, But A Pre-Cut 2027 Outlook And Stalling U.S. Patient Starts Shift The Story
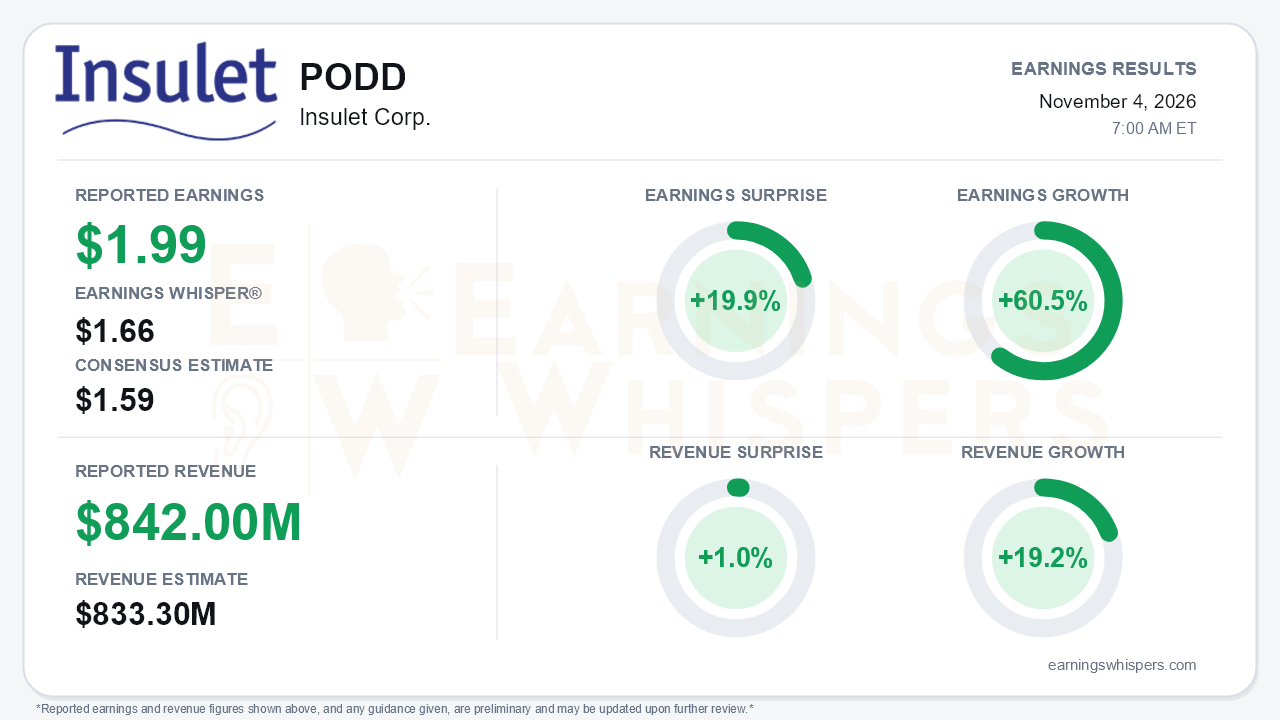
Insulet (NASDAQ: PODD) delivered a clean third-quarter beat. The guidance commentary, however, changes the investment debate more than the headline numbers do. Adjusted earnings of $1.99 per share topped the $1.59 consensus by 19.9% and cleared the $1.66 Earnings Whisper number. EPS grew 60.5% year over year. Revenue of $842.0 million rose 19.2%, or 19.6% in constant currency, and beat consensus by 1.0%. It also landed slightly above the top of management's 17.5%-19.5% range. On the same call, management walked back its 2027 growth ambitions, acknowledged share loss to new tubeless competitors and disclosed that U.S. new customer starts were flat. The quarter looked strong, but the forward trajectory weakened. That is the central tension.
The quality of the beat deserves some scrutiny, although profitability gains were real. Adjusted gross margin reached a record 74.2%, up 200 basis points, after 72.9% in Q2 and 71% in Q1. Adjusted operating margin climbed to 22.0% from 17.1% a year ago and 19.3% last quarter. GAAP EPS of $2.03 ran above the adjusted figure because of a $7.2 million gross-profit benefit from revised warranty estimates tied to the March and May voluntary medical device corrections. Revenue had its own one-time help. International Omnipod sales grew 33.0% in constant currency, ahead of the 28%-30% guide, but roughly 250 basis points of that came from reserve adjustments in France and Canada. Meanwhile, U.S. Omnipod growth of 14.7% marks a clear slowdown from 28% in Q1 and 20% in Q2. U.S. pricing also dipped slightly.
Beneath the headline, demand is cooling. Global new customer starts slowed to low single-digit growth. U.S. starts were flat year over year, a sharp turn from the second-highest quarter ever in Q2 and record starts in Q4 2025. Fourth-quarter U.S. guidance of 10%-13.5% implies a steep exit-rate deceleration. For 2027, management now expects:
- total growth modestly below mid-teens, after targeting growth at or above the mid-teens exit rate just one quarter ago;
- U.S. growth at the low end of its 9%-14% framework;
- international growth to moderate meaningfully as the Dash-to-Omnipod 5 price-mix tailwind fades.
Management also said explicitly that it expects to cede a couple of share points of new customer starts to new tubeless entrants. Two of three 2027 PBM contracts remain unfinalized. The tone has shifted across recent calls, from confident long-range 20% growth earlier in the year, to an accountability-driven reset in Q2, to a framing management now calls conservative.
The 2026 numbers, by contrast, moved up modestly:
- Total constant-currency growth narrowed to 21%-22% from 20%-22%.
- International guidance rose to 32%-33%, the fourth consecutive increase.
- Adjusted operating margin expansion was lifted to roughly 150 basis points from about 100.
- Adjusted EPS growth remains above 30%.
Cash generation is the weak spot. Free cash flow is now expected near $275 million, well below the roughly flat-versus-$375-million-plus outlook from earlier in the year. Nine-month capex doubled to $113.9 million, and receivables and inventory both climbed. Even so, the board added a $1 billion repurchase authorization and plans about $400 million of buybacks in Q4, funded from existing cash, on a balance sheet that held $584 million at quarter-end.
Pipeline catalysts offer bulls something to hold onto:
- The final Omnipod 6 510(k) has been submitted, with launch still targeted for 2027.
- EVOLVE pivotal enrollment is complete for type 2 fully closed-loop delivery, with a 2028 launch targeted.
- Omnipod Discover reached 35,000 users and 5,000 clinicians, up from 12,000 and 1,600 in Q2.
- Libre 3 Plus integration expanded to ten more markets.
- Type 2 retention improved modestly following the commercial action plan and a roughly 25% larger U.S. sales footprint.
None of these address the near-term new-patient slowdown, however.
The market setup is more complicated than the surprise implies. Investor sentiment remained negative but improved meaningfully into the report, rising from -0.33 to -0.18. Shares had rallied 21.0% from the $128.00 open after the August report and closed the pre-report session at $154.86, just 1.4% below the inter-earnings high. That rebound followed a 52-week low of $126.40 set the day of the prior release. Even after the recovery, the stock sat about 13% below its $178.02 200-day moving average. The broader trend readings lean positive, though momentum remains negative. In short, the stock entered the print with expectations partially rebuilt and price near the top of its recent range. That is not an ideal setup for a report whose most important message is a lower 2027 trajectory.
The bottom line is that Insulet executed well on margins and EPS, but the quarter shifted the debate from profitability to durability of growth. Flat U.S. starts, explicit competitive share loss, a sharply slower Q4 U.S. guide and a reduced 2027 framework give bears legitimate ammunition. The buyback and the Omnipod 6 and type 2 pipelines are the key offsets. Until new customer starts stabilize, record margins may not be enough to carry the story.
Read our earnings preview for Insulet Corp.: https://www.earningswhispers.com/article/PODD/21730
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 6 hours | |
| 7 hours | |
| Nov-03 | |
| Oct-27 | |
| Oct-21 | |
| Oct-12 | |
| Oct-07 | |
| Oct-01 | |
| Sep-18 | |
| Sep-14 | |
| Sep-14 | |
| Sep-01 | |
| Aug-26 | |
| Aug-26 |
