Scotts Miracle-Gro Narrows Its Miss Risk But Not Its Growth Problem: Q4 Loss Beats As Sales Slide And FY27 Guide Leans On Pricing And An Acquisition
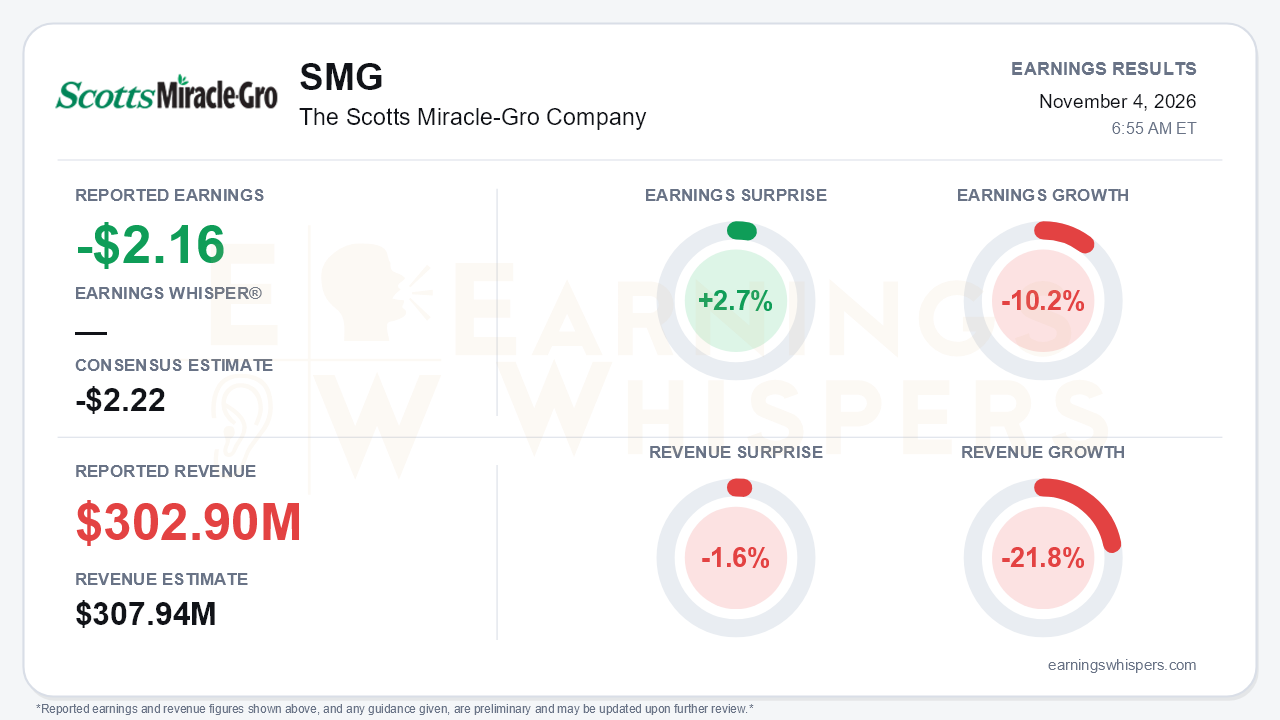
Scotts Miracle-Gro (NYSE: SMG) delivered a seasonal fiscal fourth-quarter loss that was better than feared, but the top line went the other way. The adjusted loss of $2.16 per share beat the consensus estimate of a $2.22 loss by 2.7%. Revenue of $302.9 million missed the $307.94 million consensus by 1.6%. On a year-over-year basis, earnings fell 10.2% because the loss widened from $1.97 a year earlier.
Revenue fell 21.8% year over year on Earnings Whispers' normalized basis. The company's release shows an 11% decline after restating prior-year results to remove the divested Hawthorne business, and that difference in comparison basis appears to explain the gap. On either measure, the quarter shrank. The central tension is that SMG hit nearly every full-year financial commitment while its core consumer business grew more slowly than its category. Management is now asking investors to underwrite a fiscal 2027 plan that leans on pricing, cost controls and an acquisition rather than on organic volume.
The quality of the quarter deserves scrutiny. GAAP gross margin turned negative at -0.7%, compared with 4.8% a year ago, and adjusted gross margin fell from 5.2%. U.S. Consumer sales dropped 10% and that segment's loss widened to $74.7 million. Corporate costs rose to $46.3 million from $36.7 million. Adjusted EBITDA deteriorated to a $106.7 million loss from an $86.1 million loss.
The company also excluded $13.5 million of IT transformation costs from SG&A, the first installment of a project expected to exceed $100 million through fiscal 2028. A larger tax benefit cushioned the bottom line.
The full year looks better on paper:
- Adjusted EPS of $4.48 rose 18% and topped the raised $4.30 to $4.45 range.
- Adjusted gross margin expanded 80 basis points to 32.4%.
- Free cash flow of $278.4 million edged past the $275 million target.
The composition of that growth matters, though. Adjusted EBITDA grew only 2%, while interest expense fell to $112.6 million from $129.0 million and stock-based compensation also declined. Much of the EPS leverage came from below the operating line. Year-end cash stood at just $7.4 million, and net leverage was 3.89x.
The call was candid about demand. Full-year sales grew just 1%, at the low end of guidance, and branded point-of-sale rose only about 1%. Earlier in the year, branded sales had been tracking up 4.5% year to date. Management conceded it did not capture its full share of a category growing 5% or more.
There were genuine bright spots:
- E-commerce point-of-sale jumped 24% and now represents about 13% of sales.
- Miracle-Gro organic grew roughly 18%.
- Pre-emergent units rose 16%.
Those wins have not yet been enough to move the consolidated top line.
Fiscal 2027 guidance calls for sales growth of 2% to 4%, continued adjusted gross margin expansion and adjusted EPS of $4.70 to $4.90, roughly 8% to 12% growth. That outlook came in above estimates, but its building blocks are telling:
- The Black Cow acquisition, closed October 1 for $55 million, is expected to contribute 1 to 2 points of sales growth.
- Targeted pricing is about 4% gross, or roughly 2% net of elasticity.
- Supply chain savings are expected to reach $35 million or more.
Against that, management flagged roughly $100 million of commodity and freight inflation tied to the Iran conflict. Retailer inventories are up low single digits, which management framed as a low-single-digit sales headwind. First-half sales are expected to be roughly flat. Gross margin expansion is framed at the low end of the 50 to 100 basis-point algorithm.
With about 55% of cost of goods sold already locked and urea more than 80% secured, management says the plan holds even if sales are flat to slightly down. That provides some insulation, but it also signals that organic acceleration is not the base case. The new SMG Professional unit, the Turf Builder relaunch and an organic Ortho line are catalysts, yet they remain unproven at scale.
Capital returns have also cooled. Earlier in the year, management talked up an active buyback program. Repurchases under the $500 million authorization are now described as opportunistic rather than planned, and the 3.0x to 3.5x leverage target is set for the end of fiscal 2029. Bears have legitimate ammunition here: the balance sheet is still the binding constraint.
Investor expectations softened into the report. Earnings Whispers sentiment moved from -0.035 to -0.106, a modestly more negative reading rather than a dramatic shift. The stock is down 14.6% since opening at $72.37 after the July report, which marked the inter-earnings high. Shares then slid to a 52-week low of $47.90 on September 29. They have since rebounded 29% to $61.80, which leaves them essentially on the 200-day moving average of $61.88. The stock therefore enters the new fiscal year at neither extreme, having recovered much of a sharp drawdown without reclaiming its post-July level.
The bottom line is that SMG executed on margins, cash flow and full-year EPS. However, the fourth quarter exposed a business still struggling to grow organically, and the fiscal 2027 guide depends heavily on pricing, hedges and Black Cow to offset inflation and retailer destocking. Until branded sell-through starts catching up with the category, the earnings story will rest more on cost discipline than on demand.
Read our earnings preview for The Scotts Miracle-Gro Company: https://www.earningswhispers.com/article/SMG/21741
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 4 hours | |
| 4 hours | |
| Nov-03 | |
| Oct-29 | |
| Oct-27 | |
| Oct-26 | |
| Oct-06 | |
| Sep-15 | |
| Sep-07 | |
| Sep-03 | |
| Aug-31 | |
| Aug-19 | |
| Aug-14 | |
| Aug-13 |
