Stanley Black & Decker's Big Beat Rests On Tariff Refunds, But Power Tools Momentum Is Real And Accelerating
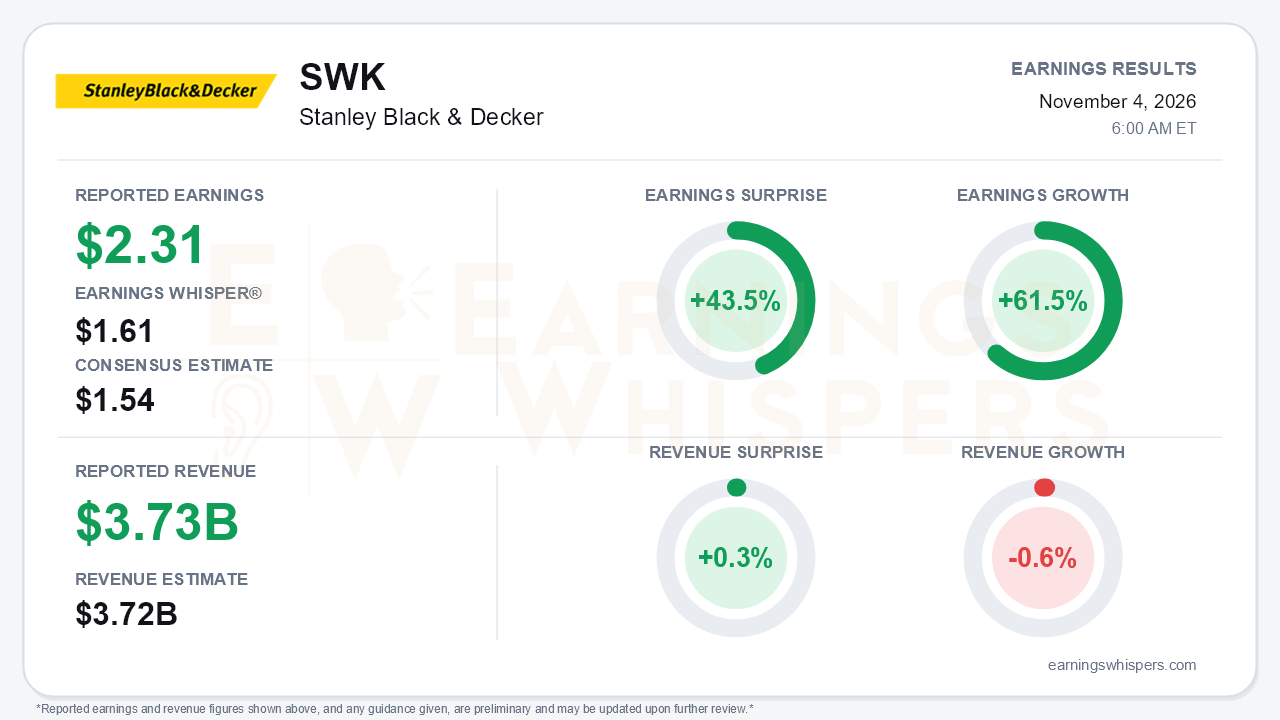
Stanley Black & Decker delivered a headline beat that needs to be read with care. Adjusted EPS of $2.31 topped the $1.54 consensus by 43.5% and cleared the $1.61 Earnings Whisper number with room to spare. Earnings grew 61.5% year over year. Revenue of $3.732 billion edged past the $3.72 billion consensus by 0.3% but fell 0.6% from a year ago as divestitures weighed on the top line. The central tension is that roughly $0.67 of the quarter's EPS came from net IEEPA tariff refunds. Strip that out and adjusted earnings land near $1.64, only modestly above the whisper number. The refund turned a solid quarter into a blowout, yet the operating story underneath is still worth paying attention to.
The refund ran through nearly every line of the income statement. Adjusted gross margin of 39.4% was up 780 basis points, and about 430 basis points of that came from net refunds. Even so, the call indicated gross margin stayed above 35% excluding the benefit, a meaningful step up from 33.7% in the second quarter and 30.2% in the first. SG&A rose 320 basis points to 24.2% of sales as management reinvested part of the windfall in growth spending and variable incentive compensation. On a GAAP basis, EPS jumped to $1.83 from $0.34. Free cash flow of $585 million in the quarter brought the year-to-date total to $836 million. That funded $250 million of buybacks, which completed the prior $500 million authorization, and the Board added a new $1 billion program.
The more durable development is the volume trend in Tools & Outdoor. Companywide organic growth improved to 4%, up from 3% in the second quarter and flat in the first. Segment volume rose 7%, after 3% and -5% in the two prior quarters. Power tools grew 10% organically, North America grew 6%, and the U.S. commercial and industrial channel strengthened further from low double digits. DeWalt, Stanley, and Craftsman all grew organically for a second straight quarter. Tools & Outdoor adjusted segment margin reached 17.6%. Management credited productivity and mix, alongside the refund contribution. This is the evidence that the brand activation effort is gaining traction, and it is not a tariff artifact.
The weaker parts of the business are concentrated but real.
- Tools & Outdoor pricing fell 3%, after being flat in the second quarter, amid continued promotional intensity.
- Full-year organic pricing is now expected to be roughly flat.
- Outdoor organic revenue fell 12%, worse than the -7% decline in the second quarter.
- Engineered Fastening organic growth slowed to 2%, from 3% and 7% in earlier quarters, as automotive turned to -2%.
- Management cut the segment's full-year outlook to low single-digit growth with flat margins.
- The implied fourth-quarter Tools & Outdoor margin steps down to roughly the mid-12% range as reinvestment continues.
Looking ahead, management flagged building inflation in steel, electrical components, resins, and battery metals. It plans a price increase around the turn of the year and expects tariffs to return to former IEEPA levels, so 2027 depends partly on industry-wide price acceptance.
Guidance rose for a second straight quarter. Adjusted EPS is now expected at $5.95 to $6.25, up from $5.20 to $5.80. Free cash flow guidance moved to $1.0 to $1.2 billion from $600 to $800 million. The quality of the raise deserves scrutiny, though. Most of it reflects refunds already banked, while underlying operating expectations were reaffirmed rather than raised. Two other developments offer forward support. The pending sale of Excel, which includes Hustler mowers with about $300 million in revenue, should close around year-end. An initial 2027 framework calls for SG&A near 23% of sales and gross margin at or near 35%. That is a credible bridge to a refund-free baseline, but not a step change from it.
The market setup is more complicated than the surprise implies. Shares closed at $104.62 heading into the report, up 13.2% since the opening after the July release and 22% above the 200-day moving average. They had rallied about 22% from an October 8 low to within 2.8% of a 52-week high of $107.67 set on November 2. Investor sentiment moved the other way, slipping from a slightly positive 0.06 to -0.15 before the report. That suggests a growing share of investors were skeptical even as the stock climbed. The Earnings Whispers trend signals are mostly positive, with sequential growth neutral. With the stock near the top of its range, much of the improvement may already have been recognized in the price.
The bottom line is that Stanley Black & Decker's beat was inflated by a one-time tariff windfall. Beneath it sits a genuinely improving core: accelerating power tools volume, broad brand growth, and margins rebuilding toward a 35% gross margin baseline. Bears have legitimate ammunition in negative pricing, automotive and outdoor weakness, a softer fourth-quarter margin, and 2027 inflation. With the stock entering the report near its highs while sentiment cooled, the next leg depends on whether volume momentum and pricing actions can carry earnings once the refunds are gone.
Read our earnings preview for Stanley Black & Decker: https://www.earningswhispers.com/article/SWK/21746
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 5 hours | |
| 5 hours | |
| 5 hours | |
| Nov-02 | |
| Oct-29 | |
| Oct-27 | |
| Oct-19 | |
| Oct-19 | |
| Oct-16 | |
| Oct-16 | |
| Oct-09 | |
| Oct-08 | |
| Oct-07 | |
| Oct-06 |
