Trimble Misses The Whisper As An ARR Growth Cut Overshadows Margin Gains
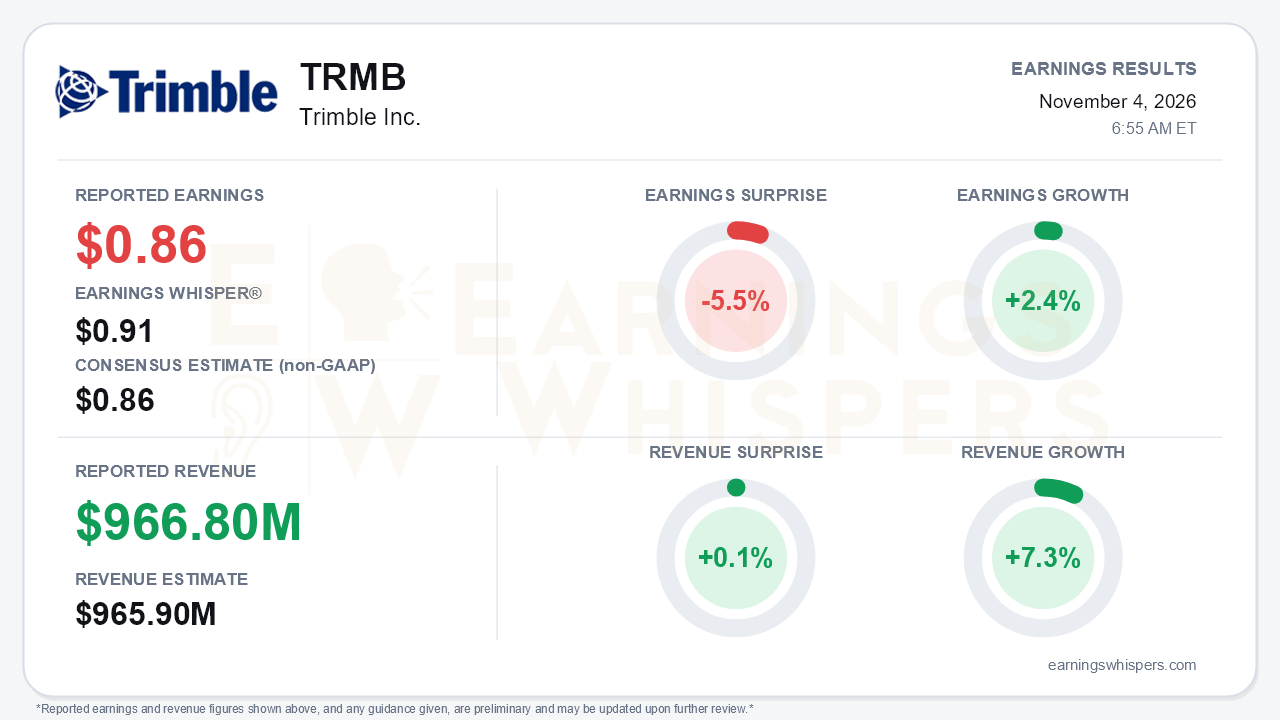
Trimble (NASDAQ: TRMB) delivered a quarter that met Wall Street's numbers but fell short of what investors were looking for, and the conference call explains why. Non-GAAP earnings of $0.86 per share matched the consensus estimate but missed the $0.91 Earnings Whisper number by 5.5%. Revenue of $966.8 million rose 7.3% year over year and edged past the $965.9 million consensus by 0.1%. The bigger problem is that earnings grew only 2.4% from a year ago. That is a sharp slowdown from the first half: nine-month non-GAAP EPS reached $2.51 versus $2.13 a year earlier. The central tension is clear. Management nudged profitability targets higher while cutting full-year annualized recurring revenue (ARR) growth to about 10% from 12-14%. That ends a three-quarter run of beat-and-raise reports and undercuts the metric that anchors the subscription-transition story.
The quality of the quarter deserves scrutiny. Non-GAAP operating margin slipped to 27.2% from 28.2% a year ago. Non-GAAP gross margin fell to 70.5% from 71.2%, a sharp reversal from Q2's 71.8%, as hardware mix and supply-chain pressure weighed on results. Field Systems carried most of the damage: its segment operating margin fell to 29.5% from 33.4% even as revenue grew to $435.8 million. AECO was the bright spot, with revenue up to $395.0 million and margin expanding 170 basis points to 33.5%. On a GAAP basis, diluted EPS fell to $0.25 from $0.46. A 51.3% tax rate and higher restructuring charges drove that decline, so the GAAP drop says more about tax and one-time items than core operations. Cash generation looks strong on paper: nine-month free cash flow was $643.6 million versus $206.2 million. However, the prior-year figure was depressed by a large tax payment, and management trimmed expected free-cash-flow conversion to about 0.9x from roughly 1.0x.
The deceleration in recurring revenue is broad rather than isolated:
- **Company-wide ARR:** growth has stepped down from 14% in Q4 FY25 to 13%, 12%, and now 10%, with about 10% guided for Q4.
- **Field Systems:** ARR growth collapsed from 12% in Q2 to 5% and is now guided to low single digits. Management cited weak agricultural positioning services in South America, lower-than-modeled renewal conversion on bundled correction subscriptions, and soft European demand.
- **Transportation & Logistics (T&L):** ARR growth slipped to 5% from 7%. Weaker Transporeon volumes and spot mix contradict the "green shoots" framing from last quarter.
- **AECO:** growth eased to 13% from 14%, though the segment's underlying health remains solid. Net retention is near 110%, backlog is up 13%, and management expects Q4 net new ARR above $200 million.
Management's tone shifted accordingly, from "exceptional" in Q2 to "pleased, notwithstanding near-term ARR headwinds."
The call did preserve a credible profitability story. The full-year non-GAAP EPS midpoint rose to $3.66 from $3.65, within a $3.63-$3.69 range. The revenue midpoint held at $3.925 billion despite currency effects and a divestiture. Management raised the AECO margin target to 36% and the T&L target to 25%. Q4 guidance calls for revenue of $1.031-$1.061 billion and non-GAAP EPS of $1.13-$1.19. The AI narrative offers real data points:
- Trimble Connect API calls topped 30 billion, up 25%.
- SketchUp AI credit consumption doubled sequentially.
- AI takeoff adoption tripled to 19% of estimating users.
- Machine-control-as-a-service bookings grew more than 50%.
Looking ahead, 2027 faces a roughly $90 million revenue and operating-income headwind from the absence of a January 1 term-license renewal. Management launched an $80-90 million efficiency program to offset it and expects 2027 EPS growth at the high end of low-to-mid teens, excluding that calendar effect. The T&L strategic review remains open with no timeline, an overhang given the segment's earlier $562 million goodwill impairment. Buybacks continue: the release cites about 4.0 million shares repurchased for $231.7 million in the quarter, slightly above the $224 million figure referenced on the call.
The market setup made the miss more consequential. As of the pre-report snapshot, shares were up 10.4% since the open after the August report, at $65.61. That left the stock 7.9% above its 200-day moving average and just 2.5% below its inter-earnings high of $67.27, set two days before the report. A stock trading near the top of its range invites a higher bar, which the $0.91 whisper reflected. Investor sentiment had already cooled, falling from 0.16 to 0.04. It remains marginally positive but is noticeably less enthusiastic. Momentum and AVWAP trend readings were positive heading into the print, which shows how much optimism was embedded in the price.
The bottom line is that Trimble is trading growth for margin at an awkward moment. Bulls can point to rising EPS guidance, AECO strength, expanding segment margin targets, and visible AI traction. Bears have legitimate ammunition: four straight quarters of ARR deceleration, a collapse in Field Systems recurring growth, gross-margin slippage, and a known 2027 headwind. Until ARR stabilizes, the margin story alone may struggle to justify a stock priced near its quarterly highs.
Read our earnings preview for Trimble Inc.: https://www.earningswhispers.com/article/TRMB/21752
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 41 min | |
| 6 hours | |
| 7 hours | |
| 9 hours | |
| 10 hours | |
| Oct-27 | |
| Oct-21 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-12 | |
| Oct-06 | |
| Oct-05 | |
| Oct-05 | |
| Oct-05 |
