Versigent Beats On Q3 And Lifts Cash Flow Outlook, But Organic Growth Slows To ~1% And The Q4 Margin Guide Points Lower
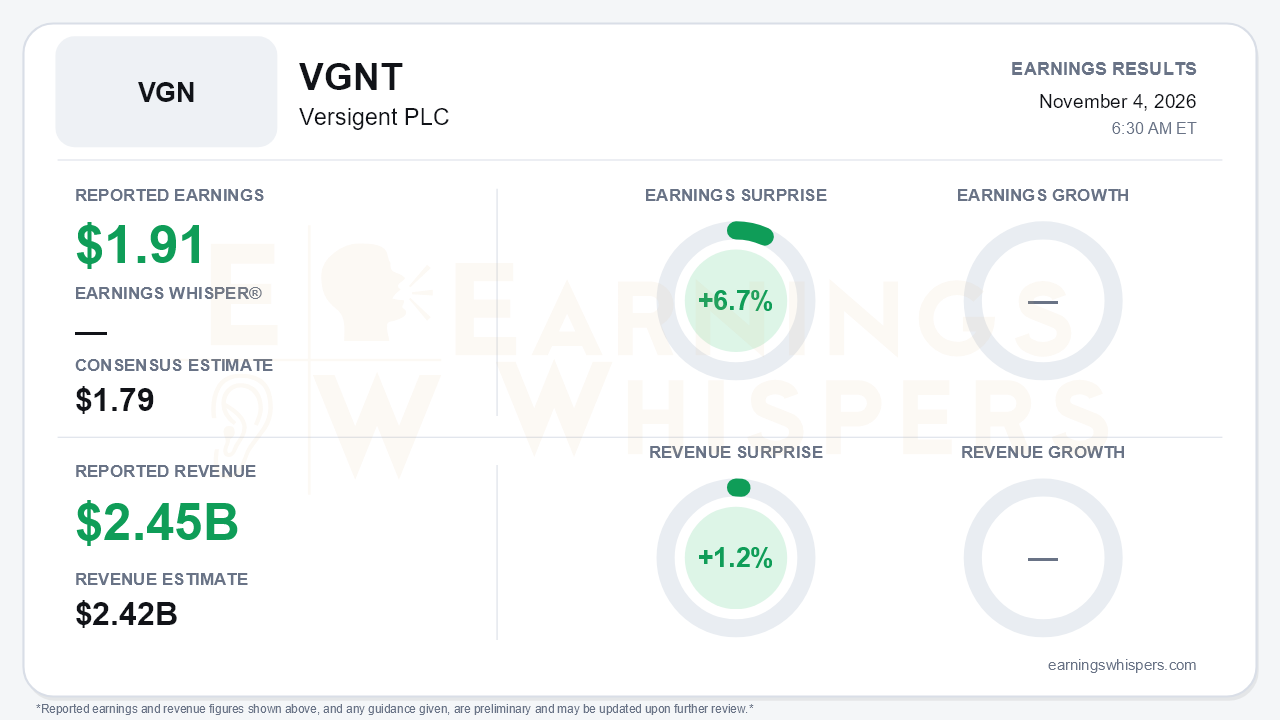
Versigent delivered a clean beat on the headline numbers for its third quarter. Adjusted earnings of $1.91 per share topped the $1.79 consensus by 6.7%, and revenue of $2.45 billion edged past the $2.42 billion estimate by 1.2%. Management also raised the midpoint of its full-year free cash flow guidance and tightened every range. The central tension is beneath that surface. Organic growth decelerated sharply, the revenue guidance lift is almost entirely copper pass-through, and the implied fourth-quarter margin steps down meaningfully. This quarter beat expectations without making the growth story stronger.
The quality of the beat deserves scrutiny. Reported sales rose 7.2%, but roughly five points came from commodity pass-throughs and about one point from currency. That left Adjusted Net Sales Growth at only about 1%, down from roughly 5% in the second quarter and 3% in the first. Adjusted EBITDA rose 10.9% to $275 million, and margin expanded 40 basis points to 11.2%. However, the quarter included about $21 million of net pricing benefit from commercial recoveries tied to prior EV program cancellations. Without those recoveries, much of the margin expansion disappears. On a GAAP basis the picture is softer still. Diluted EPS fell to $1.41 from $1.54, and net income slipped to $102 million from $109 million. The drivers were $36 million of interest expense from the spin-related debt, which did not exist a year ago, and a higher noncontrolling-interest share. Adjusted EPS of $1.91 compares with $1.81 a year earlier, but a lower tax bill helped carry that comparison.
The call reinforced the sense that growth is slowing at the operating level. Americas adjusted growth cooled to 1% from 6% in the second quarter. EMEA remained in decline, with adjusted sales down 8%, which was less severe than the double-digit drops earlier in the year but still negative. Asia Pacific was the bright spot, growing 18% reported and 9% adjusted, with India strengthening. Management pointed to a sixth straight quarter of growth over market, attributing the slowdown to launch ramps and an industry production decline of about 2%. Bookings of $2.1 billion brought the year-to-date total to $7.5 billion, but the figure was below the $2.8 billion and $2.6 billion booked in the two prior quarters. Management was explicit that third-quarter margins are not a run rate. The tightened EBITDA range leaves the $990 million midpoint unchanged and implies a fourth-quarter margin of roughly 9.8%, pressured by elevated launch costs and copper lag. The copper assumption rose to $6.25 per pound, which carries a continuing headwind of about 90 basis points.
The cash flow story is the strongest part of the report, though it is not entirely clean. Third-quarter free cash flow of $170 million was a sharp improvement from $107 million in the second quarter and negative $30 million in the first. Net leverage fell to 1.5x from 1.8x, and the board declared a second $0.13 quarterly dividend. Part of the $50 million guidance raise reflects restructuring spending shifted into 2027, so the cumulative 2026-2028 target of about $1 billion is unchanged. That creates a visible 2027 headwind. The roughly $40 million in EV recoveries will roll off, a full year of interest will be absorbed, and deferred restructuring will come due. Bears also have legitimate ammunition in the risk that EU industrial policy cools China exports into Europe, which account for about 35% of China-made sales. Adjacent markets such as commercial vehicles, agriculture, energy storage and robotics are drawing investment and new wins, but they remain immaterial to revenue. The authorized buyback has also not yet been executed.
The market had already been leaning skeptical. Investor sentiment entered the report mildly negative and drifted modestly lower, to -0.18 from -0.13. Shares closed at $40.69 the day before the release, down 10.7% from the open after the August report. That left the stock about 4% below its 200-day moving average and just 1.5% above its inter-earnings low of $40.11, set October 23. The stock had peaked at $50.25 in early September and given back about 19% since. The AVWAP trend signal remains negative, reflecting that steady erosion.
That setup cuts both ways. A beat and a cash flow raise give near-term support to a stock trading near its lows. However, investors who sold through the autumn were reacting to exactly the issues the call confirmed: decelerating organic growth, margins helped by one-time recoveries, and a softer fourth quarter.
The bottom line is that Versigent executed well on cash generation, deleveraging and launches, and it cleared estimates on both lines. Even so, the underlying trajectory weakened. With adjusted growth near 1%, EBITDA guidance flat at the midpoint, and identifiable 2027 cash flow pressures, the report steadies the near-term picture more than it rebuilds the growth case.
Read our earnings preview for Versigent PLC: https://www.earningswhispers.com/article/VGNT/21756
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-01 | |
| Aug-26 | |
| Aug-14 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Jul-21 | |
| Jul-15 | |
| Jun-03 | |
| May-19 |
