Qnity Delivers A Clean Beat-And-Raise As AI-Driven Volume And Margin Expansion Outrun A Skeptical Tape
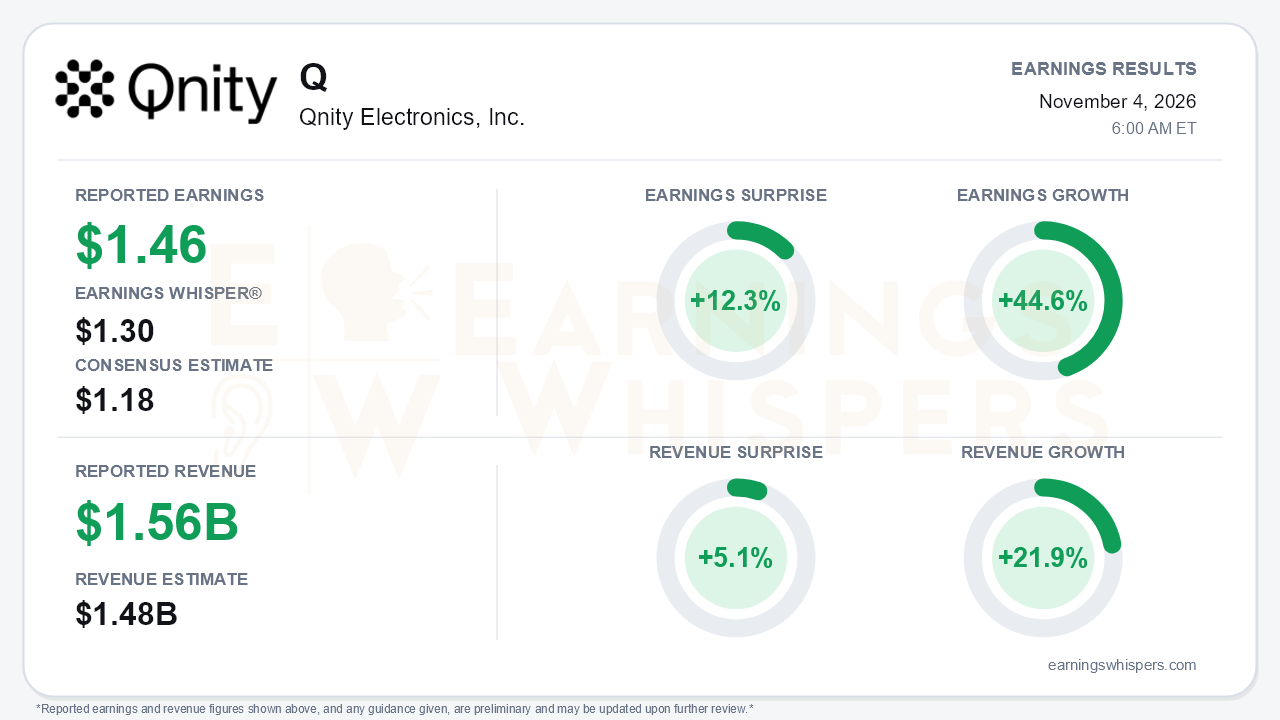
Qnity Electronics turned in the kind of quarter that is hard to argue with on fundamentals. Adjusted EPS of $1.46 beat the $1.18 consensus by 12.3% and topped the $1.30 Earnings Whisper. Revenue of $1.556 billion beat the $1.48 billion consensus by 5.1%. Earnings grew 44.6% year over year and revenue rose 21.9%, and management raised full-year guidance for the third consecutive time. The central tension is not in the numbers. The stock entered the report down 15.7% since the open after the August release, even as the business accelerated through the period.
The quality of the beat holds up well. Organic growth was 22%, and price and mix contributed essentially nothing. This was a volume quarter, with Interconnect Solutions up 29% organically and Semiconductor Technologies up 16%. Gross margin expanded 270 basis points to 47.8%. Adjusted operating EBITDA rose to $503 million at a 32.3% margin, up from 29.0% on a pro forma basis a year ago. Interconnect segment EBITDA jumped from $152 million to $236 million.
The GAAP picture is weaker. GAAP EPS fell 14% to $0.87, and GAAP net margin slid from 17.5% to 12.6%. The drag came from standalone-company costs: $53 million of transformation charges, mostly IT independence; $39 million of indirect legacy costs tied to DuPont cost-sharing; and interest expense that rose to $64 million from $14 million. Investors should also note a growth-rate discrepancy. Qnity's own 55% adjusted EPS growth figure compares against a pro forma $0.94, while the Earnings Whispers growth figure uses a different prior-year base.
Cash conversion is the other soft spot. Operating cash flow fell to $271 million from $302 million as receivables and inventory built alongside the sales surge. Adjusted free cash flow nonetheless rose to $320 million.
The call showed clear acceleration beneath the headline:
- Sales rose 9% sequentially, far ahead of the low-single-digit sequential growth guided in August.
- Adjusted EBITDA growth accelerated to 36% from 24% in the second quarter.
- The second quarter's semiconductor margin dip reversed.
- Thermal, advanced packaging and AI PCB, roughly 30% of Interconnect, are growing more than 50%. The rest of the segment is growing mid-teens.
- Advanced nodes grew 25% and now represent 44% of semiconductor revenue, up from roughly 40% exiting the first half.
- Advanced-logic fab utilization moved into the high-80s.
The guidance trajectory tells the story. Full-year sales guidance has climbed from $4.97-$5.17 billion in February to $5.77-$5.83 billion. Adjusted EPS guidance has gone from $3.55-$3.95 to $4.95-$5.05, and free cash flow guidance from $450-$550 million to $800-$900 million. These are management targets, not results, but they imply roughly 26% fourth-quarter growth. Management also lifted its wafer-start outlook to high-single to low-double digits and signaled a similar range for 2027.
Forward catalysts are substantive:
- 2nm and HBM4 process-of-record wins are now entering production, at a pace expected to exceed 2025's record.
- Management is tracking more than 15 advanced fabs scheduled to start production within about a year.
- Management articulated an explicit path to a 50%-plus gross margin.
- Qnity was added to the SOX index.
- A permanent CFO with semiconductor-industry experience is now in place.
- Net leverage fell to 1.7x from 2.2x at year-end.
Bears still have legitimate ammunition. Analysts pressed on reported data center project delays and pushback on AI capex pacing, which bear directly on the fastest-growing product lines. Low- and mid-end consumer electronics are softening. Fourth-quarter seasonality and year-end inventory management apply, and the first quarter is typically up only low single digits. Capex of $290 million year to date trails a $450-$470 million target even as some projects require accelerated capacity, so execution timing matters.
Investor sentiment improved meaningfully, rising from near-neutral 0.02 to 0.175. That is still only modestly positive. The price action has been far less forgiving. Shares peaked at $146.67 on August 13 and then slid to a $105.01 low on October 23. They entered the report at $118.89, 8.1% below the $129.38 200-day moving average, 13.2% off that low, and nearly 19% below the quarter's high. Earnings Whispers momentum readings are positive, but the AVWAP trend remains negative. That fits a stock whose fundamentals have outpaced its price, consistent with a market more concerned about the durability of AI spending than about Qnity's own execution.
The bottom line is that Qnity delivered a genuine beat-and-raise driven by volume, advanced-node mix and margin expansion, with no metrics cut and guidance moving higher again. The GAAP decline reflects separation costs and leverage rather than operating weakness, though cash conversion merits watching. The open question is whether investors will reward the improving fundamentals while broader AI capex doubts linger and shares remain below their long-term trend.
Read our earnings preview for Qnity Electronics, Inc.: https://www.earningswhispers.com/article/Q/21732
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 8 hours | |
| 8 hours | |
| Nov-03 | |
| Oct-29 | |
| Oct-27 | |
| Oct-21 | |
| Oct-21 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-06 | |
| Oct-05 | |
| Oct-01 |
