Avient Beats And Raises Again As Organic Growth Hits 10.6%, But Pricing Is Still Doing The Heavy Lifting
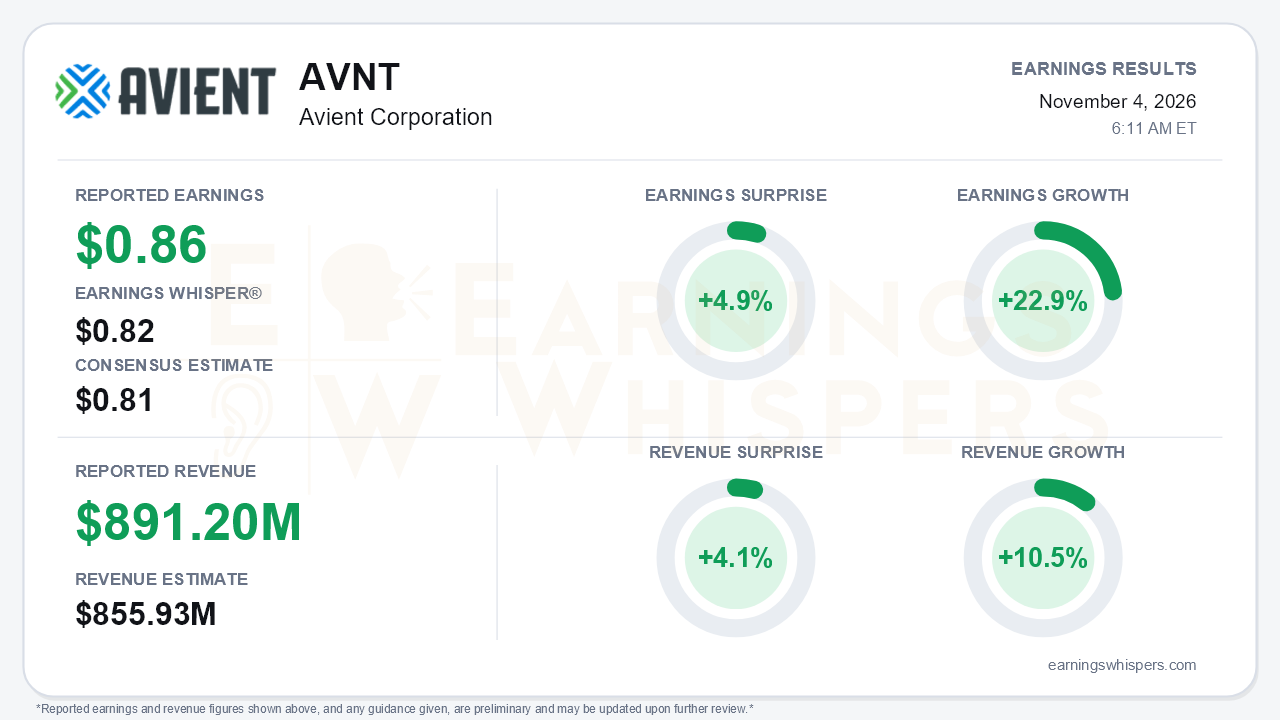
Avient delivered the kind of quarter that forces a rethink of the bearish setup it carried into the report. Adjusted EPS of $0.86 beat the $0.81 consensus by 4.9% and topped the $0.82 Earnings Whisper number. Revenue of $891.2 million beat expectations by 4.1%. Earnings grew 22.9% year over year and sales rose 10.5%. Management raised full-year adjusted EPS guidance for the second straight quarter, to $3.22–$3.32 from $3.10–$3.25. The central tension is what is driving the growth. Organic sales accelerated sharply, to 10.6% from 4.3% in Q2, 1.2% in the first half and -0.8% in Q4 2025. Yet total volume grew only about 1%, so the acceleration rests almost entirely on price and mix.
The margin story is the strongest part of the release. Adjusted gross margin widened to 33.2% from 32.2%. Adjusted operating margin rose to 12.2% from 10.7%. Adjusted EBITDA margin expanded 80 basis points to 17.3%, a third-quarter record. Both segments contributed:
- Specialty Engineered Materials grew 15% organically, with margin up 140 basis points.
- Color, Additives and Inks grew 8%, with margin up 120 basis points.
GAAP EPS improved more modestly, to $0.46 from $0.36. Special items rose to $0.23 a share from $0.17, led by $19.1 million of environmental remediation costs and higher restructuring charges. Those costs relate to legacy sites, but they are recurring often enough to warrant attention.
Cash flow was solid. Nine-month operating cash flow reached $180 million versus $133.8 million a year ago, despite an $80.5 million inventory build and $92.8 million of receivables growth. Leverage is now guided to 2.2–2.3x by year-end, down from 2.66x at the end of 2025.
Beneath the headline, the call showed both breadth and gaps. Asia grew 20% after 18% in Q2, helped by high-performance computing and electronics wins. Healthcare in SEM returned to double-digit growth after first-half inventory rebalancing. Defense, consumer, telecom and building & construction also grew double digits. The weak spots were clear, however:
- EMEA remained muted in consumer, industrial and transportation, pushing CAI volume down about 1%.
- Transportation was flat on soft global auto builds.
- Volume fell short of management's Q2-call framing, which expected volume to account for roughly 70% of growth by Q4, including mid-single-digit U.S. volume gains.
Pricing is currently offsetting mid-single-digit raw material inflation, and that net benefit may normalize. Bears have legitimate ammunition here. A pricing-led recovery is less durable than a volume-led one.
The guidance details reinforce that nuance. The EPS range moved up meaningfully. Adjusted EBITDA guidance, however, was narrowed to $593–$603 million by raising only the low end, leaving the top unchanged despite the Q3 beat. Measured against year-to-date results, the outlook implies a fourth quarter only modestly ahead of last year's. Capex has been trimmed to about $120 million from $140 million originally, which management attributed to project timing. A $30–$35 million variable compensation headwind is also inflating corporate expense.
The forward story now belongs to new CEO Mike Frank, three weeks into the job. He explicitly framed his role as growth acceleration, not a turnaround. Frank deferred 2027 targets to February and launched a review of the manufacturing footprint, procurement and portfolio. He said near-term M&A is unlikely. That review could bring restructuring charges, which would add to an already elevated special-items line. Capital allocation also shifted: Avient repurchased roughly $10.9 million of stock after quarter end, its first buyback since 2022, and plans to balance further debt reduction with opportunistic repurchases.
Investor sentiment improved meaningfully into the report, rising to -0.215 from -0.4675, though it remains negative. Investors are warming to the story without embracing it. Shares closed at $43.25 before the release, up 8.1% from the opening price after the August report. That leaves the stock about 12.2% above its 200-day moving average. Shares sit 7.3% below the $46.64 52-week high set on August 11 and 18.2% above the October 9 low of $36.60. In other words, the stock had already rebounded sharply off its fall low but had not reclaimed its post-Q2 peak. Supporting trend readings for momentum and AVWAP are positive, while price trend is neutral.
The bottom line is that Avient produced a credible beat-and-raise quarter. Organic growth accelerated, margins expanded and the balance sheet strengthened enough to restart buybacks. The quality question is volume. Until EMEA and transportation stabilize and units, rather than pricing, carry growth, the improvement remains narrower than the headline suggests. A leadership transition and a pending footprint review add uncertainty heading into February's 2027 outlook.
Read our earnings preview for Avient Corporation: https://www.earningswhispers.com/article/AVNT/21674
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-14 | |
| Oct-09 | |
| Oct-09 | |
| Oct-09 | |
| Oct-06 | |
| Oct-01 | |
| Sep-11 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-16 |
