Bruker's Margin-Led Beat Outruns A Flat Top Line As Bookings Recovery Broadens
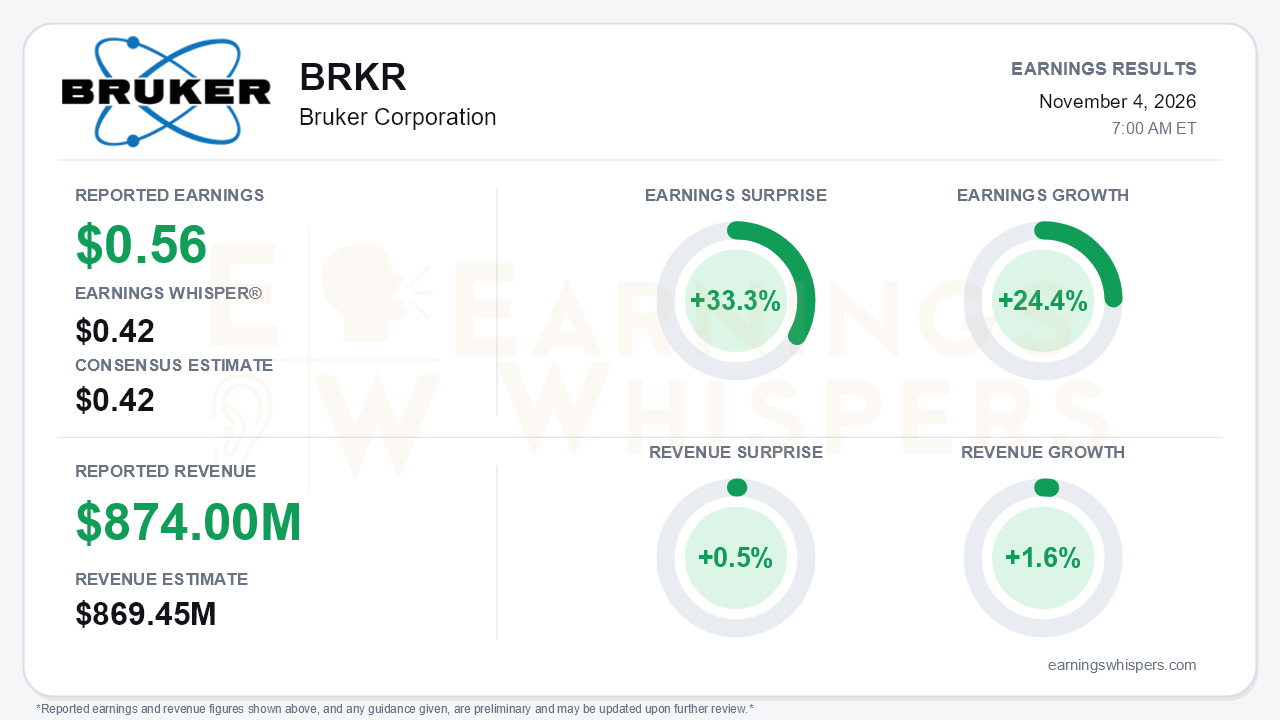
Bruker (NASDAQ: BRKR) delivered a quarter driven by cost discipline rather than growth. Third-quarter non-GAAP EPS of $0.56 beat the $0.42 consensus and Earnings Whisper number by 33.3% and rose 24.4% from a year ago. Revenue of $874.0 million topped the $869.45 million consensus by only 0.5% and grew just 1.6%, or 0.7% organically. That is the central tension. Bruker is now converting a stagnant top line into sharply higher earnings, and the order book suggests revenue is about to catch up. But the reported numbers still show a company that is not yet growing.
The margin story is real. Non-GAAP operating margin reached 16.3%, up 400 basis points year over year, compared with 14.1% in the second quarter and 10.2% in the first. The second-quarter figure was flattered by roughly 200 basis points of tariff refunds. Management said the quarter came in "meaningfully ahead" of internal expectations, even though it had guided third-quarter margins slightly lower sequentially. Non-GAAP gross margin improved 120 basis points to 51.3%, with mix contributing about 90 basis points. GAAP SG&A and R&D both declined as the $140 million cost-out program took hold. Earnings growth also accelerated: nine-month non-GAAP EPS rose from $1.23 to $1.36, a much slower pace than the third quarter's 24.4%. Free cash flow swung to $96.7 million from negative $54.1 million a year earlier, and net leverage fell to 2.4x from 3.1x at the end of 2025.
The quality of the beat still deserves scrutiny on the GAAP side. Bruker posted a GAAP loss of $0.81 per share, wider than last year's $0.41 loss. The main cause was a $174.5 million goodwill impairment at Bruker Spatial Biology, which followed a roughly $135 million write-down in the second quarter. Two consecutive impairments in one unit are an admission that past acquisition assumptions are not holding. Organic revenue in the core Bruker Scientific Instruments (BSI) segment slipped 0.4%. Semiconductor revenue fell by double digits on a flagged $20 million push-out into the fourth quarter. Asia-Pacific revenue declined to $247.7 million from $252.5 million. The 11.8% organic growth at BEST supplied most of the consolidated organic gain.
Demand is where the narrative turned more constructive. US academic and government bookings grew by double digits, the first year-over-year increase since the 2025 NIH disruption, after being described as still weak in the second quarter. Management expects further growth in the fourth quarter, plus a budget-flush benefit. China BSI bookings are up more than 20% year to date, and China revenue rose by low double digits after falling more than 20% in the first quarter. Semiconductor metrology bookings are up more than 30%. BSI book-to-bill exceeded 1 for a fifth straight quarter, and year-to-date bookings and backlog are both up mid-single digits. Bears have legitimate ammunition, though:
- BSI bookings growth slowed to low single digits from about 10% in the second quarter, which management attributed to a tough comparison.
- European pharma orders softened.
- Academic demand in Japan and Europe weakened.
Guidance was steady rather than raised. Bruker reaffirmed 1% to 2% organic growth and non-GAAP EPS of $2.10 to $2.15. It trimmed reported revenue guidance for a third time on currency, to $3.52-$3.56 billion, and raised its tax-rate assumption to 27.5%. Holding the EPS range after a $0.14 beat implies fourth-quarter EPS of roughly $0.74 to $0.79. That quarter depends on a roughly $1 billion revenue ramp that management says is now almost entirely covered by backlog, compared with about two-thirds at the prior call. About $20 million of site-readiness risk remains. Early fiscal 2027 framing calls for double-digit EPS growth, more than 100 basis points of margin expansion and at least lower-mid-single-digit organic growth. Management nonetheless called 2027 a transition year, with above-market growth more of a 2028 story. Other forward catalysts include:
- the majority acquisition of Mimetas;
- the Atinary AI-lab collaboration;
- an expected FDA clearance for Wave AST.
Investor sentiment improved from slightly negative (-0.07) to modestly positive (0.10) heading into the report, a meaningful shift but not euphoria. Shares closed at $56.50 before the release, up 4.5% from the open after the August report and 12.4% above the 200-day moving average. The path was volatile. The stock fell to $48.63 the day after the last report, then rallied to a 52-week high of $66.98 on September 30. It entered this report 15.6% below that peak, having surrendered much of the rally. The Earnings Whispers trend signals are mostly favorable on sequential growth and momentum, while AVWAP remains negative, consistent with that pullback.
The bottom line is that Bruker has shown it can manufacture earnings growth from a flat revenue base, and the bookings recovery in US academia, China and semiconductors gives the 2027 acceleration thesis credibility. Repeated spatial biology impairments, a guidance range that absorbed rather than passed through the beat, and management's own "transition year" label argue that investors will need visible organic growth, not just margin gains, to reclaim the September highs.
Read our earnings preview for Bruker Corporation: https://www.earningswhispers.com/article/BRKR/21681
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-20 | |
| Oct-06 | |
| Sep-28 | |
| Sep-21 | |
| Sep-08 | |
| Sep-04 | |
| Aug-11 | |
| Aug-10 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 |
