AudioCodes Delivers Its Fastest Revenue Growth Of The Year, But Slowing ARR, Thinner Margins And Shrinking Cash Undercut The Story
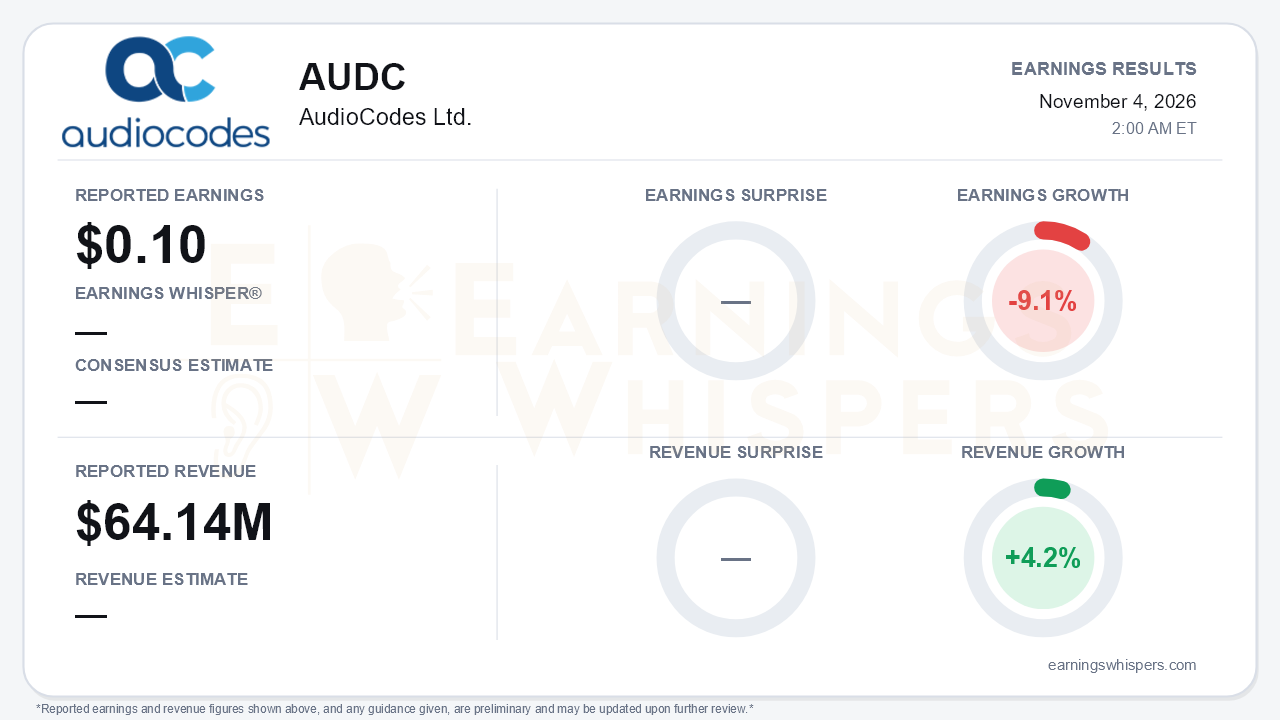
AudioCodes (NASDAQ: AUDC) posted its best top-line growth of 2026, yet the quarter's more important signals point the other way. Revenue rose 4.2% year over year to $64.14 million, the fourth straight quarter of acceleration from 1.7% in the fourth quarter of 2025, 2.9% in Q1 and 3.1% in Q2. On Earnings Whispers' normalized basis, earnings were $0.10 per share, down 9.1% from a year ago. The company's own figures tell a different story: GAAP EPS of $0.15 versus $0.10 and non-GAAP EPS of $0.16 versus $0.17. No consensus or Whisper figure was available, so the quarter has to be judged on its trends rather than a surprise. Those trends are the central tension: revenue is speeding up while the leading indicators of future growth are slowing.
The quality of the earnings deserves scrutiny. The GAAP improvement relied heavily below the operating line. Financial income jumped to $1.2 million from $64,000, largely from exchange-rate revaluation gains, and the tax bill fell. GAAP operating income actually declined to $3.4 million from $4.1 million, and operating margin narrowed to 5.3% from 6.6%. On a non-GAAP basis, which strips out those currency effects, operating margin fell to 7.4% from 9.5% and net income slid to $4.0 million from $4.9 million. Per-share results held up better than profits only because buybacks cut the diluted share count to roughly 24.5 million from 28.7 million. The mix shift is real: services revenue climbed 19.9% to $37.1 million, or 57.8% of sales, while product revenue fell to $27.0 million from $30.6 million. Gross margin was flat at 65.8% on a non-GAAP basis, however. The margin damage came from selling and marketing, which rose to $21.2 million from $18.9 million as the company funds its Live and VoiceAI push.
The call preserved a credible transformation narrative, but the growth language softened. Combined ARR for Live and VoiceAI reached $87 million, up from $84 million in Q2 and $80 million in Q1. ARR growth, however, decelerated to 16% from 20% in Q2 and about 22% in Q4. Microsoft Teams growth eased to 4% from 5% and 6% earlier in the year. New Microsoft opportunities rose 9.4% versus 14% previously, and TCV growth slowed to 61% from 73%, even as Teams TCV bookings topped $20 million for a second straight record quarter. VoiceAI messaging also stepped down. Management cited 50% growth for the first nine months, after framing it as "over 50%" in Q2, and VoiceAI Connect and Live Hub invoicing grew about 40%. The SBC line, tracking toward a record of more than $135 million, and roughly $50 million in stable gateway sales give the legacy connectivity base, now more than 85% of the business, a solid floor.
The catalyst list is genuinely encouraging:
- Deutsche Telekom publicly selected VoiceAI Connect, alongside Mistral AI, for its Mobile AI Notes service.
- A large North American network operator signed a multi-million-dollar, 24-month contract.
- A new APAC customer lifted Live platform ARR above $5.5 million.
- A major German insurer chose Voca CIC, extending a run of financial-institution wins, and a Fortune 500 win came through AT&T.
- MiaEdge added 11 customers.
Management reiterated full-year guidance of $251-256 million in revenue, a range raised last quarter, and non-GAAP EPS of $0.60-0.75. Against a year-to-date non-GAAP EPS of $0.44, that EPS range leaves a wide fourth-quarter spread. Bears have legitimate ammunition in the balance sheet and cash flow. Operating cash flow fell to $4.1 million from $6.1 million in Q2 and $12.8 million in Q1. DSO stretched to 109 days, and the backlog figure was not updated. Cash and investments dropped to $47.1 million from $64.2 million at midyear and $75.7 million at year-end. That decline followed $15.1 million in Q3 buybacks plus a $4.8 million dividend, roughly five times quarterly operating cash flow. A new $30 million court approval, with $26.7 million remaining, keeps returns flowing, but at this pace capital return is drawing down the cash cushion rather than being funded by operations.
Market context is limited. Shares opened at $9.67 after the August report, modestly above a 200-day moving average now at $9.33. That suggests the stock has been trading in a narrow band around its longer-term trend rather than pricing in either a breakout or a breakdown. No current sentiment reading was available.
The bottom line is that AudioCodes is executing on its shift toward recurring services, with accelerating revenue and notable VoiceAI wins. Underneath, decelerating ARR, Microsoft and VoiceAI growth, compressed operating margins and dwindling cash make this a lower-quality quarter than the headline suggests. Per-share support from buybacks cannot run indefinitely on a $47 million balance. The next test is whether record bookings convert into reaccelerating ARR and better cash generation.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-20 | |
| Oct-19 | |
| Aug-17 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Jul-06 | |
| May-05 | |
| May-05 | |
| Apr-06 | |
| Mar-30 | |
| Feb-03 |
