ATS Misses As Tariff Delays Force Guidance Retreat, Even As Life Sciences Backlog Hits A Record
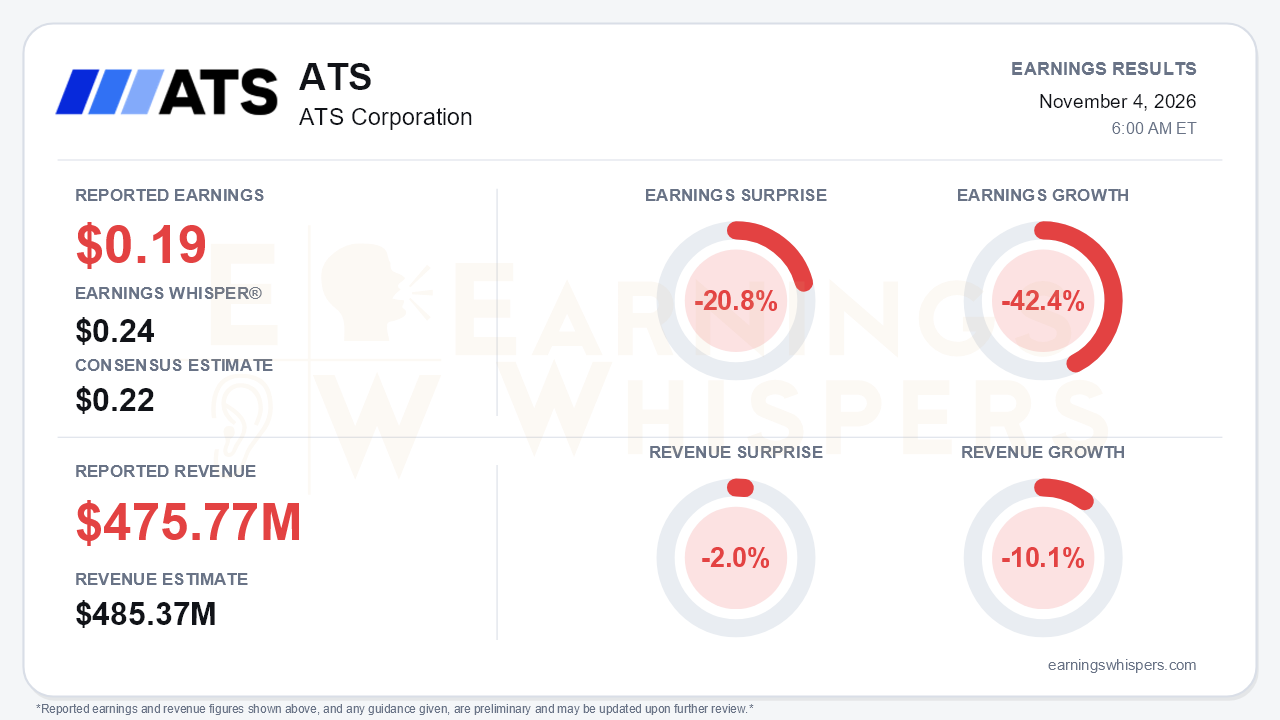
ATS Corporation delivered a quarter that pulled in two directions. Earnings Whispers recorded fiscal second-quarter earnings of $0.19 per share, short of the $0.22 consensus and well below the $0.24 Whisper number, a 20.8% miss. Revenue of $475.77 million trailed the $485.37 million consensus by 2.0%. Earnings fell 42.4% year over year and revenue declined 10.1%. ATS reports in Canadian dollars, and its release shows adjusted basic EPS of C$0.27 versus C$0.45 a year ago on revenue of C$665.8 million, so the two sets of figures reflect currency basis rather than a factual conflict. The more consequential news was not the miss itself. Management abandoned its fiscal 2027 targets for modest revenue growth and 50-75 basis points of margin expansion, while orders improved meaningfully at the same time. That is the central tension: demand indicators are turning up just as reported results and the near-term outlook move down.
The deterioration beneath the headline is real and accelerating. Organic revenue fell 9.1% in the quarter, compared with a 7.7% decline for the first half, which means the first quarter was considerably milder. Adjusted EPS slipped from C$0.40 to C$0.35 in the first quarter but dropped from C$0.45 to C$0.27 in the second. Construction-contract revenue fell 19.2% on lower opening backlog. Industrial & consumer fell 23.5% and food & beverage fell 20.2%, while life sciences slipped 5.0% as GLP-1 activity normalized. Energy was the lone bright spot, up 45.1% on nuclear project execution. Adjusted earnings-from-operations margin compressed to 8.6% from 10.9% a year ago and from roughly 10.3% in the fourth quarter of fiscal 2026. On an IFRS basis, ATS swung to a C$5.0 million net loss from C$33.6 million of profit, burdened by C$21.3 million of restructuring charges. Cash flow was the quality offset. Operating cash flow reached C$80.7 million versus C$28.5 million, and free cash flow was C$62.5 million versus C$10.2 million.
The call preserved a credible demand story. Order bookings rose 12.7% year over year and 26.1% sequentially to C$827 million, a sharp reversal from the 18% decline in the fourth quarter of fiscal 2026. Life sciences produced its second-best bookings quarter on record, with a large radiopharma award and medical device follow-on orders after devices lagged in earlier quarters. Life sciences backlog reached a record C$1.24 billion, and trailing book-to-bill improved to 1.05 from 0.99. Management also noted that life sciences revenue excluding GLP-1 grew year over year. The catch is timing. These life sciences programs are longer-dated, so conversion lags by a quarter or two. Meanwhile, industrial & consumer backlog shrank to C$312 million from C$431 million, and total backlog remains 2.9% below last year.
Tariffs are both the main near-term risk and the main potential catalyst. Section 338 tariffs, effective in late August, froze packaging equipment orders more severely than management anticipated. The late-October U.S. modification removes the impact on most covered products, but management cautioned that relief may not translate immediately into bookings. Third-quarter revenue guidance of C$640-680 million sits well below the C$700-740 million guided for the first quarter. Management also flagged margin pressure from mix and absorption over the next several months. The Fixed Cost Transformation Program is now quantified at C$65-75 million of annualized savings, roughly 250 basis points, but lower volumes are temporarily masking those benefits. A 300-400 person workforce reduction is under way. Leverage climbed to 3.1x from 2.8x and is expected to remain above the 2-3x target range, even as ATS spent C$61.3 million on buybacks. The C$71.2 million facility sale, which carries an estimated C$12.2 million gain and will be recognized next quarter, helps fund restructuring.
The market had already priced in much of this disappointment. Shares fell 22.8% from the open after the August report to $18.96 ahead of this release. They hit a 52-week low of $17.15 in mid-October and sit about 28.5% below the 200-day moving average. Investor sentiment moved from mildly positive (0.05) to mildly negative (-0.09), a measurable but not dramatic shift. The Earnings Whispers price and AVWAP trends remain negative.
The bottom line is that ATS traded near-term credibility for a longer-dated recovery narrative. Bears have legitimate ammunition: withdrawn guidance, sub-9% margins, rising leverage and a soft third-quarter outlook. Still, record life sciences backlog, rebounding bookings, strong cash generation and easing tariff pressure give the turnaround case something concrete to build on. The next two quarters must show that orders are converting into revenue before margins can rebuild toward the 15% long-term target.
Read our earnings preview for ATS Corporation: https://www.earningswhispers.com/article/ATS/21672
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-21 | |
| Aug-11 | |
| Aug-08 | |
| Aug-06 | |
| Jul-23 | |
| Jun-08 | |
| May-28 | |
| May-28 | |
| May-24 | |
| May-14 | |
| Mar-10 | |
| Mar-10 |
