Kyndryl Beats On Margins And Signings, But A Back-Loaded Cash Year And Quietly Shelved FY28 Targets Temper The Quarter
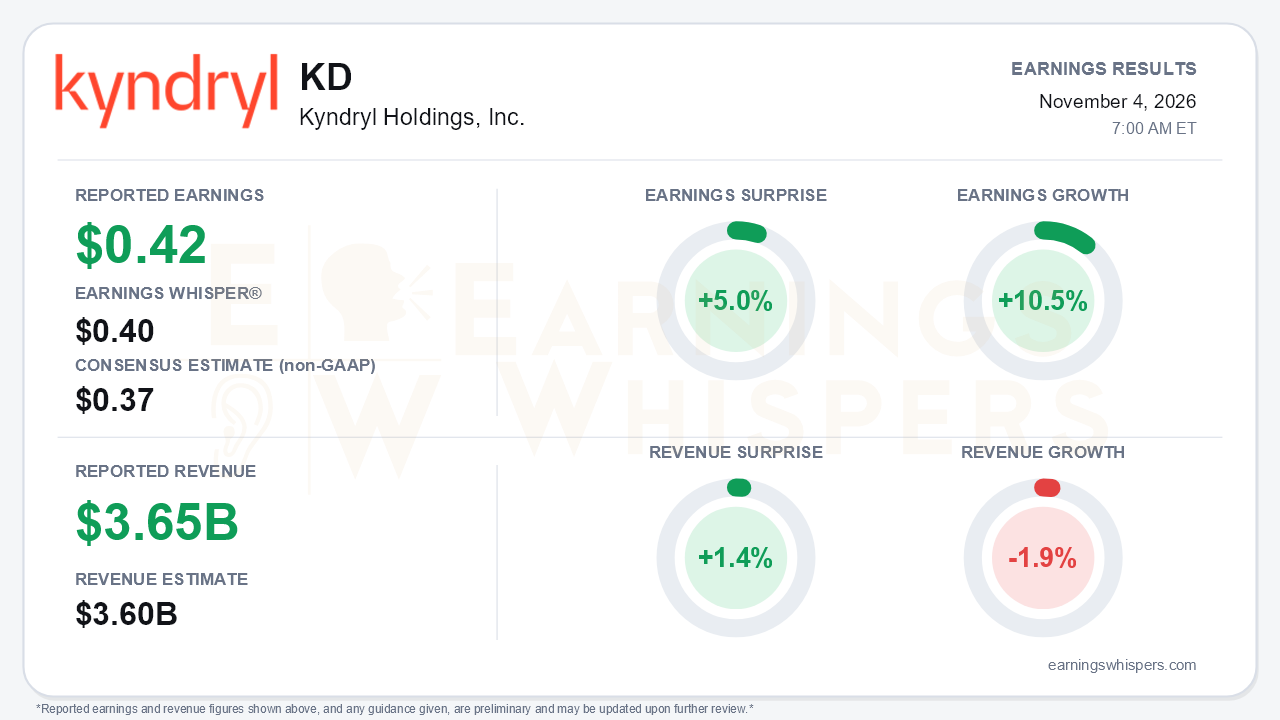
Kyndryl (NYSE: KD) delivered a clean headline beat for its fiscal second quarter. Adjusted earnings came in at $0.42 per share, ahead of the $0.37 consensus and the $0.40 Earnings Whisper number. That is a 5.0% surprise and 10.5% year-over-year growth. Revenue of $3.651 billion topped the $3.60 billion estimate by 1.4%, though it still fell 1.9% from a year ago. Management reaffirmed every fiscal 2027 target, and that outlook sits above Street estimates. Kyndryl's margins and bookings are clearly improving, but the cash and long-term-target picture got murkier. That is the central tension.
The quality of the EPS beat deserves scrutiny. Adjusted net income rose only modestly, to $92 million from $89 million. Much of the per-share growth came from a diluted share count that shrank to 219.1 million from 235.9 million. On a GAAP basis, diluted EPS slipped to $0.27 from $0.29, weighed by $38 million of workforce rebalancing charges and a higher tax provision. The operating improvement is real:
- **Adjusted EBITDA margin** expanded 190 basis points to 19.1%.
- **Adjusted pretax income** climbed to $150 million from $123 million.
Two caveats apply. First, a one-time commercial matter resolution added about 3 points to U.S. revenue growth and 15 points to U.S. EBITDA growth, although the company says the benefit was mitigated at the total-company level. Second, rising amortization of transition costs flatters EBITDA relative to pretax income.
The top-line trajectory is modestly better. Constant-currency revenue declined 0.8%, an improvement on Q1's roughly 3% drop. The U.S. grew 9% for a third straight growth quarter, and hyperscaler-related revenue surged 27.2% to more than $550 million. Bookings were the standout. Q2 signings jumped to $4.1 billion from $2.8 billion a year earlier, and trailing-twelve-month signings rose to $15.5 billion from $14.2 billion last quarter. Kyndryl also signed 11 contracts above $50 million in the quarter, and roughly a third of signings now come from new scope or new logos. Beneath that strength, however, several metrics softened:
- **Kyndryl Consult** growth slowed to 6% in constant currency from 11% in Q1. Management called Q2 the low point and held to high-single to low-double-digit growth for the year.
- **Projected gross margin on signings** slipped to 25% from the 26% cited in prior quarters.
- **Focus-account profits**, a tailwind in recent periods, are now largely exhausted.
The forward catalysts are tangible. Kyndryl closed the Healthcare IT Leaders acquisition, which will contribute second-half revenue. Next week it plans to launch a co-developed ServiceNow offering with a better margin profile and a sovereignty solution aimed at European deal delays. It has also expanded its Broadcom/VMware consulting relationship. Management's tone on Europe shifted from describing delays to saying signings and revenue are "starting to come back." Workforce rebalancing is essentially done, with about $200 million of second-half savings and a reiterated $400 to $500 million annualized run rate in fiscal 2028.
Bears still have legitimate ammunition:
- **Cash flow.** Free cash flow was a $34 million outflow in Q2 and a $434 million use in the first half. Hitting the $400 to $500 million full-year target therefore requires a heavy second-half back-end load.
- **Balance sheet.** Cash fell to $1.7 billion from $2.6 billion. Refinancing 2.05% notes with paper yielding roughly 7.8% to 7.9% pushes interest expense toward about $160 million.
- **Long-term targets.** The fiscal 2028 targets of $1.2 billion in pretax income and $1 billion in free cash flow disappeared from the release and deck. Management said verbally they remain on track, but the earlier fiscal 2028 revenue framework had already slipped from mid-single-digit to low-single-digit growth.
- **Near-term headwinds.** Management flagged a difficult Q3 revenue comparison, and this was the new CFO's first call.
Investors entered the report deeply skeptical. Earnings Whispers sentiment edged to -0.6756 from -0.6561, essentially unchanged but still firmly negative. Shares closed at $12.94 ahead of the release, down 9.5% from the open after the August report and about 3.8% below the 200-day moving average of $13.45. The inter-earnings range was volatile. The stock fell to a $10.96 low on September 29, rallied to $15.23 by October 22, then gave back about 15% of that peak into the print. Kyndryl's internal trend readings are mixed: AVWAP is positive, while sequential growth remains negative.
The bottom line is that Kyndryl produced a credible "reaffirm and execute" quarter. Margins expanded, revenue declines narrowed, and bookings strengthened in a way that supports the turnaround narrative. The beat leaned on buybacks and some one-time help, though. Consult momentum cooled, and the whole fiscal 2027 cash story now rests on the second half. Dropping explicit fiscal 2028 targets from the materials will not reassure an already pessimistic shareholder base. Until free cash flow shows up, the improving operating story is likely to keep competing with balance-sheet and credibility concerns.
Read our earnings preview for Kyndryl Holdings, Inc.: https://www.earningswhispers.com/article/KD/21710
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 12 hours | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-20 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-06 | |
| Oct-01 | |
| Oct-01 | |
| Sep-29 | |
| Sep-16 | |
| Sep-16 |
