Harmony Biosciences Misses As Royalty Costs Squeeze Margins And WAKIX Growth Cools, With February Patent Rulings Looming
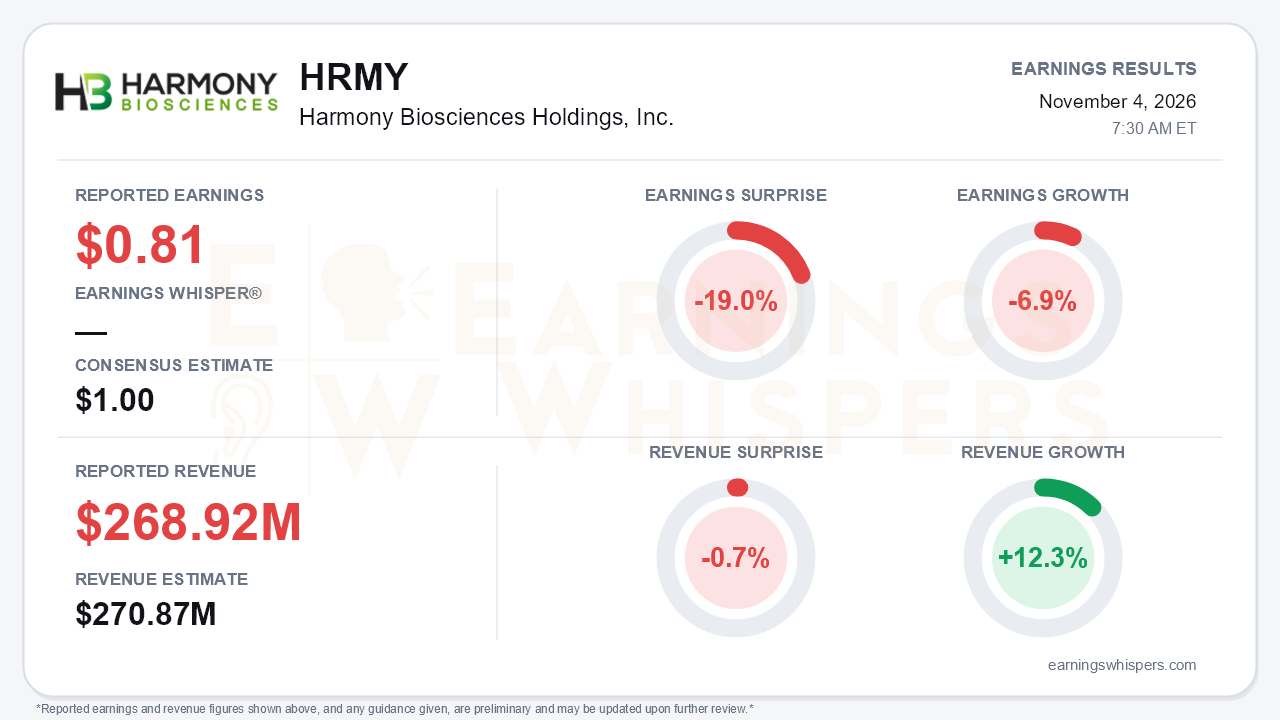
Harmony Biosciences delivered a third-quarter miss that was driven by costs rather than demand. Earnings of $0.81 per share fell 19.0% short of the $1.00 consensus and declined 6.9% from a year ago. Revenue of $268.92 million came in 0.7% below expectations while still growing 12.3% year over year. The central tension is that WAKIX remains a durable, growing franchise, but each incremental dollar is now worth less. Top-line growth is also decelerating sharply, from roughly 30% in the second quarter, according to call commentary, to the low teens. That combination is uncomfortable for a company whose valuation case leans on WAKIX funding the pipeline through 2030.
The quality of the miss deserves scrutiny because only part of it is transitory. A $25.0 million milestone tied to the MSN license pushed R&D to $71.7 million and total operating expenses to $134.0 million. That one-time charge accounts for a meaningful share of the shortfall. The more durable problem sits higher on the income statement. Cost of product sold climbed to 30% of revenue, up from 25% a year ago, 24.2% in the second quarter and 20.7% in the first. The release attributes this primarily to new royalties under the Novitium license, and management signaled on the call that roughly 30% is the go-forward run rate. Gross profit rose only about $8 million on nearly $30 million of added revenue, and operating income fell to $54.2 million from $65.5 million. A lower tax bill cushioned the net income decline. Net income was $48.2 million, down sharply from $75.4 million in the second quarter.
Demand held up, but the trajectory flattened. Average patients rose by 400 to about 9,350, extending a streak of five 400-plus quarters out of the last six. That was still a step down from roughly 450 adds in the second quarter. The slowdown came even though the expanded field sales, remote sales and reimbursement teams were fully deployed by the second quarter. Management reiterated full-year WAKIX guidance of $1.0 billion to $1.04 billion for the fourth consecutive call. With $745.6 million booked through nine months, that range implies fourth-quarter revenue of roughly $254 million to $294 million. The low end would be below the third quarter's result, so reiterating the range offers little evidence of upside. Competitive pressure is also arriving: Takeda's orexin agonist oveporexton is expected to launch in narcolepsy type 1 this month.
The pipeline update was constructive but not spotless. Preliminary multiple-ascending dose data for BP-205 supported once-daily dosing, showing a roughly 29-hour effective half-life and about 60-minute Tmax. The study recorded no serious or severe adverse events and no liver, visual or clinically significant cardiovascular signals, which are the safety issues that have dogged the orexin class. However, on-target insomnia appeared in under 20% of participants at all doses, and urinary frequency and urgency appeared in under 20% at the 1 mg and 3 mg doses. Headache reached about 25%. The single-ascending dose study had shown none of the on-target events and headache of about 10%. All of these events were mild, but the cleaner single-dose profile has become more nuanced. The next proof point is Phase 1b data in sleep-deprived volunteers in the first quarter of 2027.
The bigger near-term catalyst is legal. A ruling in the AET ANDA litigation is expected around the February 2027 expiration of the 30-month stay. The judge adopted Harmony's proposed preliminary injunction schedule, with a January 26 hearing and a decision by February 14, built around a newer amorphous-form patent running to 2042. Management frames this as one layer of a multi-layered IP strategy and maintains confidence in exclusivity to March 2030. Analysts, however, pressed on whether the injunction request is a hedge against an adverse bench ruling, and bears have legitimate ammunition there. The amorphous patent trial itself is not expected until around 2029. The CEO handoff to Peter Anastasiou on January 1, with the CFO role still interim, adds execution uncertainty just as these events converge. Offsetting that, cash and investments exceeded $1.05 billion, and management broadened its business development focus toward larger CNS markets.
Investor sentiment entered the report mildly negative and essentially unchanged from the prior quarter, edging from -0.29 to -0.27. Shares, at $37.02 heading into the release, were nearly flat from the $37.10 open after the August report. That flat result masks a round trip: the stock reached a 52-week high of $43.49 in early September, then slid to $34.11 in late October. It now sits about 15% below that peak and about 7% above its 200-day moving average. The Earnings Whispers trend readings are mixed, with sequential growth and momentum positive while AVWAP remains negative.
The bottom line is that Harmony's miss was partly one-time, but the margin reset is not. A franchise growing in the low teens with a structurally higher royalty burden is a different earnings story than the one investors priced earlier this year. February's patent rulings, rather than quarterly revenue, will likely dictate the stock's direction from here.
Read our earnings preview for Harmony Biosciences Holdings, Inc.: https://www.earningswhispers.com/article/HRMY/21708
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 7 hours | |
| Oct-27 | |
| Oct-22 | |
| Oct-20 | |
| Oct-12 |
Harmony Bio CEO Plans His Exit, And Shares Take An Unharmonious Hit
HRMY -5.09%
Investor's Business Daily
|
| Oct-12 | |
| Oct-01 | |
| Sep-03 | |
| Aug-27 | |
| Aug-26 | |
| Aug-06 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 |
