GXO Logistics Narrowly Beats As Commercial Momentum Accelerates, But Flat EBITDA And A Reaffirmed Outlook Leave Margins As The Open Question
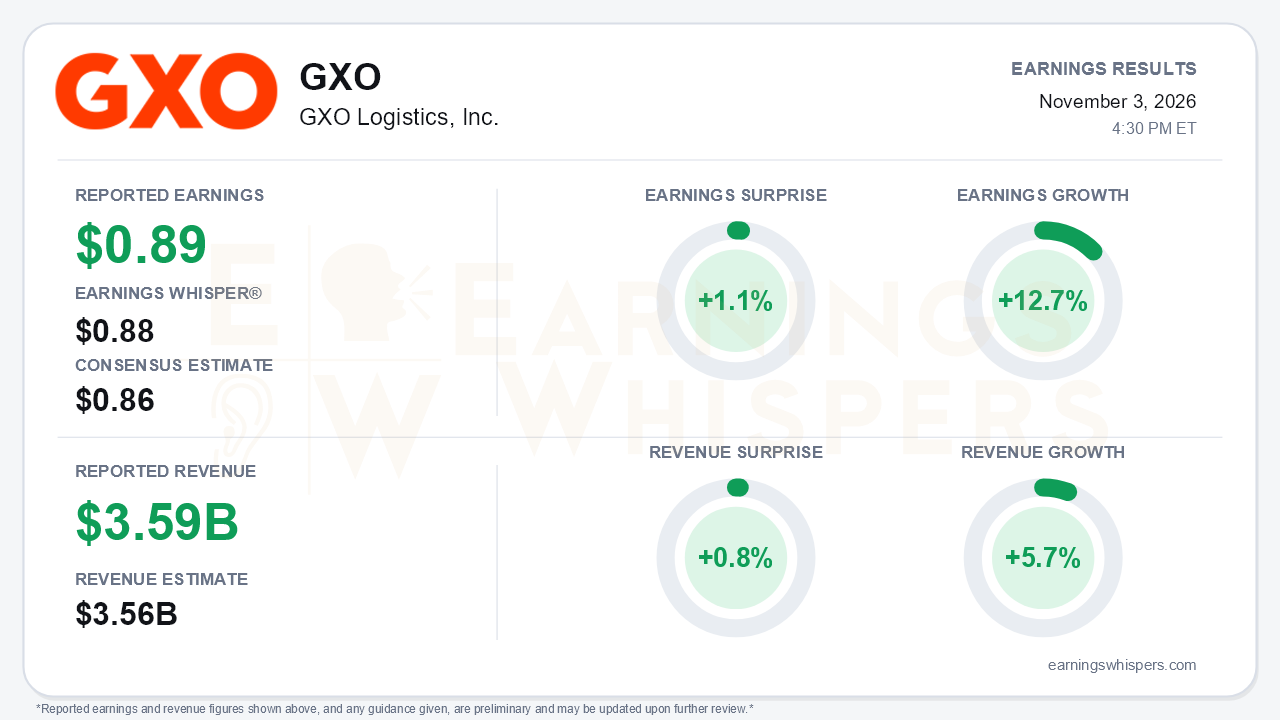
GXO Logistics delivered a modest beat that matters more for what it says about the order book than for the earnings line. Adjusted EPS of $0.89 topped the $0.86 consensus by 1.1% and edged past the $0.88 Earnings Whisper number. Revenue of $3.59 billion beat by 0.8%. Earnings grew 12.7% year over year and revenue rose 5.7%, while organic growth of 6.4% was the fastest in more than three years. The central tension is that GXO is clearly winning more business, but none of that momentum has yet reached operating profit, and management chose to reaffirm full-year guidance rather than raise it.
The quality of the beat deserves scrutiny. Adjusted EBITDA was exactly flat at $251 million despite the 5.7% revenue gain, so adjusted EBITDA margin slipped to 7.0% from 7.4%. Adjusted EBITA was essentially unchanged at $163 million versus $164 million. The 13% rise in adjusted EPS therefore came largely from below the operating line: other income rose to $12 million from $5 million, the tax burden was lighter, and the share count fell slightly. On a GAAP basis, operating income dropped to $96 million from $118 million, and operating margin narrowed to 2.7% from 3.5% as transaction and integration costs nearly doubled to $26 million. GAAP diluted EPS still improved to $0.56 from $0.51, but mainly because income tax expense fell to $7 million from $28 million. Cash flow was also softer. Free cash flow fell to $85 million from $187 million. Management attributed part of the decline to ERP timing and higher capex. The reported figures, however, show third-quarter capex fell year over year to $74 million from $144 million. The bigger drivers were lower operating cash flow and the absence of the $99 million in asset-sale proceeds that flattered last year's quarter.
The commercial story is where the quarter turned decisively better. Organic growth reaccelerated sharply, from 4.1% in Q1 and 3.4% in Q2 to 6.4%. New business wins of $375 million rose 34%, the second straight quarter of 30%-plus growth. Year-to-date wins already exceed $1 billion, and management expects roughly $1.3 billion for the year versus about $1.1 billion in 2025. The pipeline reached a record $3.1 billion, up from $2.3 billion at the end of 2025, and the North American pipeline jumped more than 80%. Technology and consumer electronics revenue rose 19% on data-center demand, with new wins including Applied Materials, Boeing and NetApp. Management targets more than $850 million of secured incremental revenue entering 2027, versus $774 million entering 2026, and promised another quarter of 30%-plus win growth.
The margin explanation is credible but not yet proven. Management blamed startup costs, external implementation consultants brought in because wins arrived faster than capacity, and ongoing investment in commercial resources, the unified labor management system and GXO IQ. EBITDA margin did improve about 60 basis points sequentially from Q2's 6.4%. The labor system, now live across five countries, is expected to deliver 5% to 15% site-level labor savings starting in 2027. Wincanton integration is substantially complete with $60 million of run-rate synergies. Bears still have legitimate ammunition:
- The reaffirmed guidance implies Q4 adjusted EBITDA of roughly $275 million to $295 million, a meaningful step up from Q3.
- Q4 organic growth is guided only slightly above 5% on flat volumes.
- Secured 2027 incremental revenue of $630 million trails last year's comparable by about 10%.
- Net leverage has crept to 2.7x from 2.5x in Q1, and cash fell to $340 million after a $400 million bond repayment, even as buybacks reached $100 million year to date.
Investor sentiment improved substantially heading into the report, rising from -0.29 to -0.03. That leaves expectations close to neutral rather than skeptical, a less forgiving starting point than last quarter. The stock has gone essentially nowhere, up 1.9% since the open after the August report and trading just 0.5% above its $51.75 200-day moving average. In other words, the market has not yet paid for the commercial turnaround. The Earnings Whispers trend readings are mostly positive, with sequential growth, momentum and AVWAP all leaning favorably while price trend is neutral.
The bottom line is that GXO's commercial reset is producing measurable results: faster organic growth, sharply higher wins, a record pipeline and better revenue visibility into 2027. The earnings beat, however, was thin and engineered below the operating line, and EBITDA has not moved. With guidance held steady and an implied fourth-quarter ramp still to be delivered, the November 16 Investor Day becomes the real test. Management needs to show that the growth it is buying now converts into the margin expansion it keeps promising.
Read our earnings preview for GXO Logistics, Inc.: https://www.earningswhispers.com/article/GXO/21580
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 10 hours | |
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-15 | |
| Oct-08 | |
| Oct-07 | |
| Sep-29 | |
| Sep-28 |
