Optimum's Sub-$1 Stock Needs Proof Its Pricing Reset Can Slow Broadband Losses
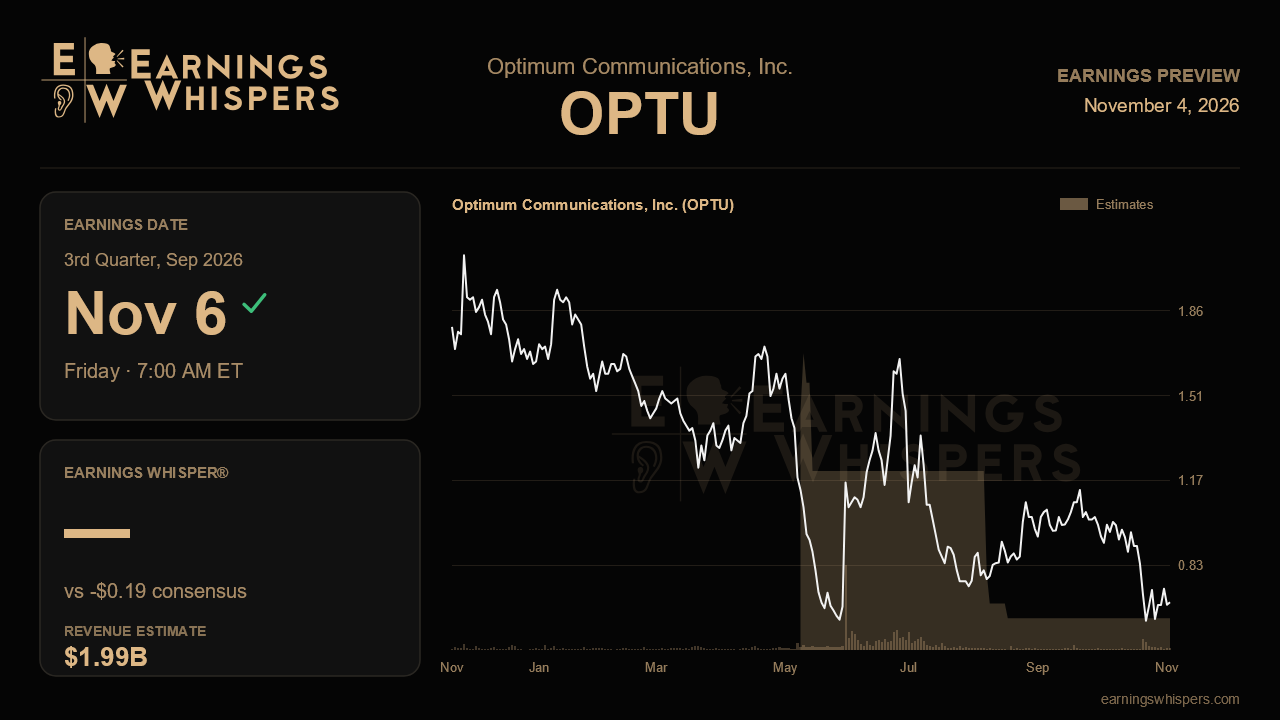
Optimum Communications heads into its third-quarter report with a story that has split in two. On the operating side, management has spent recent calls pointing to sharper cost control, the best adjusted EBITDA margins in years and a fast-growing LightPath fiber business. On the financial side, the company carries leverage of roughly 7.3 to 7.5 times EBITDA, a 6.8% weighted cost of debt and maturities moving closer. With the stock at $0.68, the market is plainly treating the second problem as the one that matters.
Wall Street expects a loss of $0.19 per share, matching the prior quarter's result, on revenue of about $1.99 billion. That compares with $2.02 billion last quarter, a sequential slip of roughly 1.5%, consistent with management's call for a mid-single-digit revenue decline in 2026. Consensus therefore sits squarely within the shrinking trajectory the company has already laid out. A headline beat or miss of a few cents matters less here than whether the composition of the quarter supports the turnaround thesis.
The central test is the deliberate trade management made this year. Optimum rolled out simplified national pricing and packaging, cheaper entry points and a loyalty program with price locks, explicitly accepting lower broadband and convergence ARPU in exchange for stabilizing a customer base that has kept bleeding, with losses of 62,000 broadband subscribers in the fourth quarter and roughly 56,000 in the first. That strategy is only worth its cost if net losses visibly narrow. A meaningful improvement in broadband net adds, ideally with better gross additions rather than just promotional churn management, would validate the reset. Continued losses near prior levels alongside falling ARPU would be the worst combination, since the company would be giving up price without winning back volume, and competitive pressure in the West, where fiber overlaps about half the footprint and fixed wireless roughly 80%, makes that risk real.
Margins are the second checkpoint. The fourth quarter delivered a 41.3% adjusted EBITDA margin and the first year-over-year EBITDA growth in 16 quarters, but management signaled that EBITDA would decline again in 2026 as pricing is reinvested. Investors should look at whether programming cost savings, falling video losses and AI-driven efficiencies, including the automation work with Google that improved dispatch rates, are cushioning that decline enough to keep margins near the 38% to 41% band seen recently. Mobile should also keep contributing; after 52,000 line additions early in the year and much lower churn, a slowdown there would remove one of the few volume growth engines.
LightPath remains the bright spot worth tracking closely. Revenue jumped 35% in the fourth quarter, awarded AI-related contract value reached $362 million, and the roughly $1.7 billion asset-backed financing showed the unit can raise capital on its own merits. Evidence that those contract awards are converting into revenue would reinforce the idea that Optimum owns at least one asset the market undervalues.
Sentiment has turned noticeably sour, swinging from moderately bullish before the last report to clearly bearish now. The shares have fallen 8.8% since the prior release, lagging the S&P 500 by nearly seven points, and trade well below the 200-day moving average of $1.17. At $0.68 the stock sits in the lower half of a wide post-earnings range between $0.48 and $1.15, which itself sits below the prior quarter's band. That pessimism lowers the bar for operations, but it also shows how little credit investors give to margin gains while the capital structure is unresolved.
Ultimately, this report must show that the pricing reset is slowing subscriber erosion without collapsing EBITDA, and any concrete progress on the debt reduction management keeps promising could matter more than the quarter itself. Without both, cost discipline alone is unlikely to change the narrative.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-30 |
Hedge Fund Arini Offloads $800 Million in Debt as Losses Deepen
OPTU +9.96% OPTU -8.90%
The Wall Street Journal
|
| Oct-08 | |
| Oct-01 | |
| Sep-24 | |
| Sep-22 | |
| Sep-18 | |
| Aug-31 | |
| Aug-28 | |
| Aug-14 | |
| Aug-12 | |
| Aug-07 | |
| Aug-06 |
