Taboola Misses And Cuts Its Full-Year Outlook As An AI-Driven Impression Decline Overshadows Margin Gains
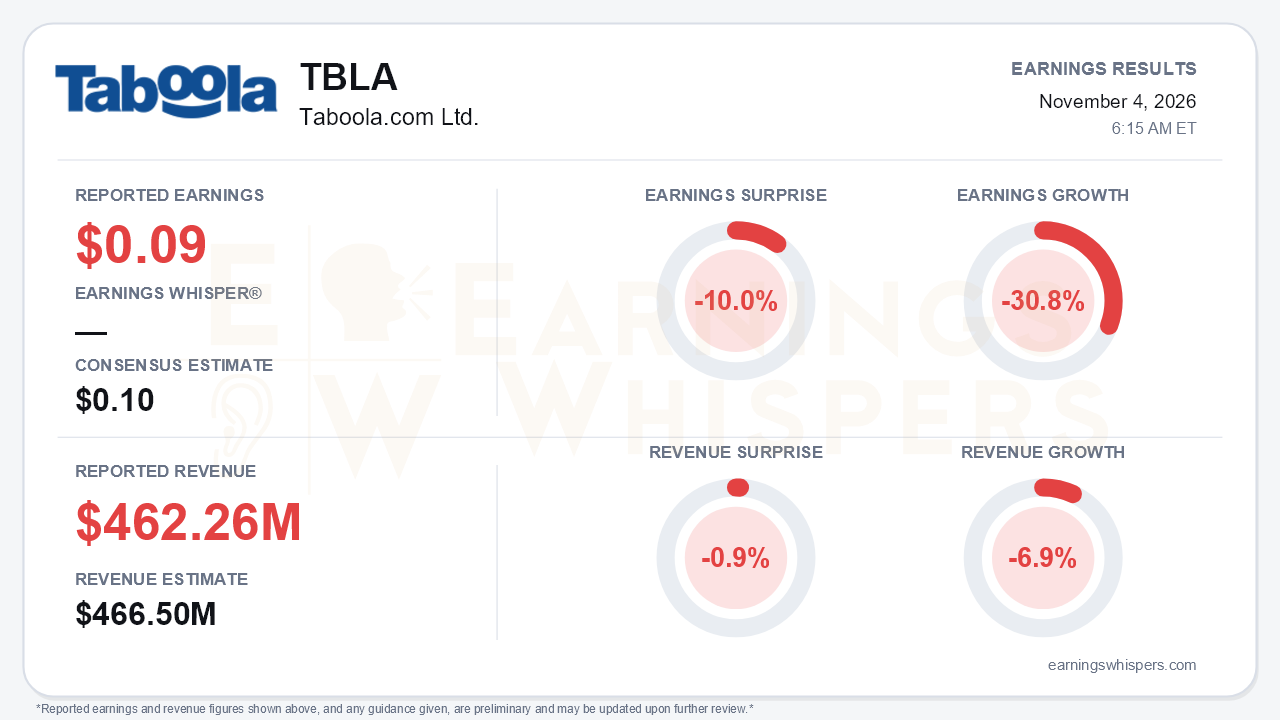
Taboola's third quarter ended a two-quarter run of guidance raises. The company reported earnings of $0.09 per share, missing the $0.10 consensus by 10.0%, and earnings fell 30.8% year over year. Revenue of $462.26 million came in 0.9% below the $466.5 million consensus and fell 6.9% from a year ago. The miss was narrow, but the guidance was not. Management cut every major full-year target and attributed the reset to a structural decline in ad impressions per page view, which it tied to AI- and LLM-driven changes in how consumers use the open web. That is the central tension. Taboola is extracting more profit from each impression, but it has fewer impressions to sell, and the call made clear this is not a one-quarter problem.
The quality of the quarter is mixed. Gross profit rose 9.6% to $152.3 million, and ex-TAC gross profit rose 6.8% to $188.8 million, as traffic acquisition costs fell faster than revenue. Adjusted EBITDA increased 16.1% to $56.0 million, and the margin on ex-TAC widened to 29.7% from 27.3%, or 31.6% excluding a roughly $3.4 million currency headwind. GAAP net income rose to $18.4 million from $5.2 million, helped by a sharp drop in depreciation and amortization. The company's own non-GAAP net income also increased, to $39.9 million from $34.3 million. That conflicts with the normalized year-over-year earnings decline above, so investors should note which basis they are using. Cash generation clearly weakened. Free cash flow fell to $20.4 million from $46.3 million as operating cash flow declined and capital spending more than doubled to $15.2 million. Net cash slid to about $50 million from $61 million in the second quarter and $84 million in the first.
The operating metrics show that demand weakened, not just supply. Revenue growth went from +9% in the first quarter to +2% in the second and then to -7%. Scaled advertisers swung from 3.5% growth in the first quarter to a 4% decline, and revenue per scaled advertiser moved from +5% to flat to -5% over the same three quarters. Management presented the improvement in ad rates as a byproduct of shrinking supply. That makes the margin expansion partly a symptom of the problem rather than a separate strength. NextEngage, the replacement for Explore More, is also ramping more slowly than expected.
The revised guidance quantifies the damage:
- Full-year revenue: now $1,882.5-$1,898.5 million, down from $1.93-$1.96 billion last quarter and $2.00-$2.06 billion in the first quarter.
- Ex-TAC gross profit: now $754-$763 million, down from $772-$783 million, which lowers implied growth to about 6% from 9%.
- Adjusted EBITDA: now $212-$221 million, down from $228-$240 million.
- Non-GAAP net income: now $151-$160 million.
The tone shifted just as much. Management had previously spoken of an inflection point and sustainable double-digit growth. Double-digit growth is now framed as an ambition, and management allowed analysts to treat the implied fourth-quarter trajectory as a reasonable base for 2027.
The call did preserve some credible offsets:
- NBCUniversal full-page monetization is now live on all NBCNews and Today.com inventory and performing as planned.
- Fox News has signed, alongside its local, sports and weather properties.
- Deeper Dive has grown from about 7 million users to about 14 million over two quarters and is now on more than 100 sites, plus a Motorola OEM integration.
- The proposed Dianomi acquisition, expected to close before year-end, would add a premium financial-publisher network including Reuters, CNN Business and the WSJ, though it brings integration risk.
- Capital return remains aggressive: about 7 million shares were repurchased for $30.3 million, and the board added a $200 million authorization.
These are real assets. The open question is whether they can outrun a headwind that management says is visible across its publisher base.
Investor sentiment heading into the report was still negative but had improved meaningfully, rising to -0.18 from -0.43 at the prior report. Investors were growing less pessimistic just as the outlook was cut, a setup the guidance reset may test. Price action had been less forgiving. Shares at $3.40 were down 8.8% since the open after the August report and sat 15% below the 200-day moving average of $4.00. The stock was 19% below its August 7 inter-earnings high of $4.20 and only 6.9% above its October 6 low of $3.18. The Earnings Whispers price and AVWAP trend readings are negative, while momentum and sequential growth are neutral.
The bottom line is that Taboola delivered the profitability it promised but lost the growth narrative that had been supporting the story. Margin expansion, new premium publishers and buybacks give the company tools to defend earnings. However, shrinking impressions, fewer and smaller scaled advertisers, weaker free cash flow and a lowered 2027 baseline give bears legitimate ammunition. Until NextEngage, Deeper Dive and Dianomi show they can restore revenue growth rather than just cushion its decline, the higher margins look like a partial offset, not a turnaround.
Read our earnings preview for Taboola.com Ltd.: https://www.earningswhispers.com/article/TBLA/21748
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 10 hours | |
| 15 hours | |
| Oct-30 | |
| Oct-28 | |
| Oct-27 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 | |
| Oct-05 |
New Study: Advertisers Increasing Budgets to Attract New Audiences, But 81% Fail to Reach Them; Advertisers Cite an Increasingly Fragmented Consumer Journey as a Problem and 92% Would Reallocate Ad Spend to the Open Web to Reach Untapped Audiences, if Identity and Measurement Challenges Were Solved
TBLA
GlobeNewswire
|
| Sep-30 | |
| Sep-29 | |
| Sep-22 | |
| Sep-21 |
