Groupon Must Prove July Rebound Was Real As Stock Sits Near Post-Earnings Lows
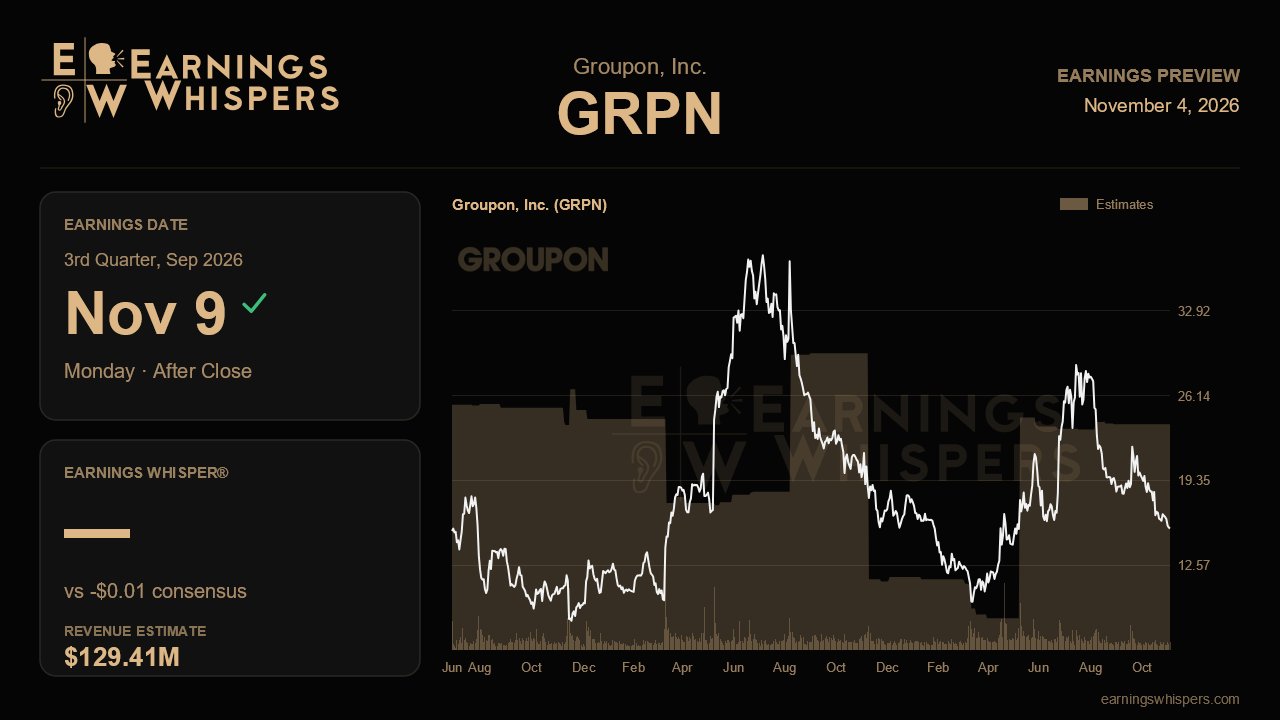
Groupon heads into its third-quarter report with a credibility problem that only revenue can fix. Last quarter, management conceded that the top line had slipped into negative territory, then asked investors to look past it. The pitch was that July had already reaccelerated, that a long platform migration was nearly finished, and that full-year targets still held. The market has not bought the story. Shares have fallen almost 42% since that report, so the November 9 release, due after the close, is less about a penny of earnings and more about whether the turnaround timeline survives.
The Street is looking for a loss of about a penny per share, compared with a loss of $2.92 a year ago. That comparison flatters the trend. The more telling figure is revenue of roughly $129.4 million, which would mean growth of about 5.4%. That would be a clear improvement from the prior quarter's $124.7 million and the slight year-over-year decline it represented. It would still be modest growth, not a sprint. Management's second-half outlook called for revenue growth of 6% at the low end and 10% at the high end. Consensus for the third quarter sits just under the bottom of that band, a sign that analysts are leaving room for disappointment even while the company maintains its targets.
The central operating question is North America local, the merchant-supply engine that has lagged expectations for several quarters. It caused the second-quarter shortfall. The deceleration has been steady: billings growth went from 11% to 4% to a slight decline over the reporting periods discussed last time. Management responded by hiring a new chief operating officer and a vice president of marketplace strategy aimed squarely at local supply. One quarter is too soon to expect a full fix. Still, investors should want signs that local billings stabilized and that the July reacceleration to mid-single-digit growth carried through August and September. The company also flagged double-digit growth in organic and search-driven traffic in July. That channel has been volatile as AI reshapes search, so durability matters more than a single strong month.
Several other threads deserve attention. The MobileNext platform migration was slated to finish by the end of this quarter. Confirmation that it is done would remove a multi-year distraction and give credibility to claims that the Project Foundry AI effort has more than doubled engineering output per developer. The McDonald's loyalty partnership and the new Trust and Quality initiative are early. Any evidence that they are bringing in customers or improving repeat purchases would help. On the financial side, adjusted EBITDA finished at the high end of guidance last quarter and free cash flow was a positive $15 million. However, management's own outlook implied negative free cash flow this quarter, so a cash burn would not by itself be a surprise. A larger-than-expected one would be.
Sentiment has warmed slightly. It is now only marginally bearish, compared with a noticeably more negative reading ahead of the last report. Price action tells a harsher story. At $15.50, the stock trades below its 200-day moving average of $17.64. It is sitting barely above its post-earnings low of $15.34, after peaking near $27.70. That pattern echoes the prior quarter's range, which was similarly wide, and suggests a shareholder base that sells hard on doubt.
The verdict hinges on one thing: whether third-quarter revenue growth looks like the start of the promised second-half acceleration or another quarter that pushes it out. Management itself warned that a slower pace would threaten its full-year goal. If growth lands at or above consensus, local shows stabilization, and the company reaffirms its outlook, the selloff may look overdone. If revenue falls short or the second-half range is trimmed, the market will likely conclude that the trough has not yet arrived.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Nov-03 | |
| Oct-15 | |
| Sep-16 | |
| Aug-19 | |
| Aug-18 | |
| Aug-13 |
The 'Mystery Vacations' That Give You No Idea Where You're Actually Going
GRPN
The Wall Street Journal
|
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-24 | |
| Jul-06 | |
| Jun-08 | |
| May-29 | |
| May-28 |
