Powerfleet's Guidance Cut Puts SaaS Momentum And Product Weakness To The Test
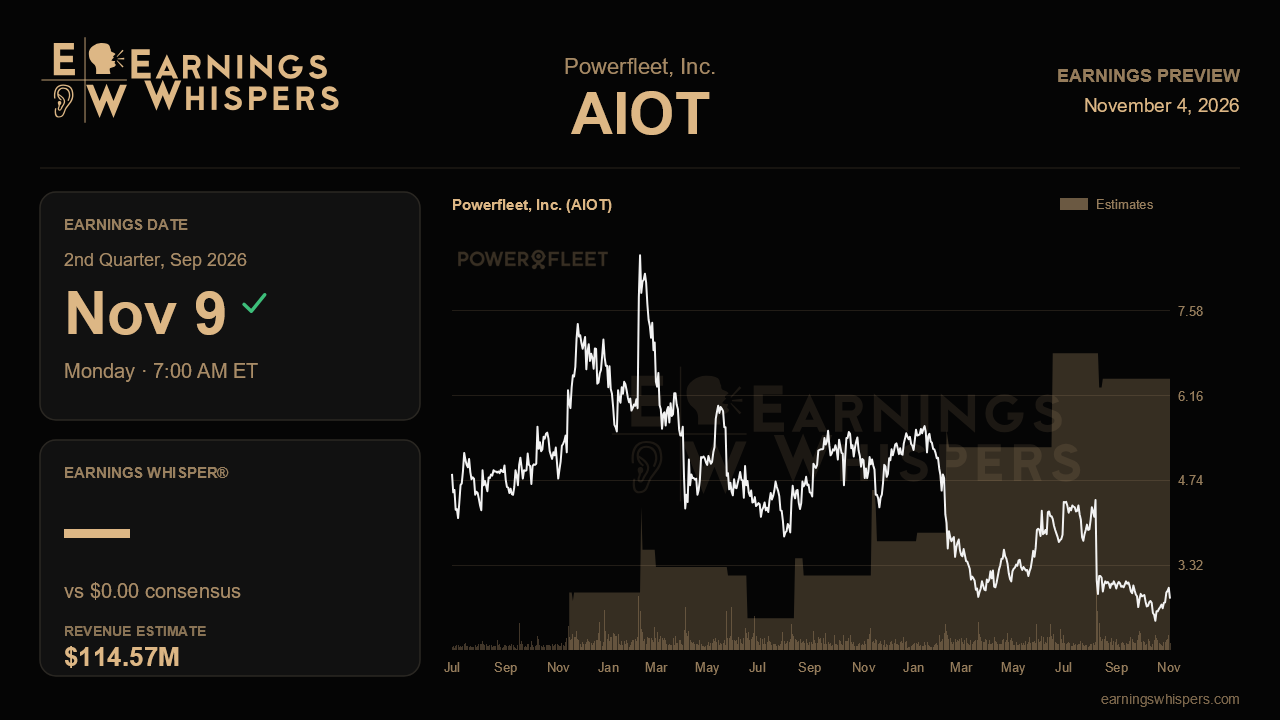
Powerfleet heads into its fiscal second-quarter report with an awkward contradiction to resolve. Last quarter's call celebrated record services revenue, fatter EBITDA margins and a string of fresh enterprise wins, and management nudged up the low end of its outlook. Since then the company has cut its fiscal 2027 revenue forecast to $468 million to $473 million, down from $485 million to $490 million. The November 9 release, due before the open, is the first chance to learn whether that cut reflects a temporary product hiccup or a broader slowdown in the growth story.
The quarterly bar is modest. Analysts expect revenue of about $114.6 million, up just 2.6% from $111.7 million a year ago, and roughly breakeven earnings per share versus a loss of $0.03 a year earlier. Growth that thin shows the large acquisition-driven jumps of recent quarters are no longer flattering comparisons. The bigger problem sits in the full-year math. Consensus for fiscal 2027 still stands near $487 million, above even the top of management's new range. Unless the Street has simply been slow to update, estimates look set to come down. A $114.6 million quarter annualizes to under $460 million. Hitting even the reduced outlook therefore requires a back-half step-up, so the commentary on the second half may matter more than the quarter itself.
The prior call offers clues about where the cut came from. Services revenue hit a record $86.5 million, up 53% year over year and rising to 83% of sales, with service margins around 76%. Product revenue was the weak spot. Tariffs made customers cautious about capital spending, sales cycles stretched out, and product margins slid to 25% from the low 30s. If the guidance cut traces mainly to hardware, the core subscription narrative survives intact. Steady sequential services growth and stable 67% adjusted EBITDA gross margins would support that view. If services growth is also stalling, the cut means something worse.
Several newer catalysts also need early signs of traction. The MTN arrangement, which moved the telecom from connectivity supplier to white-label distributor of the Unity platform across 16 countries, is the most important. Any early subscriber or revenue contribution would show it is more than a press release. AI video bookings jumped 52% sequentially last quarter, so further pipeline growth would show demand for the higher-value safety products is holding. The pace of new customer additions slowed to 14% sequential growth from 26% earlier in the year, and another slowdown would be hard to ignore. The South Africa Treasury contract and Accenture partnership, once the headline growth drivers, have already been pushed toward late fiscal 2027 or 2028. Any further delay would weigh on the long-term case.
The balance sheet is another pressure point. Net leverage climbed to 2.97 times EBITDA as management front-loaded integration spending. The company has promised a $30 million improvement in debt in the back half, and with revenue guidance lower, investors need evidence that cash generation can still deliver it. Progress toward the reset $18 million synergy target belongs in the same conversation.
The market has already punished the stock. Shares have fallen 9.5% since the last report, trailing the S&P 500 by more than seven points. At $2.76 they sit well below the 200-day moving average of $3.50, and the entire post-earnings range of $2.29 to $3.35 lies beneath the prior quarter's range. Sentiment has nonetheless swung from mildly bearish to mildly bullish, suggesting some investors see the guidance reset as clearing the decks. Whether that view holds depends on one question: can Powerfleet show that its high-margin subscription engine is still growing fast enough to offset a hardware slump while it brings leverage down?
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Oct-15 | |
| Oct-08 | |
| Sep-30 | |
| Sep-22 | |
| Sep-18 | |
| Sep-18 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Jul-27 | |
| Jul-21 | |
| Jul-01 | |
| Jun-30 |
