Marriott Vacations' Sales Turnaround Gathers Speed As 29% Contract Growth Outruns A Revenue Miss
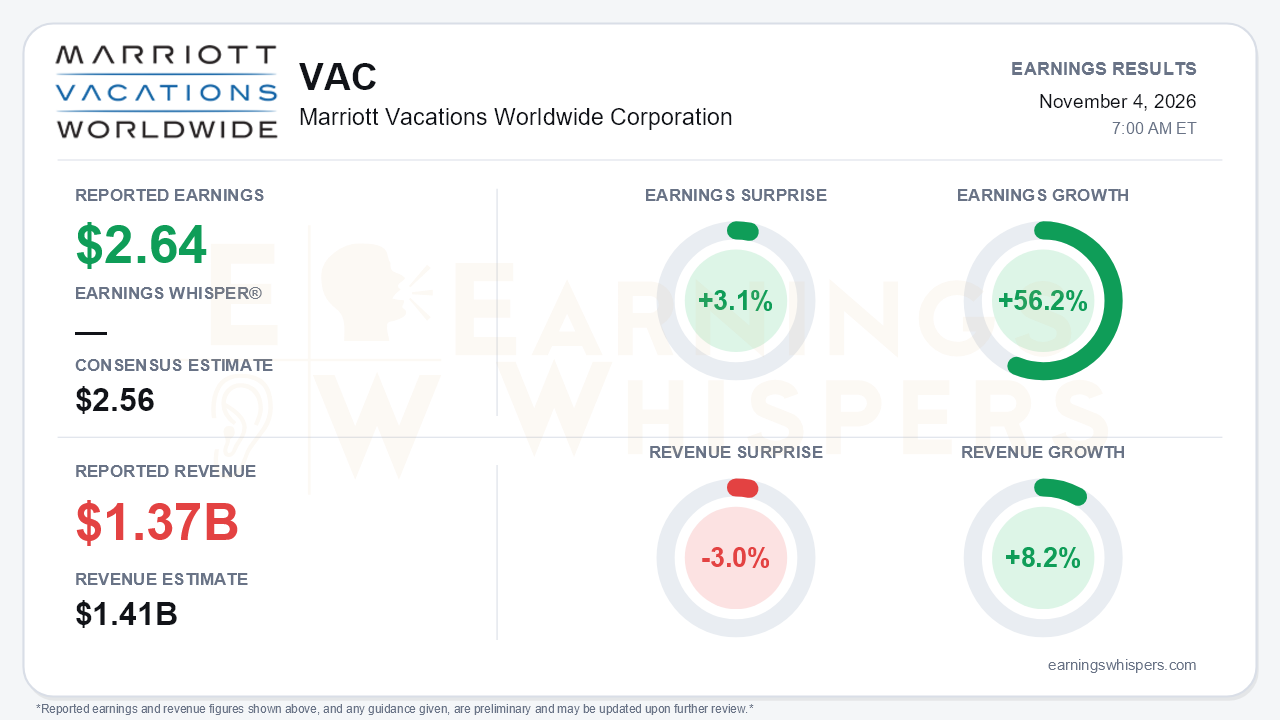
Marriott Vacations Worldwide delivered the kind of quarter that shifts a turnaround from promise toward proof. Adjusted earnings of $2.64 per share beat the $2.56 consensus by 3.1% and grew 56.2% year over year. On a GAAP basis, the company earned $2.24 per diluted share, compared with a $0.07 loss a year ago. Revenue of $1.367 billion rose 8.2% but missed the $1.41 billion consensus by 3.0%. That miss is the obvious blemish, and it says little about the core business. Revenue excluding cost reimbursements rose 14% to $921 million, while pass-through reimbursements were roughly flat at $446 million. The central development is in the timeshare engine. Contract sales jumped 29% to $565 million, extending a sharp acceleration from a 2% decline in the first quarter to 22% growth in the second.
The quality of the beat is better than the modest surprise suggests, though it deserves some scrutiny. Volume per guest climbed 30% to $4,822. That reflected average transaction sizes up more than $7,000 and a better close rate, which more than offset a 2% decline in total tours. The tour decline was tied to a deliberate pullback in Asia-Pacific, while North American tours rose 4%. Operating leverage was striking. Development profit nearly doubled to $142 million, and its margin widened to 31.0% from 20.2%, as marketing and sales costs fell to 48% of contract sales, 600 basis points better than last year. Adjusted EBITDA rose 27% to $216 million, after a 16% decline in the first quarter and 6% growth in the second. Two caveats apply. Adjusted net income grew 47%, so a lower adjusted diluted share count did some of the work behind the 56% EPS gain. And the rest of the business was far less dynamic. Rental profit fell 40% to $12 million on higher inventory costs and hurricane closures, and financing profit slipped 6%. Management and exchange profit was essentially flat, and G&A rose $18 million on incentive compensation.
The call preserved, and arguably strengthened, a credible growth story. Management described the transformation as being in its "second inning" and said September was the second-largest contract sales month in the company's 42-year history. Growth channels are scaling. Hotel linkage desks expanded to roughly 40 locations from four or five cited last quarter. The company implemented a second 2% price increase in October, following one in July. The 398 sales executives hired over six months are already producing $5,036 VPG, above the company average. The Inner Circle events platform is generating VPG above $20,000 at headline events, and management reaffirmed its target of 1,000 events in 2027.
Guidance moved higher, though the raise was incremental rather than dramatic. The full-year contract sales midpoint rose to $2.13 billion, and the adjusted EBITDA range narrowed to $810-830 million, absorbing an estimated $16 million hit from Hurricane Lowell. Adjusted EPS guidance moved to $8.65-9.15 from $8.25-9.05. The fourth-quarter outlook implies 33% contract sales growth and 23% EBITDA growth at the midpoints. Bears still have legitimate ammunition. Adjusted free cash flow guidance was cut to $410-430 million from $410-460 million, and expected cash conversion slipped to the low 50s percent. The sales reserve rose to 14.8% of contract sales from 13.4% as more buyers financed purchases. Funding is also more expensive: the October securitization priced at 5.91%, compared with 4.86% in April. In addition, net owner families fell about 4,000, and management flagged gas prices and interest rates as possible weights on consumer spending.
The balance sheet gives management more room to act. Net corporate leverage fell to 3.6 times from 4.0 times last quarter and 4.2 times in the first quarter. The board extended the remaining $322 million buyback authorization through 2027. Termination of the Puerto Vallarta project removes a $46 million 2028 inventory commitment. The December 9 investor day, where management plans to present a multi-year financial framework and capital allocation plan, is the next obvious catalyst.
The market setup is more complicated than the surprise implies. Shares entered the report at $118.59, up 7.1% since the open following the August report and 36.7% above their 200-day moving average. However, they sat 9.7% below the 52-week high of $131.34, set the day after that report, after falling as low as $96.80 in late September. Investor sentiment became slightly more positive heading into the release but remains only mildly positive. Most Earnings Whispers trend readings are positive, with sequential growth and momentum improving, while the price trend is neutral.
The bottom line is that Marriott Vacations' third quarter showed a sales turnaround that is accelerating rather than fading, with development margins and EBITDA growth that skeptics were not positioned for. The revenue miss, rising sales reserve, higher funding costs and trimmed cash flow outlook keep the story from being clean. Even so, the core engine is clearly improving, and the investor day will be the test of whether that momentum can become a durable multi-year framework.
Read our earnings preview for Marriott Vacations Worldwide Corporation: https://www.earningswhispers.com/article/VAC/21755
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-22 | |
| Oct-20 | |
| Oct-19 | |
| Oct-07 | |
| Sep-16 | |
| Sep-02 | |
| Aug-28 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-04 |
