Brink's Beats On Margin Expansion And Faster AMS/DRS Growth, But Thin Revenue, Slipping Cash Conversion And Heavy GAAP Charges Complicate The Story
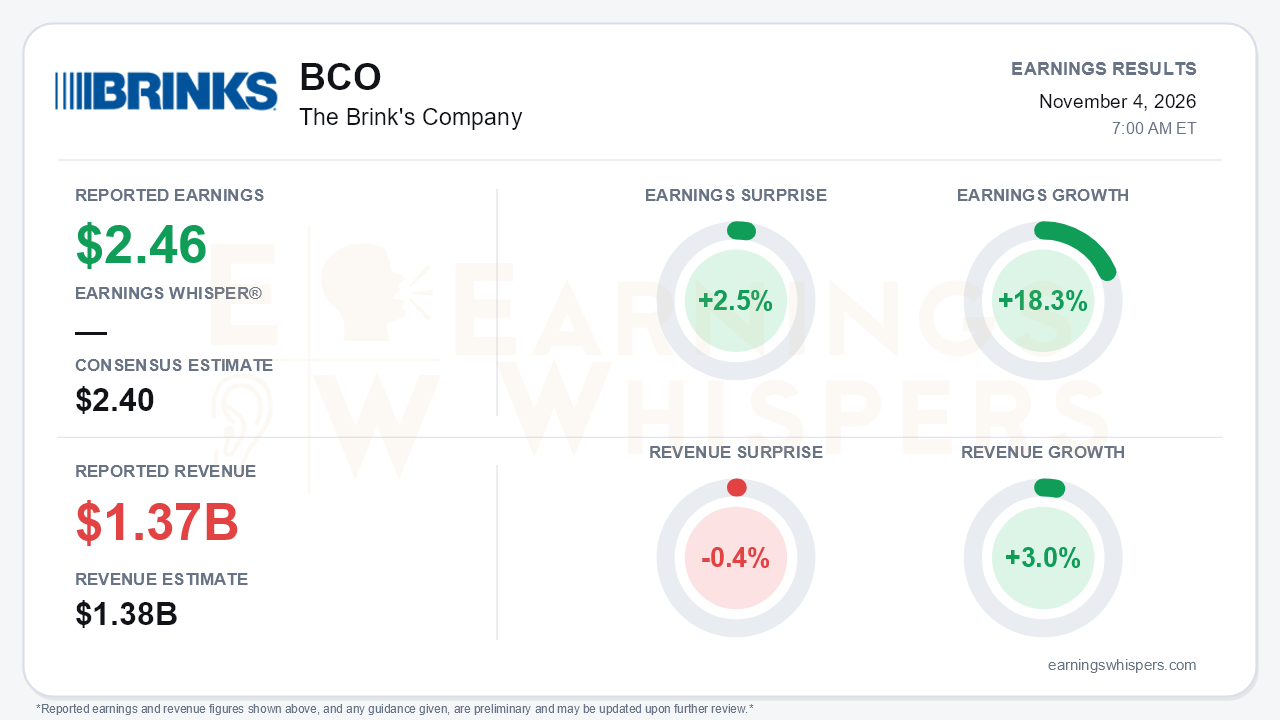
Brink's delivered a third quarter in which profit outran the top line. Non-GAAP EPS of $2.46 beat the $2.40 consensus by 2.5% and grew 18.3% year over year. Revenue of $1.375 billion rose only 3.0% and slipped 0.4% short of expectations. That is the central tension. Mix and pricing are driving faster earnings growth, but headline sales growth has cooled noticeably, from roughly $1.375 billion in each of the first two quarters to a quarter that was flat sequentially. Q3 adjusted EPS growth was the strongest of the year, while revenue growth was the weakest.
The quality of the beat deserves scrutiny on two fronts. First, the GAAP and non-GAAP pictures have diverged sharply. GAAP EPS fell 59% to $0.35, and net income attributable to Brink's dropped to $15 million. That decline reflects $45.7 million of NCR Atleos acquisition and transformation costs plus $26.6 million of incident-related losses: a $19.6 million precious-metals robbery and a $7.0 million flood at a North American warehouse. Second, the revenue line is noisier than it looks. Organic growth was 4%, but the deconsolidation of Malaysia removed $23 million, which flattened Rest of World's 14% organic growth into a 1% reported gain. The operating story itself was genuinely good. Segment operating margin reached 17.8%, up from 16.2%. Europe's operating profit jumped 31% to a 17.1% margin. Adjusted EBITDA of $274 million (+8%) landed above the guidance midpoint, with a 19.9% margin, 90 basis points higher year over year.
The call showed a business whose mix shift is accelerating. AMS/DRS organic growth exceeded 16%, up from 14% in Q2 and 15% in Q1. These lines reached a record 32% of revenue. EBITDA margin expansion has stepped up from 10 bps in Q1 to 70 bps in Q2 and 90 bps now. North America hit its 20% trailing EBITDA margin milestone. The flip side is that the legacy cash business is shrinking faster. Cash and valuables management organic revenue fell 1.5%, compared with slight growth in Q2 and +1% in Q1. Customers are converting to AMS/DRS at about twice the previously assumed pace, and global services is normalizing. Latin America grew only about 2% organically, with Argentina consumption and Mexican retail soft, and its organic operating profit fell 6%.
Forward-looking developments lean constructive but carry real cost. The NCR Atleos close has been pulled forward again, now to early January 2027 from "early Q1" on the prior call. Management says synergies should exceed the original $200 million target and arrive about a quarter sooner. The UK CMA remedy requires divesting Note Machine, roughly $125 million of revenue and $30 million of EBITDA, with sale proceeds unknown; management says the synergy case did not depend on it. Demand signals include:
- a U.S. DRS backlog up about 80%;
- a 5,500-location retailer deploying in early 2027;
- a Luxembourg bank-consortium ATM network win;
- a top Canadian bank contract.
Bears still have legitimate ammunition:
- Trailing free cash flow conversion slid to 40%, from 46% in Q2 and 50% in Q1, now at the bottom of the 40-45% framework.
- Nine-month operating cash flow fell to $155 million from $266 million.
- Some banks are delaying ATM outsourcing decisions until the deal closes.
- Currency flips to a greater-than-1% headwind in Q4.
- Interest expense rose to $66 million, ahead of a transaction that will add debt.
Guidance was reaffirmed rather than raised. Q4 calls for revenue of $1.365 to $1.415 billion, adjusted EBITDA of $275 to $295 million, and EPS of $2.45 to $2.80, against $2.54 a year ago. Organic growth is guided to 3-4.5%. That range leaves room for modest growth but also for a flat year-over-year quarter.
Investor sentiment improved meaningfully heading into the report, rising from -0.38 to -0.12, but it remains negative. That suggests skepticism is easing rather than reversing. Pre-report pricing reflects the same ambivalence. Shares at $108 were down 3.2% since the open following the August report and about 2.1% below the 200-day average of $110.28. They sat in the middle of an inter-earnings range that peaked at $119.16 on the day of the last report and bottomed at $97.75 on September 30. The stock has recovered about 10.5% off that low but has not regained the post-Q2 high. Price and AVWAP trend readings remain negative even as momentum has turned positive.
The bottom line is that Brink's is executing the margin and mix transformation it promised, with AMS/DRS growth, EBITDA margin expansion and the NCR Atleos timeline all moving in the right direction. Still, a modest revenue miss, an accelerating decline in the legacy cash business, weakening cash conversion and a widening GAAP gap mean the investment case increasingly rests on deal execution and synergy delivery beginning in January rather than on the standalone quarter.
Read our earnings preview for The Brink's Company: https://www.earningswhispers.com/article/BCO/21678
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-21 | |
| Oct-14 | |
| Oct-08 |
U.K. Regulator Says Brink's Disposals Could Clear Way for $4 Billion NCR Atleos Takeover
BCO
The Wall Street Journal
|
| Oct-08 | |
| Oct-01 | |
| Sep-30 | |
| Sep-29 | |
| Sep-23 | |
| Sep-18 |
