Intelligent Protection Management Must Prove Its Margin Slip Was Timing, Not Trend
Last quarter, Intelligent Protection Management asked shareholders to accept a simple argument: demand is fine, and the profit setback came from parts arriving late and costing more. The fiscal third-quarter report due after the close on November 10 is the first real test of that claim. The backlog management pointed to should start turning into revenue, and the money-losing order that spanned two quarters should be finished. If both happen, margins should recover. If they do not, the timing explanation becomes much harder to defend.
The Street's numbers frame an unusual setup. Consensus calls for revenue of about $6.4 million, up only 2.1% from a year ago and slightly below the $6.5 million booked last quarter. That is a sharp slowdown from the 13% to 15% growth of the past two quarters. Analysts nonetheless expect earnings of $0.02 per share, compared with a $0.10 loss last quarter and an $0.08 loss a year earlier. In other words, the forecast assumes softer sales but a big jump in profitability. That is an ambitious bar for a company that just posted negative adjusted EBITDA of $0.6 million and a $1.4 million net loss. Management has not issued formal quarterly guidance. Its standing goal is positive adjusted EBITDA in the fourth quarter, so a profitable third quarter would put the company ahead of its own stated schedule.
The key operating question is procurement. This hardware resale business has been the growth engine, rising 64% last quarter on demand for AI servers, storage and GPUs. It is also where the damage occurred. Shortages of memory, CPUs and GPUs delayed shipments, and higher component and freight costs turned one large order into an outright loss. Management said it has widened its network of suppliers, distributors and manufacturers to reduce that risk. Investors should look for evidence the fix is working: procurement gross margin back in positive territory, fewer delayed shipments, and some of the $4.5 million in deferred revenue converting to recognized sales. A further rise in deferred revenue alongside flat revenue would be a warning sign that the backlog is building faster than the company can deliver it.
The recurring side of the business deserves equal attention, because it determines the quality of any recovery. Managed IT growth slowed to about 8% from 19% the quarter before. Professional services fell 47% and subscription revenue declined, while revenue from related party NewTekOne keeps shrinking as that customer cuts IT spending. If managed IT re-accelerates, helped by private cloud and private cloud AI demand at the Phoenix data center, the business mix improves and the growth story looks sturdier. Further erosion in services would mean procurement, a lower-margin business, is carrying more of the top line than is comfortable.
Cash also matters for a company this size. Cash has fallen from $8.4 million to $7.5 million over two quarters, as buying inventory consumed working capital. Stabilizing that balance, or showing that inventory is being sold through, would support management's view that the drain was temporary.
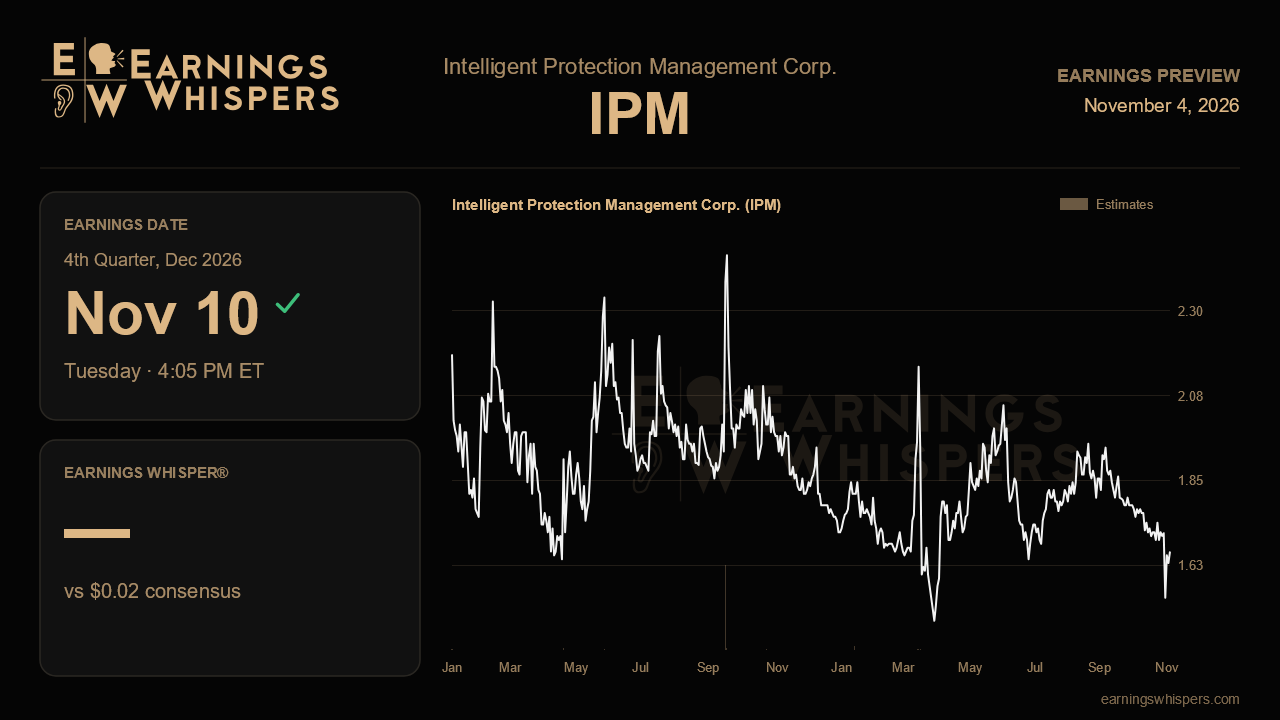
The mood has thawed somewhat without turning optimistic. Sentiment readings show 43.2% bearish, compared with uniformly bearish heading into the last report. The stock has drifted down 3.5% since then, slightly worse than the broader market. At $1.64, it sits in the lower half of its post-earnings range of $1.37 to $2.00. That range is wider and lower than the prior quarter's, which reflects lingering doubt rather than conviction either way.
The central issue is whether the supply-chain disruption was a temporary pause in a business moving toward breakeven, or a sign that its fastest-growing segment carries structurally thin margins. Recovering gross margins and adjusted EBITDA near breakeven would keep the fourth-quarter profitability goal credible. Another quarter of losses on procurement would make that goal look like a moving target.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-04 | |
| Nov-03 | |
| Oct-22 | |
| Sep-24 | |
| Sep-09 | |
| Aug-12 | |
| Aug-11 | |
| Aug-04 | |
| Jun-08 | |
| May-21 | |
| May-19 | |
| May-13 | |
| May-12 |
