Accelerant Nears Breakout As Street Braces For Halved Profit On Flat Revenue
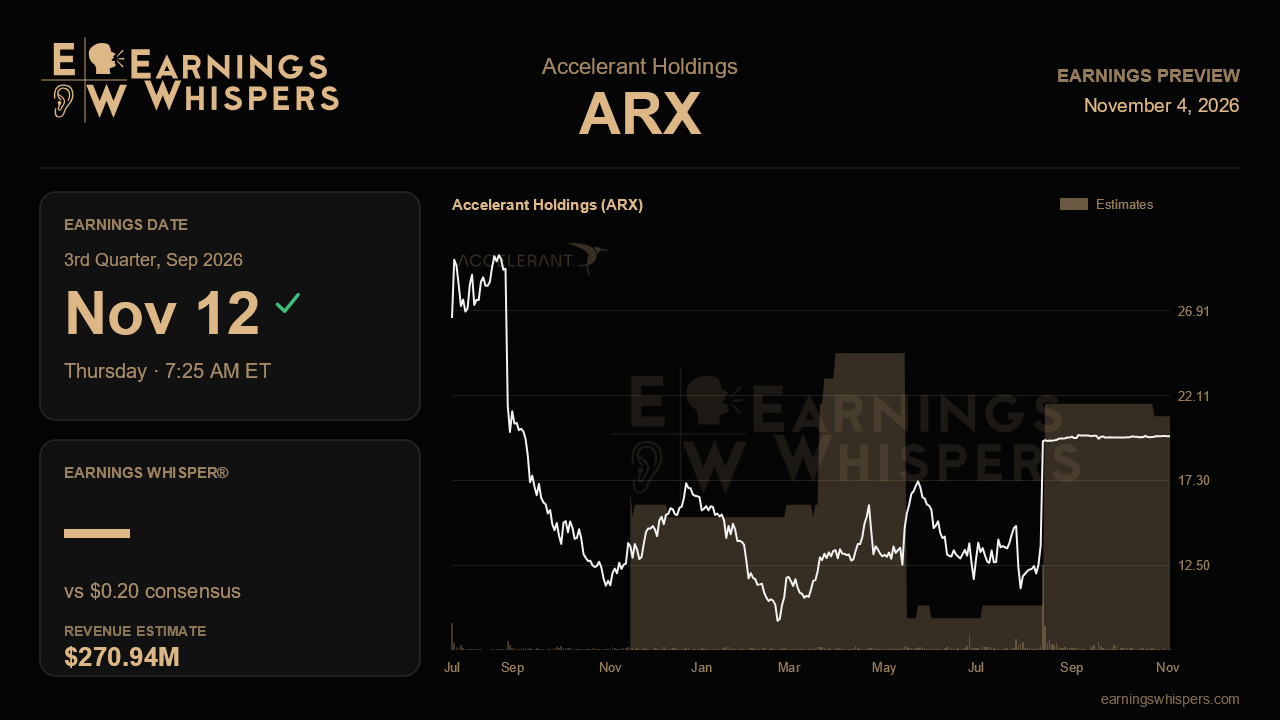
Accelerant Holdings heads into its third-quarter report with an odd mismatch between its stock chart and its earnings forecasts. The shares are pressing against their highs, yet Wall Street expects profit to fall by nearly half from a year ago on revenue that barely grows. When the specialty insurance risk exchange reports before the opening bell on November 12, the central question is whether the market has already looked past a soft quarter, or whether the numbers will force a reassessment.
Consensus calls for earnings of $0.20 per share on revenue of about $270.9 million. That revenue figure would be up only 1.3% from the $267.4 million posted a year earlier, essentially flat for a company that sells itself on growth as a data-driven marketplace. The earnings comparison is harsher. A year ago Accelerant earned $0.38 per share, so the Street is bracing for a decline of roughly 47%. The sequential picture is just as striking. Last quarter the company produced $356.9 million in revenue and $0.32 per share, which means analysts are modeling a revenue drop of close to a quarter from the prior period. Management has not supplied formal guidance, so the Street's numbers stand on their own as the bar.
That sequential gap is the most important thing to understand going into the release. Accelerant's model depends on the flow of specialty risk between the underwriters on its platform and the capital providers that back them, and revenue in that kind of business can be lumpy depending on timing, volume and how risk is placed. If the lower forecast reflects timing rather than a slowdown in underlying activity, the company has room to look better than feared. If, however, the decline reflects softer placement volume, thinner economics per dollar of risk, or a cost base growing faster than revenue, the weaker earnings outlook could prove to be more than a one-quarter story. Halving profit on flat sales implies meaningful pressure on margins somewhere, and the report should clarify where.
Evidence that would support the bull case includes revenue landing at or above the year-ago level with clear signs that activity on the exchange is still expanding, along with expense discipline that keeps the profit decline shallower than modeled. A result that challenges the story would be revenue that falls short of even this modest bar, or commentary suggesting that last quarter's strength was unusual rather than a new baseline.
The market's posture is cautiously supportive. The stock has risen 1% since the last report while the S&P 500 slipped 2.7%, a modest but real outperformance. At $19.81, shares sit well above their 200-day moving average of $15.03 and within a hair of the post-earnings high of $19.90, so they are effectively testing a breakout. The recent trading band has also been remarkably tight compared with the previous quarter's swing between $10.77 and $17.85, a sign the stock has settled after a volatile run. Sentiment has cooled, though, with bullish readings slipping from 46.8% ahead of the last report to 37.8% now, suggesting enthusiasm is more restrained even as the price holds firm.
That combination makes this report a genuine test. Expectations for the quarter itself are low, but the stock is priced near its highs, implying investors are paying for the longer-term growth of the exchange rather than this quarter's earnings. For that view to hold, Accelerant needs to show that the expected profit slump reflects timing or investment rather than eroding demand for its platform. Clarity on whether the prior quarter's revenue run rate is repeatable will likely decide whether the shares break higher or slip back into their range.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Nov-02 | |
| Sep-23 | |
| Sep-23 | |
| Sep-15 | |
| Aug-24 | |
| Aug-17 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Jul-23 | |
| Jul-13 | |
| Jul-01 |
