Innospec's Margin-Led Beat Comes With Slower Sales, A Weaker Oilfield Quarter, And A Volume Recovery Pushed To 2027
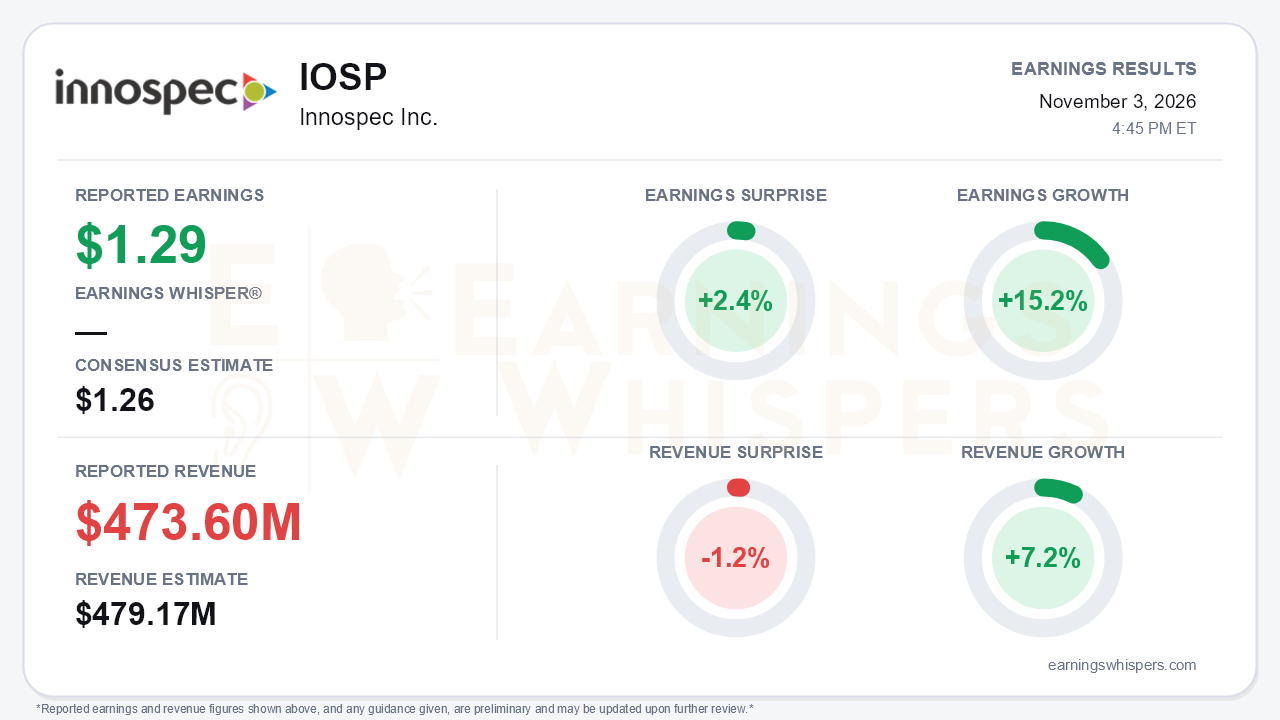
Innospec delivered the earnings acceleration investors had been waiting for, but the top line moved the other way. The specialty chemicals maker reported third-quarter earnings of $1.29 per share, 2.4% above the $1.26 consensus and up 15.2% year over year. That is a clear improvement from the essentially flat adjusted EPS of Q2 ($1.27 vs. $1.26) and the decline in Q1. Revenue of $473.6 million rose 7.2% but missed the $479.17 million consensus by 1.2%. Sales growth slowed from 12% in Q2, and revenue fell sequentially from $491.4 million. That is the central tension: margins are carrying the story while volumes and sales momentum are not.
The quality of the beat is better than the GAAP comparison alone suggests. GAAP EPS jumped from $0.52 to $1.29, but that comparison is flattered by roughly $33 million of impairments in the year-ago quarter. The more meaningful figure is adjusted EPS, which rose from $1.12 to $1.29, and this quarter GAAP and adjusted results were identical. Segment operating income rose about 31% to $40.6 million, and adjusted EBITDA increased to $51.4 million from $44.2 million a year ago and $50.1 million in Q2. These gains came despite a higher adjusted tax rate (24.7% vs. 22.7%) and sharply lower interest income. That points to genuine operating leverage. Cash generation is a different matter. Operating cash flow fell to $17.4 million from $39.1 million, and year-to-date working capital has absorbed $87.4 million as receivables and inventories climbed. As a result, net cash has slipped from $292.5 million at year-end to $251.9 million, and no buybacks were cited this quarter after modest repurchases in Q1 and Q2.
Performance Chemicals was the standout and the clearest example of the margin-over-volume dynamic. Operating income surged 84% to $16.9 million, and gross margin reached 18.8%, up 3.7 points year over year and up from 17.3% in Q2 and 16.8% in Q1. Yet volumes fell 5%, worse than the 2% decline in Q2, with 12% price/mix doing all the work. On the call, management guided Q4 for the segment roughly in line with Q3. It also described the recapture of lost share as a 'slow curve' into 2027, a retreat from the Q2 hint of a fourth-quarter uptick. The North Carolina efficiency upgrades remain on track for year-end commissioning, with management previously citing more than 10% added capacity and better yields. Both the growth thesis and the capacity payoff are now explicitly 2027 stories.
Oilfield Services is where bears have the most legitimate ammunition. Year over year the segment looks fine: revenue rose 13% and operating income 40%, helped by the DRA plant expansion. But operating income fell to $6.7 million from $8.7 million in Q2, and gross margin dropped to 28.2% from 32.3%. Management blamed Middle East activity delays and elevated raw material costs. This quarter therefore missed management's own Q2 call outlook for second-half sequential improvement. Management is now calling for sequential operating income growth in Q4 on a return of Middle East activity, and Mexico still contributes no sales. Fuel Specialties remained the steady anchor, with revenue up 5% on 3% volume growth, but operating income rose only 1%. The release puts gross margin at 35.1%, down 0.5 points year over year. The call analysis cited a sharper sequential slide to 31.5% from 36.6% in Q2, a figure that does not reconcile with the segment table. What both sources do agree on is pressure from raw-material and freight inflation and pass-through lag.
Management tried to shift attention toward cash. It guided Q4 free cash flow to $40-50 million as the working capital build partially reverses, and it offered a first 2027 framework of $55-60 million in free cash flow on roughly $60 million of capex. The 9% dividend increase, to $0.94 semi-annually, signals confidence. With no debt, the balance sheet retains ample flexibility for M&A or buybacks.
The market had already been leaning into the margin recovery. Shares are up 9.9% since the open following the August report and, at $99.23, sit 17.4% above the 200-day moving average of $84.53. Price, momentum and AVWAP trend readings are all positive. Investor sentiment improved meaningfully, rising from -0.18 to +0.09. It has moved from mildly negative to modestly positive rather than exuberant. That setup leaves less room for error, given that the forward volume narrative just slipped by a quarter or more.
The bottom line is that Innospec proved it can grow earnings through pricing, mix and margin repair even as sales slow. The near-term growth drivers, however, look softer than they did three months ago. Performance Chemicals volume recovery has been deferred to 2027, Oilfield missed its own sequential outlook, and cash conversion has lagged earnings. With the stock well above its long-term average and sentiment now positive, the Q4 cash rebound and Oilfield recovery have become the promises management needs to keep.
Read our earnings preview for Innospec Inc.: https://www.earningswhispers.com/article/IOSP/21588
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-05 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-08 | |
| Jul-06 | |
| Jun-30 | |
| May-07 | |
| May-07 | |
| Apr-07 | |
| Mar-09 |
