NRP's Earnings Fall 14.5%, But The Debt Payoff Unlocks A Tripled $2.34 Distribution
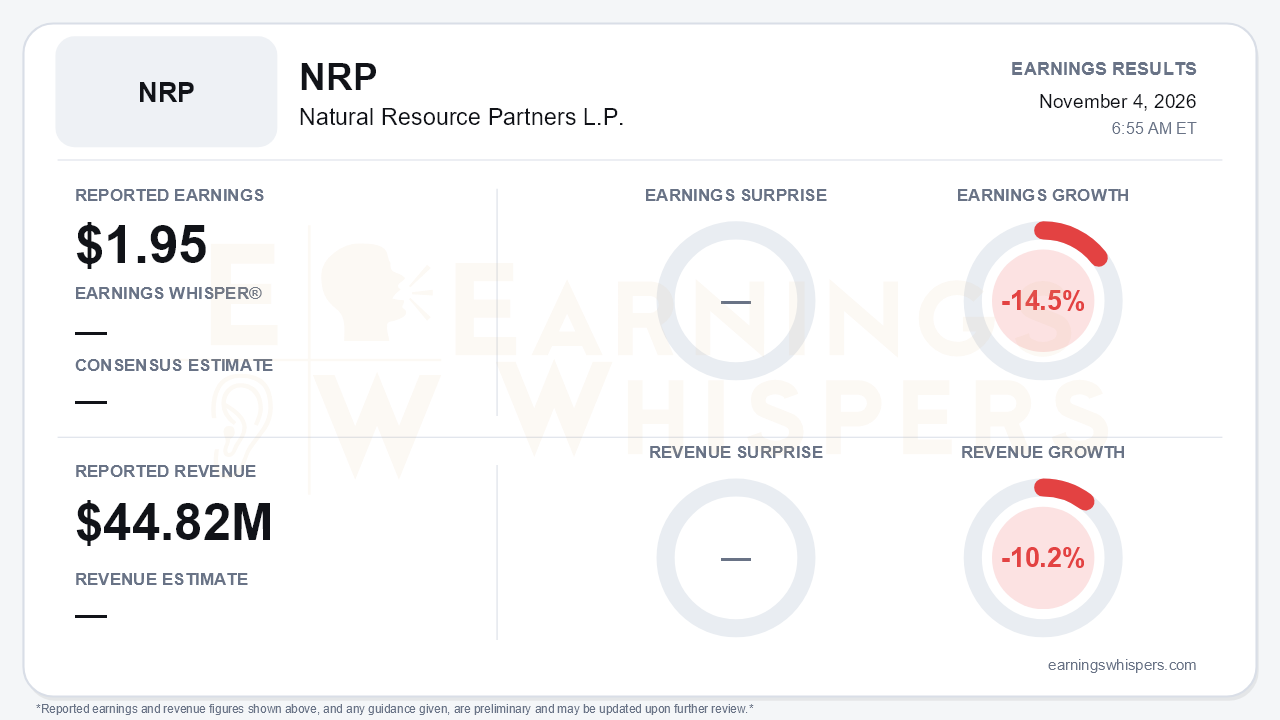
Natural Resource Partners reported third-quarter earnings of $1.95 per unit on revenue of $44.82 million. Earnings fell 14.5% from a year ago and revenue fell 10.2%. No consensus estimate was available, so the quarter cannot be scored as a beat or a miss. That matters less than usual, because the income statement was not the story. NRP fully repaid its credit facility and raised the quarterly distribution to $2.34 per common unit from $0.75, an increase of more than threefold. Management had signaled this payout for most of the year. The central tension is that NRP has nearly finished de-risking its balance sheet just as all three of its key commodities, metallurgical coal, thermal coal and soda ash, face what management called a "challenging market environment."
The decline in earnings comes mostly from accounting and from the soda ash investment, not from a collapse in the royalty business. Depreciation, depletion and amortization rose to $6.5 million from $3.9 million after revised engineering raised the depletion rate at a thermal property. That change alone accounts for much of the $3.9 million drop in Mineral Rights net income. The equity loss from Sisecam Wyoming widened to $4.1 million from $2.4 million as soda ash prices stayed weak.
Cash generation held up better than earnings. Free cash flow was $44.8 million, up from $41.8 million a year ago and $41.7 million last quarter. Part of that gain came from a $5.2 million release of accounts receivable. Adjusted EBITDA slipped to $37.7 million from $38.9 million. On a trailing basis, Adjusted EBITDA has fallen to $153 million from $186 million a year earlier, mainly because Sisecam distributions have stopped. The lower earnings base is real.
The coal royalty book was mixed. Coal sales volumes rose to 8.17 million tons from 7.53 million, driven by Northern Appalachia. The combined royalty rate eased to $4.40 per ton from $4.51. Total coal royalty revenue still edged up to $35.1 million, and metallurgical coal supplied about 70% of it.
The weakness sits in other revenues, which fell to $11.8 million from $15.4 million. The main drivers were lower property tax revenues, lower minimum payments and lower lease amendment fees, along with softer oil and gas royalties. On the call, management pointed to a steady sequential climb in free cash flow:
- Consolidated free cash flow (before the first-quarter soda ash investment): $34 million in Q1, $42 million in Q2, $45 million in Q3.
- Mineral rights free cash flow: $43 million, $45 million, $47 million over the same quarters.
The outlook is where bears have legitimate ammunition:
- **Coal:** NRP expects no meaningful change in coal pricing in 2027. Steel demand remains soft, cheap natural gas and full stockpiles are capping thermal prices, and diesel costs up more than 75% this year are squeezing lessee margins.
- **Soda ash:** The outlook is worse. Chinese capacity has outrun global demand, and international prices sit below most producers' cost of production. Management expects domestic contract prices to reset lower, making 2027 harder than 2026, and sees rebalancing taking years rather than quarters.
- **Sisecam distributions:** No distribution has arrived since the second quarter of 2025, and none is expected near term. The $39 million NRP invested in the business earlier this year is producing no cash return.
The forward-looking change is in capital allocation. With leverage at 0.1x and only $14.3 million of debt left, due in December, the board is moving to a variable distribution framework that pays out free cash flow each quarter. It named unit repurchases and opportunistic acquisitions as possible uses of retained cash. This quarter's $2.34 payout matches the full $31.7 million of free cash flow available for distributions.
That framework cuts both ways. Payouts will now move directly with commodity-driven cash flow. The fourth quarter still carries the final debt repayment. Lumpy items, like this quarter's working-capital tailwind, will feed straight into the distribution. Investors should treat $2.34 as a reflection of one quarter's cash generation, not a fixed run rate. Management's tone was noticeably more celebratory, and that is earned on balance-sheet execution. Its tone on fundamentals was more guarded.
Investor sentiment readings and a current price were not available for this report. The units opened at $102.00 after the August release, below the current 200-day moving average of $111.17. That suggests the market was already discounting the weak commodity backdrop heading into the quarter. Whether the distribution step-up changes that view will depend on how durable investors judge the higher payout to be.
The bottom line is that NRP delivered exactly what it promised on deleveraging and distributions, even as reported earnings and revenue declined. The partnership now converts nearly all of its royalty cash flow into payouts, backed by $251.7 million of liquidity. However, flat coal pricing, a deteriorating soda ash outlook for 2027 and a distribution policy that will rise and fall with free cash flow mean income-focused holders are trading balance-sheet risk for commodity-cycle risk.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Oct-21 | |
| Aug-05 | |
| Jul-22 | |
| May-20 | |
| May-06 | |
| Apr-22 | |
| Mar-10 | |
| Mar-06 | |
| Mar-05 | |
| Mar-05 | |
| Mar-04 | |
| Feb-28 | |
| Feb-27 |
