NIQ Faces A Higher Bar As AI Pipeline And Sixth Straight Beat Come Under Scrutiny
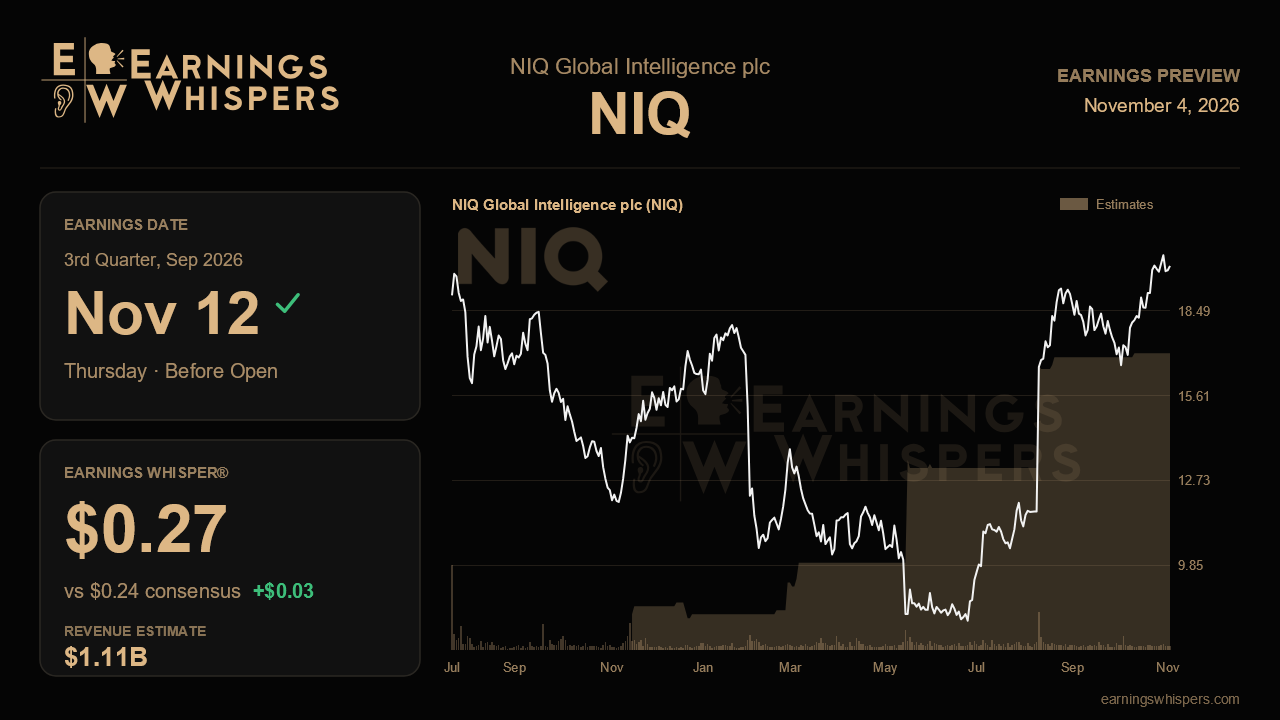
NIQ Global Intelligence enters its third-quarter report with a problem most companies would welcome: it has beaten the top of its own organic revenue guidance five quarters running, raised every line of its full-year outlook, and watched its stock climb 46% since the last report while the S&P 500 slipped. The question now is whether another tidy beat-and-raise is enough, or whether a stock trading near its post-earnings high needs evidence that the artificial intelligence story is moving from pilot programs toward revenue.
The Street is looking for earnings of $0.24 a share on revenue of $1.11 billion, roughly 5.5% growth from the $1.05 billion posted a year ago. That is solid, steady growth for a subscription data business rather than a breakout, but the earnings comparison is dramatic, with last year's quarter producing just $0.03 a share. Management guided to $0.22 to $0.24 in earnings on revenue of $1.105 billion to $1.108 billion, so consensus sits at the very top of the EPS range and slightly above the revenue range. The Earnings Whisper of $0.27 is a meaningful step above consensus, signaling that the more enthusiastic crowd expects NIQ to clear its own guidance by a comfortable margin again. Notably, the full-year consensus of $0.98 still sits well below the raised $1.08 to $1.12 guide, suggesting some annual estimates have not fully caught up with the company's improved outlook.
The prior call laid out a clear scorecard. Organic constant currency growth accelerated to 5.8% in the second quarter, yet the implied guide for the back half sits closer to 5.2% to 5.5%. A print near or above the top of that band would extend the pattern of conservative guidance followed by outperformance; a result at the low end would raise the question of whether the second quarter was a high-water mark. Margins deserve equal attention. Adjusted EBITDA margin expanded 270 basis points to 23.3%, helped by restructuring savings now targeted around $75 million for the year, and the full-year margin guide of 23.5% to 23.9% implies continued progress. Free cash flow, which turned positive last quarter, should keep building toward the $245 million to $255 million target, and further reduction in leverage from 3.1 times would reinforce the balance-sheet repair story.
Geography offers a useful stress test. Asia Pacific swung back to growth after a negative first quarter, validating management's push to repair retailer relationships, and the Yimian acquisition adds China and Southeast Asia e-commerce data. Sustaining positive growth there would confirm the turnaround is real rather than a one-quarter bounce. Europe and the Middle East remain the softer flank, with regional conflict cited as a backdrop.
The AI narrative is where the stock's rerating likely lives, and it is also where expectations could run ahead of the numbers. Management explicitly excluded material AI revenue from 2026 guidance and framed this as a foundation year, with commercial scaling deferred to 2027. So this report will not be judged on AI dollars. It will be judged on traction: conversion of the 49-opportunity Connect AI pipeline beyond the named charter clients such as Purina, early uptake of Optic Bridge after its September launch, continued growth in AI-native revenue that rose 34% last quarter, and timing on the agentic commerce measurement product. Progress with new buyer types such as ad tech platforms and retail media networks would also support the argument that NIQ's data has value beyond consumer packaged goods.
Sentiment has flipped from mildly bearish heading into last quarter to modestly bullish now, and the shares at $20.01 sit about 3% below the $20.56 post-earnings high and far above the 200-day average near $13.26. That leaves the stock testing a breakout with little cushion for disappointment. The central issue is whether NIQ can pair a sixth straight core beat with concrete evidence that its AI pipeline is converting, because steady execution alone may already be reflected in the price.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Nov-09 | |
| Nov-04 | |
| Nov-02 | |
| Oct-30 | |
| Oct-29 | |
| Oct-28 | |
| Oct-22 | |
| Oct-21 | |
| Oct-15 | |
| Oct-08 | |
| Oct-06 | |
| Oct-06 | |
| Oct-02 | |
| Sep-30 |
