Spectrum Brands' Fiscal-Year Finale Tests Whether The Pet And Garden Rebound Can Outrun HPC
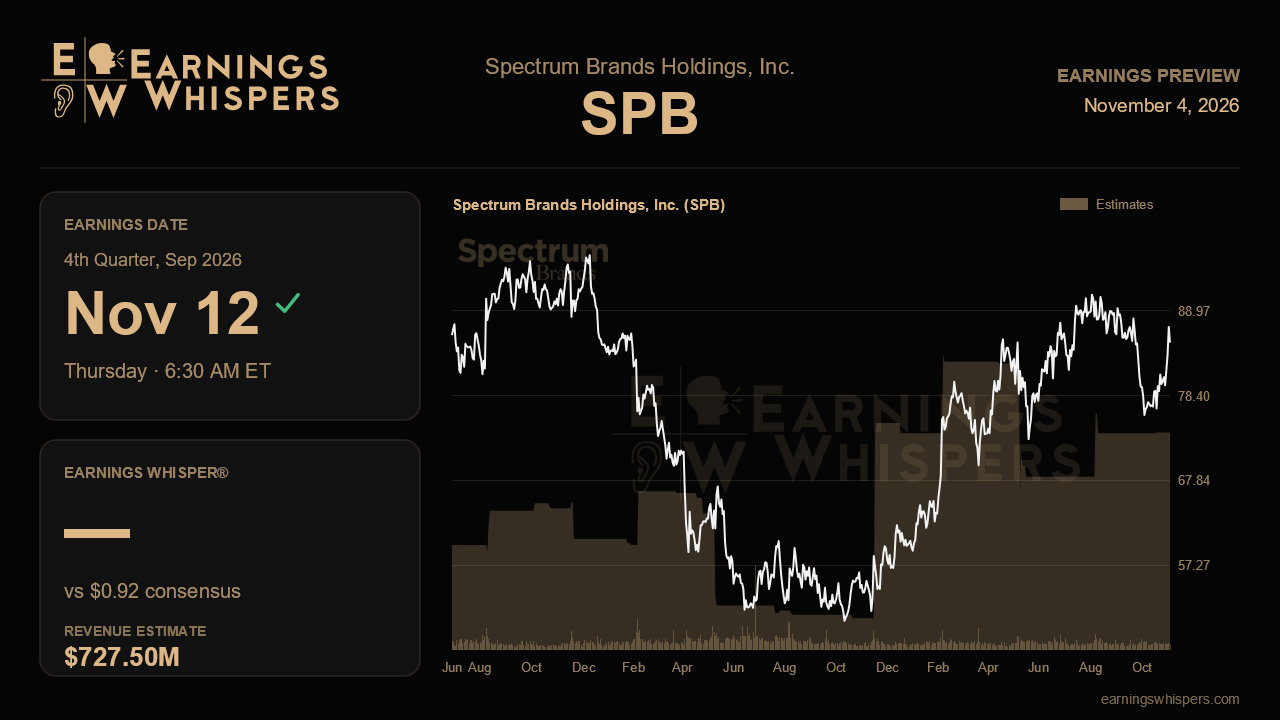
Spectrum Brands heads into its fiscal fourth-quarter report with an awkward contrast. Management spent much of fiscal 2026 telling a recovery story, with tariff damage contained, Global Pet Care and Home & Garden growing again, and an adjusted EBITDA outlook nudged higher. The stock has not followed that script. Shares are down about 12% since the last report, roughly 10 percentage points worse than the S&P 500. The November 12 release, due before the open, closes the books on the year management raised its profit outlook for, and it should show whether that confidence was earned.
The Street expects earnings of $0.92 per share on revenue of about $727.5 million. Revenue would be down just 0.8% from a year ago, while EPS would fall nearly 65% from the $2.61 posted in the same quarter last year. Those two figures do not fit together comfortably. Flat sales paired with a collapse in per-share earnings suggests the year-ago comparison carried items that will not repeat, rather than a sudden break in demand. The sequential step down from the prior quarter's $2.79 also fits a seasonally softer stretch once the garden season fades. Either way, the revenue line and segment margins will say more about the business than the headline EPS change.
Because this is the fiscal year-end report, the most useful benchmark is management's full-year framework. Adjusted EBITDA guidance moved from low single-digit growth to low-to-mid single-digit growth as the year went on, while net sales guidance stayed at flat to low single-digit growth through every update. Fourth-quarter revenue near consensus would put full-year sales within that conservative range. The real question is whether EBITDA growth reaches the upper half of the raised target. Landing at the low end would make the raise look like a quarter's worth of good weather rather than a durable improvement in mix.
The segments will tell that story. Global Pet Care organic growth accelerated from 5.8% to 7.6% earlier in the year, with margins around 19%. Continued mid-to-high single-digit growth, now that the EMEA SAP system migration is done, would support the view that pet is the company's dependable engine. Home & Garden is harder to judge. Its swing from a nearly 20% decline to 11% growth leaned partly on timing and a record-warm March, so investors need evidence that full-season sell-through held up instead of being pulled forward. Home & Personal Care remains the weak spot, with organic sales down double digits, EMEA hit by retailer destocking, and Chinese competition flooding European shelves. A slower rate of decline would matter more than any single quarter's margin. Progress on the Oak Tree arrangement, which values HPC at roughly six times trailing EBITDA and sets it up as a standalone vehicle, could shift attention toward eventual separation options.
Cost pressures are the other swing factor. Management flagged higher fuel and freight costs tied to Middle East conflict, along with the risk of renewed trade-policy volatility over the summer. Gross margin will show whether the earlier tariff mitigation, which cut gross exposure from about $450 million to $70 million to $80 million, is holding up against new inflation.
Sentiment has soured, with bearish readings climbing to 50% from 34.5% heading into the last report. The stock, at about $85, sits above its 200-day moving average of roughly $80.64 but well below its post-report high near $99, closer to the bottom of its range. That leaves room for relief if the year ends cleanly. What matters most is the fiscal 2027 outlook. If management can project continued EBITDA growth from pet and garden despite a shrinking HPC and higher input costs, the recovery narrative stays intact. A cautious or vague guide would suggest the market's skepticism was justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 |
Empower Brands Makes Unsolicited Bid to Buy Helen of Troy for $1.6 Billion
SPB +7.72%
The Wall Street Journal
|
| Nov-04 | |
| Oct-29 | |
| Oct-15 | |
| Aug-27 | |
| Aug-10 | |
| Aug-07 | |
| Aug-07 | |
| Aug-07 | |
| Aug-05 | |
| May-20 | |
| May-07 |
