EagleRock Misses On EPS, But Raised Guidance And A Capital-Free Acreage Dedication Shift The Story Toward 2027
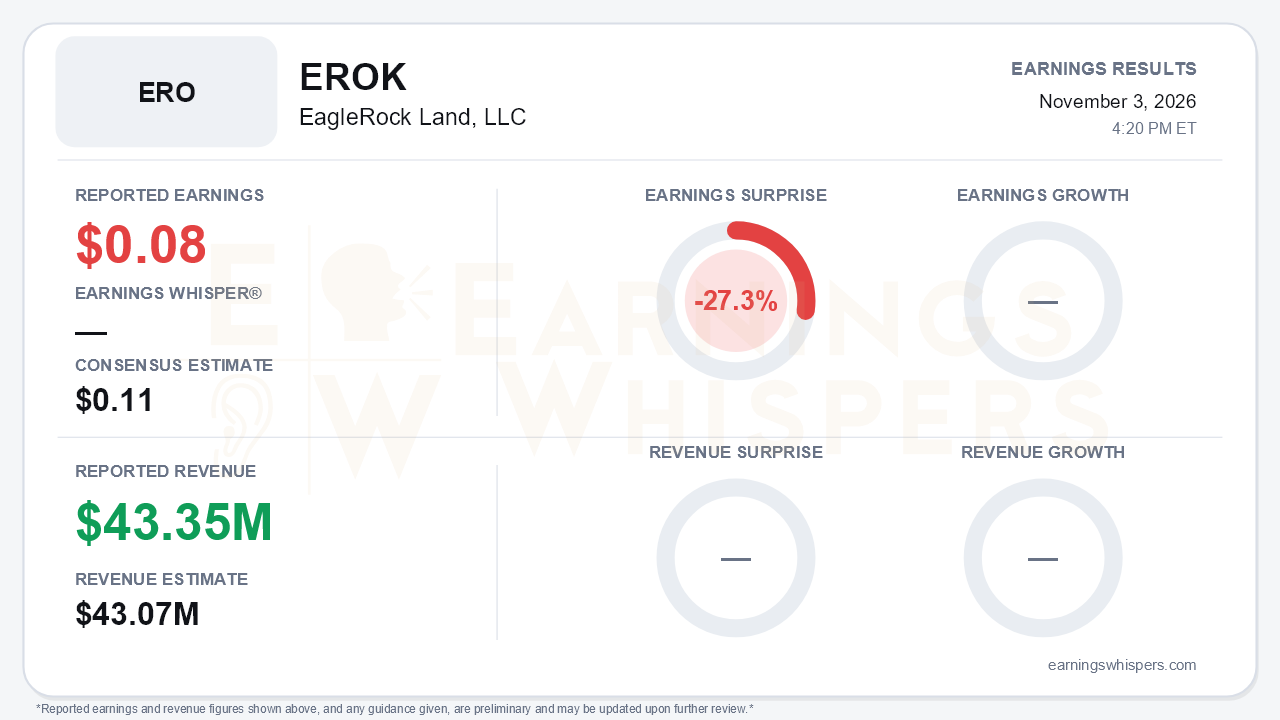
EagleRock Land (NYSE: EROK) reported third-quarter earnings of $0.08 per share, 27.3% below the $0.11 consensus. Revenue of $43.35 million came in 0.6% above the $43.07 million estimate. On its face this was an earnings miss, but it was not an operating miss. Revenue landed on target, Adjusted EBITDA margin expanded, free cash flow jumped, and management raised full-year Adjusted EBITDA guidance for the second straight quarter. The central tension is that the newly public company's GAAP per-share line is heavily diluted by acquisition accounting and its share structure, while the cash-generating engine is improving. Investors, judging by the stock, have not been rewarding that distinction.
The quality of the miss deserves context. Depreciation and amortization climbed to $15.9 million from $10.3 million in the second quarter, reflecting a balance sheet that now carries $711 million of intangibles and $643 million of goodwill. Share-based compensation added another $5.6 million of expense. Net income of $11.3 million was a clean swing from the second quarter's $37.5 million loss, which had been distorted by $57.4 million of IPO-related stock compensation. However, only $2.1 million of that profit was attributable to Class A holders, with the rest flowing to the noncontrolling interest. Year-over-year comparisons are not meaningful because of the predecessor structure. This is the first quarter reported fully on an as-reported basis, which also limits strict comparisons with the normalized second-quarter figures.
Sequentially, the headline numbers softened. Revenue fell to $43.3 million from $46.8 million on a normalized basis, and Adjusted EBITDA slipped to $34.0 million from $36.2 million. The culprit was resource sales, which nearly halved to $12.7 million from $24.2 million. Management attributed the drop to lumpy drilling and completion activity and expects a rebound in the fourth quarter. What changed beneath the surface was the mix:
- Surface use revenue rose to $11.3 million from $7.1 million.
- Surface use royalties grew to $19.4 million from $15.5 million and now account for 45% of revenue.
Because these streams carry little or no cost of sales, Adjusted EBITDA margin improved to 78.5% from 77.5% normalized. Free cash flow reached $31.8 million, a 93% conversion rate, up from $22.4 million in the second quarter. Capital expenditures were just $1.1 million.
The forward story is where management's tone turned noticeably more assertive. Full-year guidance moved to $133 million to $137 million, a $135 million midpoint versus $131 million previously. Roughly $2 million of the raise is organic and $2 million comes from the Intrepid Ranch acquisition. The Double Eagle V dedication of roughly 35,000 acres lifts Double Eagle-dedicated acreage to more than 100,000 acres. It requires no capital and carries 100% margin, with revenue beginning in 2027. The CFO called it among the most important announcements since the IPO and said 2027 consensus EBITDA looks conservative. Other new or expanding revenue streams include:
- two Midland bolt-ons acquired for $15.4 million at under 10x EBITDA;
- a sand mine lease on Intrepid Ranch;
- a first acid gas injection (AGI) agreement signed the morning of the call;
- pore space agreements in late-stage negotiation;
- progress on behind-the-meter power.
The call shifted from describing a pipeline of opportunities to announcing completed deals.
Bears still have legitimate ammunition. Fourth-quarter EBITDA margin is guided to 73% to 75%, below the third quarter's 78.5%, which suggests a resource-sales recovery would bring lower-margin dollars back into the mix. The Double Eagle V contribution remains unquantified and depends on the partner's 2027 drilling cadence. An analyst noted no material acceleration in activity from public operators. The Texas election, including a Democrat winning a Railroad Commission seat, adds regulatory uncertainty around produced water and land use. The balance sheet has also changed. Cash fell from $61.8 million at the second quarter to $12.3 million, and $70 million is now drawn on the revolver. Net leverage of 0.4x remains modest, and management plans roughly $10 million per month of debt reduction.
The market setup has been unforgiving. Shares opened at $24.00 after the August report and now trade at $19.15, down 20.2%. That leaves the stock about 13.5% below its $22.13 200-day moving average, and the AVWAP trend reading is negative. Investor sentiment deteriorated sharply into the report. One caveat: the supplied current reading of -2.11 falls outside the stated -1 to +1 scale, so its exact magnitude should be treated cautiously. The direction, from a modestly negative -0.21, is clearly more bearish.
The bottom line is that EagleRock's EPS miss reflects accounting and capital structure more than business weakness. Cash flow, margins, and guidance all moved in the right direction, and the Double Eagle V dedication gives the 2027 growth narrative real substance. The burden now falls on a fourth-quarter rebound in resource sales and on quantifying the new dedication. Until then, a skeptical market that has marked the stock down sharply since August is unlikely to give full credit for growth that is largely promised rather than delivered.
Read our earnings preview for EagleRock Land, LLC: https://www.earningswhispers.com/article/EROK/21569
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-23 | |
| Aug-31 | |
| Aug-12 | |
| Aug-10 | |
| Aug-10 | |
| Aug-09 | |
| Jul-31 | |
| Jul-28 | |
| May-18 | |
| May-14 |
