Standard Nuclear Must Show Revenue Is Scaling Faster Than Losses As Shares Slip
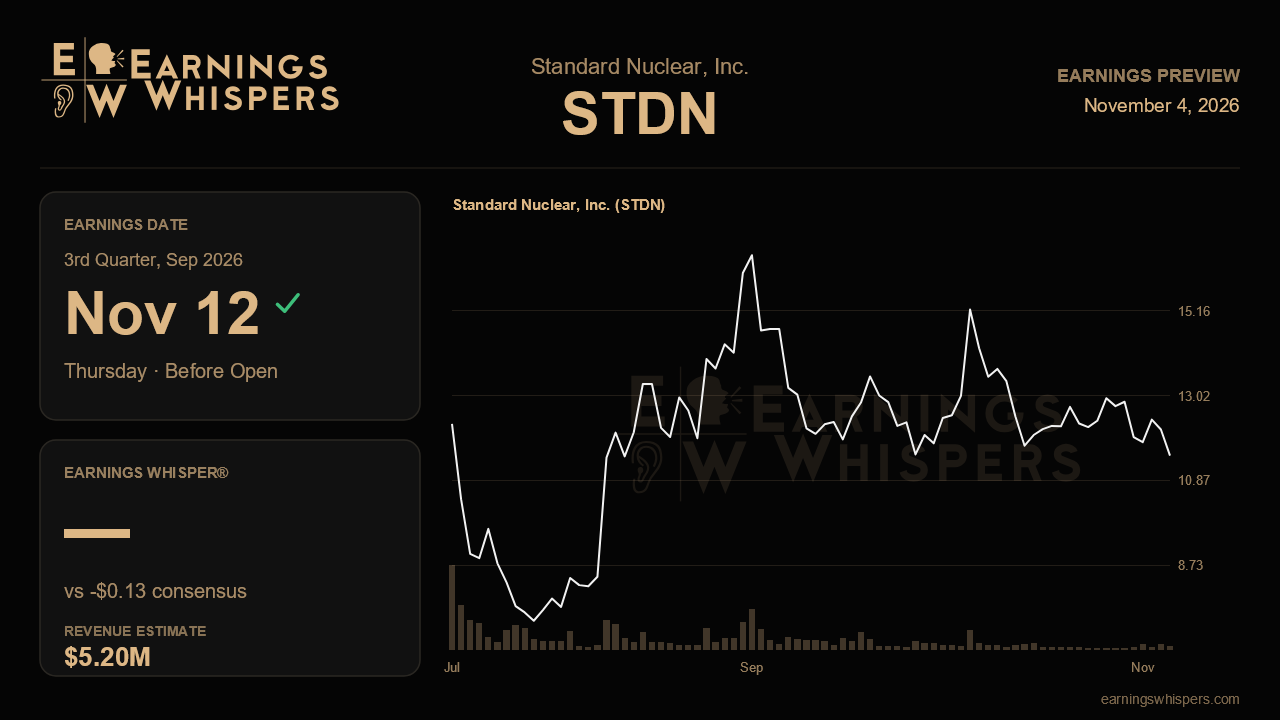
Standard Nuclear heads into its September-quarter report with a simple but demanding question hanging over it: can a company whose stated mission is delivering the building blocks of nuclear power at scale start showing that scale in its financial statements? Wall Street is looking for modest progress on the top line paired with slightly deeper losses. Since the last report, the stock has drifted lower, which suggests the market wants harder evidence before paying up for the long-term story.
The consensus calls for a loss of 13 cents a share on revenue of about $5.2 million. Last quarter the company lost 12 cents a share on $4.7 million in revenue, so analysts are modeling sequential revenue growth of roughly 10% alongside a marginally wider loss. That combination is the crux of the setup. For an early-stage nuclear supplier, red ink is expected. What matters is the direction of travel. If revenue grows while per-share losses hold roughly steady, the company is showing early operating leverage. If losses widen faster than sales, investors may conclude the path to scale will be longer and more capital intensive than hoped.
There is no formal guidance or detailed prior commentary to anchor the comparison, which makes the release itself and the accompanying discussion more important than usual. Without a management range to measure against, the quarter will be judged on whether the business is building visible momentum. Investors will want to see whether revenue growth reflects repeatable demand rather than one-off items, how quickly spending is rising to support expansion, and whether the company can articulate concrete milestones that tie today's small revenue base to the large opportunity implied by its mission. Commentary on cash usage and funding needs will likely matter as much as the headline loss, since capital is the lifeblood of any company trying to industrialize nuclear supply.
Sentiment has improved, if only slightly. Bullish readings rose to 8.1% from 4.7% ahead of the prior report, a sign that the tone around the stock has warmed a touch even as the price has not. Shares have fallen 10.3% since the last earnings release, trailing the S&P 500 by about 8.5 percentage points over a stretch when the broader market slipped just 1.8%. That underperformance means the market is not braced for a blowout, which could make a clean quarter more impactful. It also signals limited patience for disappointment.
The chart reinforces that caution. At $12.41, the stock sits near the bottom of its post-earnings range of $11.25 to $17.34, roughly 28% below the high and only about 10% above the low. It remains a bit less than 4% above its 200-day moving average of $11.94, a level that has so far acted as a floor. A weak report could put that support and the range low in play, while an encouraging one would need to carry the shares well higher before any talk of a breakout makes sense.
Ultimately, this report comes down to whether Standard Nuclear can demonstrate that growth is outrunning the cost of achieving it. Hitting the $5.2 million revenue mark while keeping the loss near last quarter's level would support the case that the business is beginning to scale. Falling short on sales or posting a sharply wider loss would reinforce the skepticism already reflected in the stock's recent slide.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 8 hours | |
| Nov-04 | |
| Nov-02 | |
| Oct-29 | |
| Aug-27 | |
| Aug-26 | |
| Aug-20 | |
| Aug-17 | |
| Aug-14 | |
| Aug-12 | |
| Aug-10 | |
| Jul-31 | |
| Jul-22 | |
| Jul-17 |
