X-Energy's Stock Has Halved; Q3 Must Show The Promised 1GW Utility Deal And TX1 Milestone
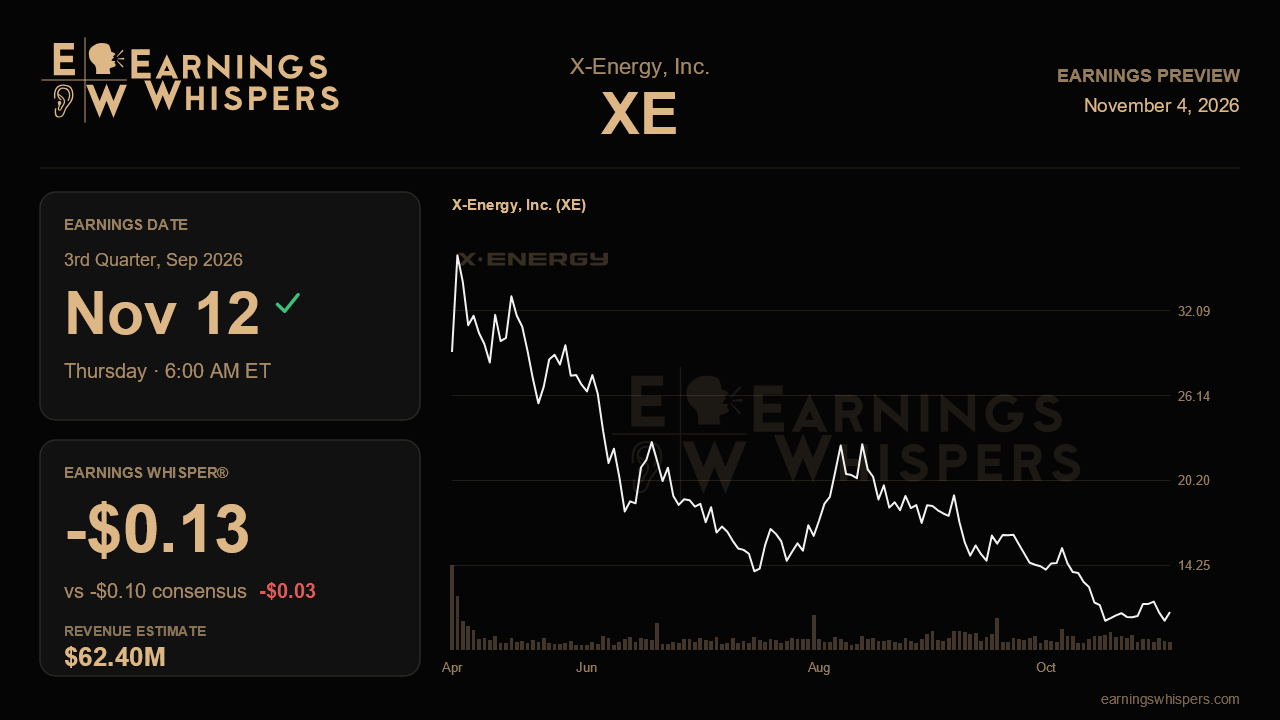
Few companies head into an earnings report with a better story and a worse chart than X-Energy. Last quarter management raised its confidence on nearly every front: up to an additional $1 billion in Department of Energy funding, binding fuel supply agreements, and a new gigawatt-scale utility customer it described as nearly finalized. The market answered by cutting the stock roughly in half. The third-quarter report, due before the open on November 12, is the first real chance to show whether those catalysts are turning into signed deals and finished milestones, or whether the sell-off was right to doubt them.
The Street expects a loss of $0.10 a share on revenue of about $62.4 million. That revenue figure would be up about 14% from the $54.6 million in total revenue and grant income reported last quarter, which itself was up 154% from a year earlier. For a pre-commercial reactor developer, that line mostly reflects Advanced Reactor Demonstration Program cost-share activity, so it works more as a gauge of construction and engineering pace than of customer demand. The Earnings Whisper sits a bit lower at a loss of $0.13, hinting that some investors expect costs to run ahead of the consensus model. Either estimate would narrow the second quarter's $0.15 loss, but that improvement is partly mechanical. Last quarter carried a $33.5 million non-cash IPO equity compensation charge and a $5.6 million warrant loss, and the warrant has since been exercised. A narrower loss is therefore expected. The real question is whether underlying spending keeps climbing.
That makes cash burn the number to watch. Operating cash use jumped to $97.3 million in the second quarter from $67.3 million in the first, driven by heavier ARDP work, hiring and prepayments to long-lead vendors. With about $1.9 billion in cash and investments and no debt, X-Energy is not under balance sheet pressure. Still, another big step up without a matching rise in ARDP reimbursements, which reached $547 million cumulatively at the end of June, would feed the worry that the company is paying for growth faster than its government partner is reimbursing it. Clear details on the full ARDP cost-share requirement, which management has not yet disclosed, would help settle that question.
On operations, the clearest test is the TX1 facility. Vertical construction was about 80% complete in June, up from 56% three months earlier, and management said it was on track for a third-quarter milestone. Confirming that milestone was hit would support the execution story. The bigger swing factor is the next 1GW project with a major investor-owned utility. Management moved from a general promise of an announcement sometime in 2026 to saying talks were in their final stages. If that deal is still unsigned in November, the gap between tone and results will be hard to ignore. Any added clarity on the confidential HALEU agreements with Centrus and General Matter, such as timing or volumes, would also help, as would reassurance that the Dow construction permit remains on schedule for early 2027.
Expectations have clearly soured. Sentiment has moved to 30% bearish from 18.5% bearish before the last report. The stock has fallen 52.5% since then, against a 2.7% dip in the S&P 500. At $10.98 it trades far below its 200-day moving average of $19.28 and sits close to the $10.04 low of its post-earnings range, a long way from the $23.99 peak. That much damage means the market is no longer pricing in management's optimism, which lowers the bar for a positive surprise if the company delivers concrete news.
In the end, this report comes down to conversion. Last quarter's call was a list of promises: more federal money, secured fuel, an imminent anchor customer. Investors now need evidence that those promises are becoming contracts and completed construction, at a cash burn rate the balance sheet can carry comfortably. A signed utility deal and a confirmed TX1 milestone would go a long way toward restoring the narrative. Another quarter of rising spending without them would suggest the stock's slide reflected more than impatience.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-06 | |
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Oct-30 | |
| Oct-30 | |
| Oct-22 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-19 | |
| Oct-19 |
