Omega Healthcare Edges Consensus But Misses The Whisper, While A $946 Million Deployment Surge Drives A Larger Guidance Raise
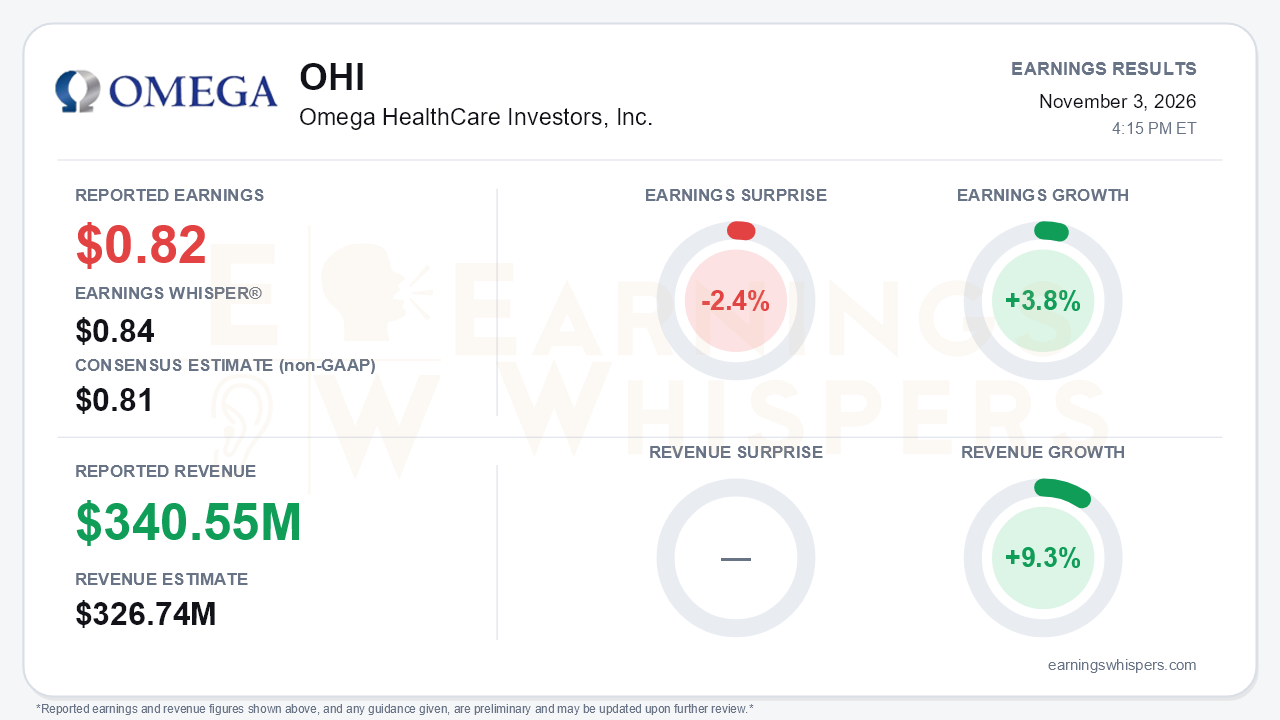
Omega Healthcare Investors (NYSE: OHI) reported third-quarter adjusted FFO of $0.82 per share. That was a penny above the $0.81 consensus but short of the $0.84 Earnings Whisper number, a 2.4% shortfall against the bar investors were actually watching. Revenue of $340.55 million beat the $326.74 million consensus by 4.2% and grew 9.3% year over year. Per-share earnings grew a more modest 3.8%. That is the central tension: the quarter was not a growth acceleration, but the guidance raise and the post-quarter capital deployment matter more than the penny of upside. Omega raised full-year AFFO guidance to $3.28-$3.30 from $3.22-$3.26. The five-cent midpoint increase is its largest raise of the year, after two-cent increases in each of the prior two updates.
The quality of the quarter deserves scrutiny on two fronts.
First, the revenue beat is partly structural rather than organic. The shift toward RIDEA operating structures brought in $30.8 million of resident fees and services that did not exist a year ago. Those fees come with $25.6 million of senior housing operating expenses inside property-level costs, so the gross revenue line flatters underlying growth. Rental income actually fell to $252.8 million from $260.7 million. NOI is the cleaner measure, and it rose about 7% to $332 million.
Second, per-share growth is being diluted. Diluted share count climbed to 321 million from 308 million, helped by 4.7 million shares issued in the quarter at an average $49.44.
On a GAAP basis the picture looks far weaker. Net income fell to $0.27 per diluted share from $0.59, and Nareit FFO dropped to $0.60 from $0.78. The main drivers were:
- $59.9 million of acquisition and transition costs, mostly the lease-termination payments tied to converting 30 U.K. care homes to RIDEA;
- $18.8 million of severance;
- an $11.4 million impairment;
- the absence of last year's $28.3 million gain on asset sales.
These are largely discrete items. Still, investors should recognize that portfolio repositioning is front-loading real cash costs.
Sequentially, AFFO slipped a penny from $0.83. The call attributed the dip to roughly $8.8 million of lost earnings from second-quarter asset sales and loan repayments. That drag explains why management leaned so heavily on deployment. Capital investment, flagged last quarter as set to pick up in the second half, arrived at scale:
- $182 million in the quarter;
- $946 million after quarter-end, anchored by an $846 million U.K. mortgage loan on the Runwood portfolio at 8.72%, stepping to 8.94% in year two;
- about $1.5 billion year to date, versus $470 million at the second-quarter call.
Management also completed two high-return portfolio moves. Transitioning 32 Florida SNFs to PACS adds $26.1 million of annual rent in exchange for a $90 million termination fee. The U.K. RIDEA conversions generate roughly a 26% yield on incremental cash flow, according to the call.
The credit backdrop keeps improving, which underpins the confidence in management's tone:
- The Genesis overhang is resolved. NewGen assumed the lease at full contractual rent of $13.3 million per quarter, and Omega received $149.5 million in DIP and term-loan repayments.
- Trailing operator EBITDAR coverage rose to 1.67x from 1.55x a year earlier, and occupancy edged up to 82.7%.
- Maplewood's DC occupancy rose to 78% from 66%.
- Leverage fell to 3.1x, which CEO Matthew Gourmand called the lowest in company history, and the leverage target was lowered to under 4x.
Bears still have legitimate ammunition. Management acknowledged more aggressive cap rates in U.K. care homes and U.S. senior housing, and Runwood was entered at a lower initial yield than historical deals. U.S. SNF deal flow remains very competitive. The loan book will swell until the Runwood purchase option can be exercised. That deal was funded partly on the revolver, and a $700 million bond due April 2027 will likely be refinanced through a term loan and ATM issuance given unattractive bond pricing. Regulatory risk is also rising, including renewed Democratic focus on long-term care quality and possible PDPM recalibration. Management characterized the near-term risk as limited but is watching the longer term.
The market setup is more muted than the guidance raise implies. Shares have fallen 9.3% since the open following the July report, from $52.39 to $47.53. They now sit just 1.9% above the 200-day moving average of $46.63, meaning the stock has de-rated even as estimates moved higher. Investor sentiment was essentially unchanged, edging to 0.0996 from 0.0948, and remains only mildly positive. The Earnings Whispers trend readings are largely positive on sequential growth and momentum, while the price trend remains negative. That split reflects fundamentals improving faster than the stock price.
The bottom line is that Omega delivered a quarter that disappointed the whisper but materially strengthened its forward earnings base. The beat was modest, the headline revenue growth is inflated by the RIDEA gross-up, and share issuance continues to cap per-share growth. Against that, Genesis is behind it, coverage and leverage are at multi-year bests, and roughly $1 billion of new capital is now earning high-single-digit or better returns. The key question for investors is whether management can keep deploying capital accretively as cap rates tighten. Thinner initial yields on deals like Runwood make that harder, and the coming debt refinancing will test whether Omega's balance-sheet advantage holds.
Read our earnings preview for Omega HealthCare Investors, Inc.: https://www.earningswhispers.com/article/OHI/21605
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-26 | |
| Oct-12 | |
| Oct-12 | |
| Oct-05 | |
| Sep-18 | |
| Sep-02 | |
| Sep-01 | |
| Aug-14 | |
| Aug-03 | |
| Jul-30 | |
| Jul-29 |
