HeartBeam's Promised Commercial Metrics Face Their Test As Cash Thins And Stock Sinks
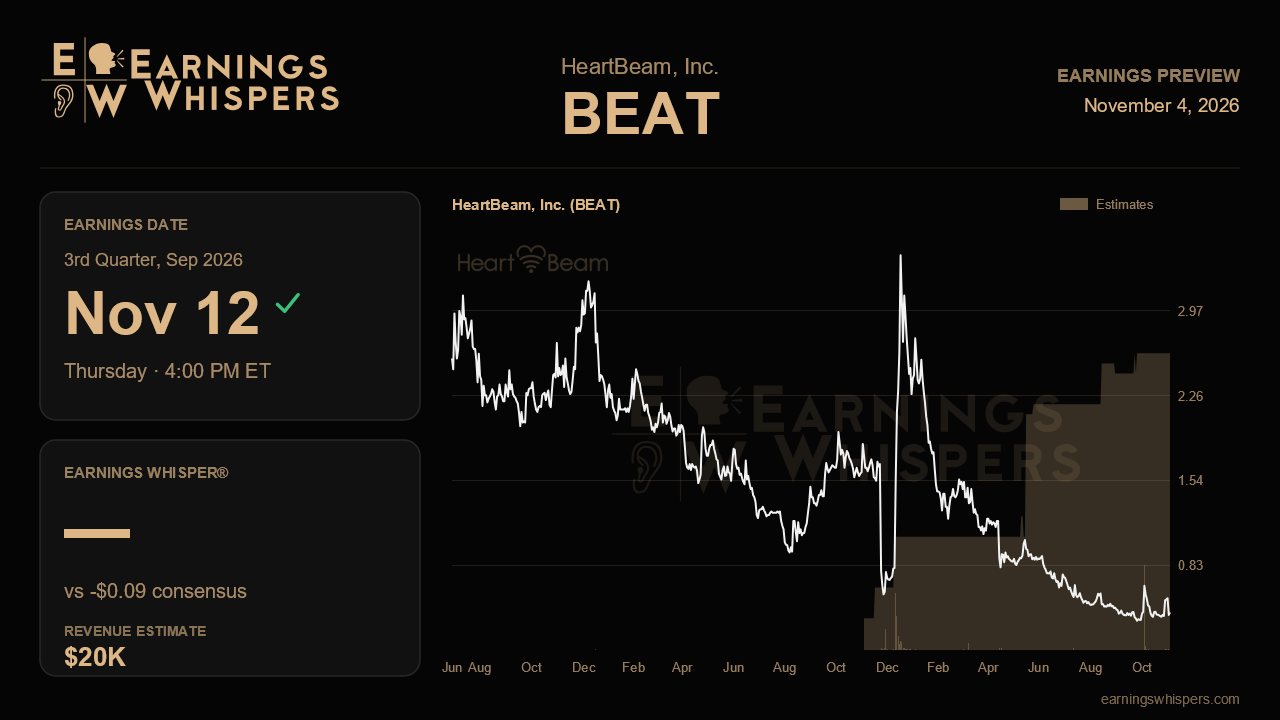
HeartBeam enters its third-quarter report with an IOU coming due. Last quarter, management asked investors to be patient on commercial disclosure, saying contracts covered patients in the thousands and that harder metrics would arrive in the third or fourth quarter. With the stock down more than 20% since that call, a new leader at the helm and cash reserves shrinking, this is the report where the company needs to start showing its work.
The headline numbers matter less than usual. Consensus calls for a loss of 9 cents a share, an improvement from 15 cents a year ago and roughly in line with the 10-cent loss posted last quarter. That 40% year-over-year improvement reflects tighter spending rather than any commercial breakthrough. Revenue expectations of about $20,000 are a rounding error for a company that once sketched out $750,000 to $1 million in potential revenue per account. Management has given no formal revenue guidance, so the meaningful yardsticks are the ones it set itself on cash burn and disclosure.
On spending, the trend has been encouraging. Full-year operating cash outflow guidance has fallen from $17 million to $19 million at the start of the year, to under $16 million, and most recently to under $14 million, with fourth-quarter baseline burn targeted below $2.5 million. Second-quarter cash use was $3.3 million. Three consecutive reductions raise the bar: the company now needs a third-quarter figure that clearly bends toward that baseline, despite lingering severance and transition costs from the departure of chief executive Rob Eno. Cash stood at $8.8 million at the end of June, down from roughly $12.4 million pro forma after the April raise. Any sign that the pivotal heart attack detection trial is pulling spending above plan sooner than expected, or that the runway into 2027 is shortening, would undercut the main improvement story of the past year.
The clinical narrative is where HeartBeam has been strongest. The company filed an FDA pre-submission for heart attack detection under the 510(k) pathway in mid-August, which places the agency's typical 75-day response window close to this report. Management also suggested the pivotal study could begin before year-end, and the Align ACS pilot was slated for full presentation at TCT. Validation would mean confirmation that FDA feedback arrived and supports the 510(k) route, a firm pivotal start date, and evidence that Head Start ACS, already past half enrollment, is near completion. Vagueness on FDA feedback or a slip in the pivotal timeline would be a notable setback, since regulatory momentum is the clearest thing the new team inherited.
Commercially, the bar is simple: numbers. First orders shipped last quarter across New York, Dallas, South Florida and Southern California, and hospital network pilots were introduced, including one system with about 50 million annual visits. Investors deserve an enrolled patient count, early subscription revenue and progress on the patch pilot. Executive Chairman Richard Ferrari has already tempered earlier messaging, calling the data licensing angle an overstatement. Another quarter of deferral would suggest the earlier per-account modeling was aspirational.
The market has priced in considerable doubt. At 43 cents, shares sit at half their 200-day moving average of 85 cents and near the bottom of a post-earnings range that stretched from 36 to 95 cents, well below the prior quarter's 48-cent low. Sentiment has moved from deeply bearish before the last report to roughly neutral, a modest thaw rather than conviction. That low bar cuts both ways. Concrete FDA progress paired with real patient numbers could reframe the story, but the central question is whether HeartBeam can prove that commercial traction exists before its shrinking cash forces the issue.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-02 | |
| Oct-28 | |
| Oct-26 | |
| Oct-21 | |
| Oct-15 | |
| Oct-05 | |
| Oct-05 | |
| Sep-21 | |
| Aug-14 | |
| Aug-13 | |
| Aug-12 | |
| Jul-30 | |
| Jul-14 |
