Arrowhead Must Show Redemplo Traction And SHTG Filing Progress After 32% Slide
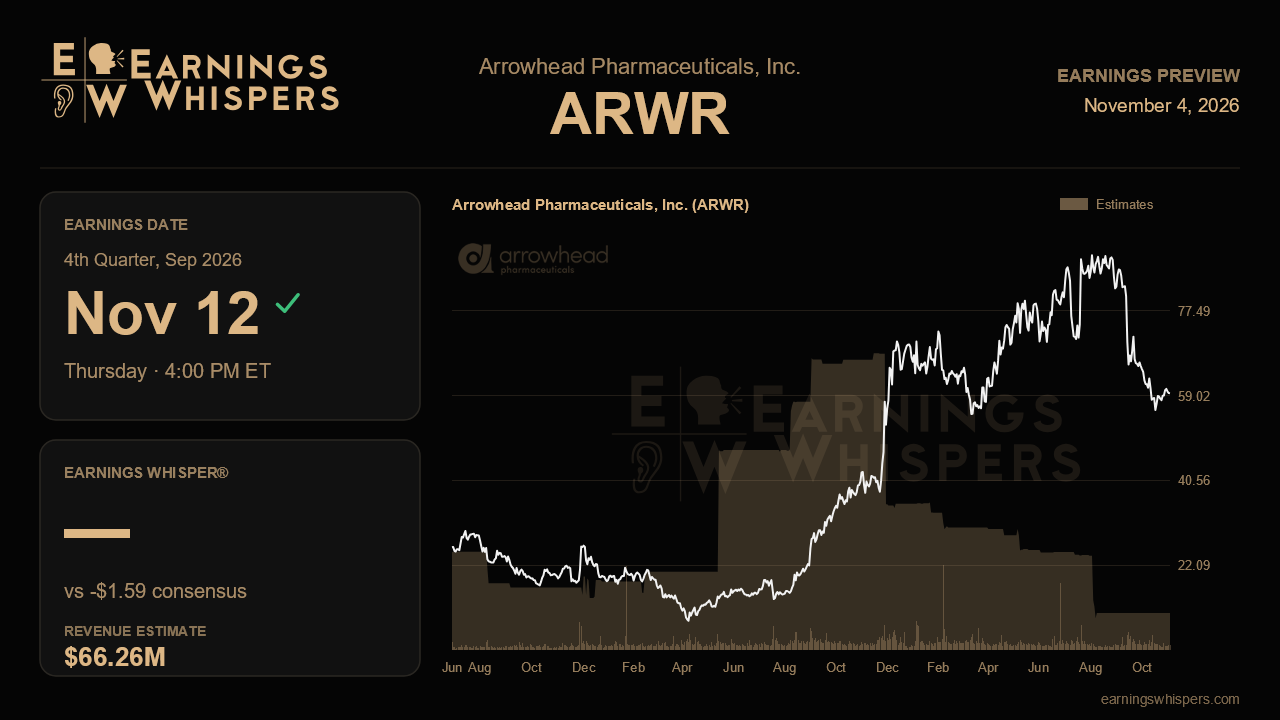
Arrowhead Pharmaceuticals heads into its fiscal fourth-quarter report with an awkward contradiction to explain. Three months ago, management delivered its most confident call in years: a positive Phase III readout in severe hypertriglyceridemia, a $215 million priority review voucher to speed the filing, and accelerating prescriptions for Redemplo in its first approved indication. Since then the stock has fallen 32%, trailing the S&P 500 by roughly 29 percentage points. The report due after the close on November 12 is less about the quarter's numbers than about whether the company can rebuild confidence in a story the market has clearly marked down.
The numbers themselves are expected to look rough, and that is largely by design. Consensus calls for a loss of $1.59 per share on revenue of $66.3 million, compared with a loss of $1.36 on $75.3 million last quarter. Against the year-ago period, when revenue reached $256.5 million and the loss was just $0.18 per share, the expected 74% revenue decline and sharply deeper loss look alarming. But Arrowhead's top line is still dominated by lumpy partnership payments, and last quarter's figure was flattered by the full $25 million Madrigal upfront for its PNPLA3 program. Without formal guidance to anchor against, the headline revenue figure matters less than its composition. The rising loss reflects deliberate spending, with research and development near $198 million and SG&A around $47 million last quarter as the company builds commercial and manufacturing scale.
The commercial line deserves the closest look. Redemplo's weekly prescriptions more than doubled sequentially last quarter from a run rate near 30, supported by more than 400 prescribers, and derived product revenue climbed from about $1 million to roughly $2.4 million. Management said that momentum continued into the current quarter. Another clear step up, along with early contributions from the newly approved EU and Australian markets, would validate the argument that the familial chylomicronemia launch is building a foundation for the much larger SHTG opportunity. A flattening in scripts would invite harder questions about Arrowhead's ability to compete with Ionis, whose Tringolza has a first-mover position and a lower price point than Redemplo's roughly $45,000 list price.
The regulatory timeline is the second test. Management said the supplemental filing for SHTG remains on track before the end of 2026, and the voucher is meant to compress review to six months, setting up a potential launch in the second quarter of 2027. Any slippage would undercut the rationale for spending $215 million on a voucher. Investors should also look for fuller detail on the Shasta 3/4 data, which was under embargo at the time of the last call. Open questions about mean versus median triglyceride reductions and possible imbalances in liver fat, ALP or glucose measures may help explain the stock's retreat, and a clean accounting of the safety profile would go a long way toward settling them.
The pipeline adds a third layer. First clinical readouts for the Aerodimer PA program and the brain-penetrant AeroMapT platform were slated for September, and the INHBE obesity program was heading toward Phase 2b. Commentary on those results, plus progress toward 23 clinical candidates by year end, will shape how much value the market assigns beyond Redemplo.
Sentiment has warmed noticeably, with bullish readings rising to about 40% from roughly 15% before the prior report, even as the shares slipped well below their 200-day moving average near $72. At $59.53, the stock sits just above its post-earnings low of $55.83, far from the $91 high. That positioning leaves room for relief if execution is clean, but little cushion if it is not. The central question is whether Arrowhead can show that prescriptions are compounding, the SHTG filing is on schedule and the full data hold up, because those three points are what justify the heavy spending behind its $3 billion to $4 billion peak-sales ambitions.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-07 | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Nov-02 | |
| Oct-28 | |
| Oct-27 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-11 | |
| Oct-07 | |
| Sep-29 | |
| Sep-24 |
