MSG Entertainment's Harry Styles-Fueled Quarter Crushes Estimates, But Back-Half Pacing Keeps The Debate Alive
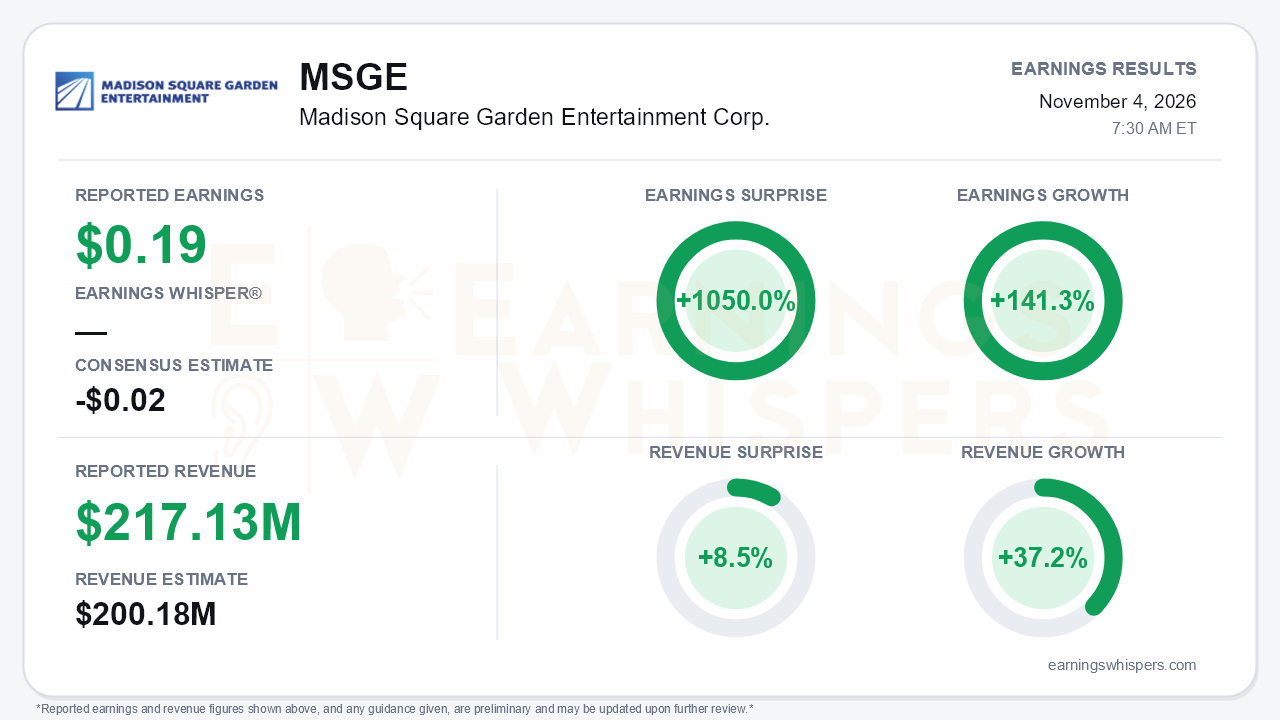
Madison Square Garden Entertainment opened fiscal 2027 with a result that was hard to argue with. The company earned $0.19 per share against a consensus estimate calling for a $0.02 loss, a 1050.0% surprise, and swung from a $0.46 loss a year ago, which works out to earnings growth of 141.3%. Revenue of $217.13 million beat the $200.18 million consensus by 8.5% and grew 37.2% year over year. The growth is accelerating: revenue rose 14% in the year-ago quarter and 27% in the fiscal fourth quarter. The central tension is that much of this strength came from an unusually concert-heavy quarter at The Garden, including 16 of Harry Styles' 30 residency nights. Management's commentary about the back half of the year was more mixed than the headline suggests.
The operating improvement is real, but the GAAP earnings beat deserves some scrutiny. Adjusted operating income, a non-GAAP measure, rose to $34.3 million from $7.1 million a year ago and $18.6 million last quarter. That reflects genuine operating leverage. Total direct operating expenses grew about 24% against 37% revenue growth. Food, beverage and merchandise revenue jumped 56% on double-digit per-cap gains. GAAP operating income of $9.7 million also benefited from the absence of a $13.8 million impairment recorded a year earlier. Below the operating line, the picture is thinner. Pretax income was just $2.3 million, and a $6.6 million income tax benefit carried net income to $8.9 million. In other words, the per-share figure that drove the outsized surprise rests largely on a tax benefit rather than on pretax profit. SG&A rose 18%, mostly on compensation. Operating cash flow was negative $26.2 million versus positive $19.8 million a year ago, and cash fell to $194 million from $294 million. Management attributed the decline to the reversal of cash held for promoters, which is a seasonal timing item rather than an operating deterioration.
The call was more constructive than the release. The CFO said the bookings financial outlook is stronger than it was in August. Garden concert bookings for fiscal 2027 have slightly exceeded the company's goal, up from roughly 90% in August, and the full portfolio is more than 80% booked. Concert sell-through for the next two quarters is pacing ahead of last year, a step up from the 'in line' language of a year ago. Suite renewals exceed 95%. Management's framing also escalated, from 'solid growth' in August to 'robust growth in revenue and adjusted operating income.' Formal guidance, however, remains qualitative.
The Christmas Spectacular is the next major catalyst. Shows are scheduled at 231, up from 230 put on sale in August and 215 last year. Advance ticket revenue is pacing up, and more than 1.2 million guests are expected. Other potential catalysts include:
- the Rangers spinoff from the Knicks, completed with the arena license agreements unaffected;
- a possible Infosys Theater transfer, whose proceeds could be reinvested in a domestic venue, though the deal remains non-binding.
Bears have legitimate ammunition, though. Garden concerts are pacing down in the second half of fiscal 2027, which management characterizes as timing. Theater concerts are expected to decline in the December quarter. Family and performing arts shows are now expected to be fewer, a softer stance than August's suggestion that Cirque's absence would be largely offset. Management also declined to quantify how incremental the Styles residency was, which leaves a difficult fiscal 2028 comparison undefined. Balance-sheet flexibility is improving, with debt down to about $571 million from $622 million a year ago, while buybacks continued with another $25 million repurchased. Book equity is now only $11.9 million, however.
The market setup is more complicated than the surprise implies. Investor sentiment slipped from slightly positive (0.0254) to modestly negative (-0.1855) heading into the report, a meaningful shift toward skepticism rather than a collapse. Price action tells a similar story. Shares spiked to a 52-week high of $90.41 the day after the August report and then gave much of it back. At $79.50, the stock was down 3.8% from the post-August opening and 12.1% below that high, though 5.5% above the September low and still 12.5% above its 200-day moving average. Momentum and AVWAP trend readings remain positive while the price trend is neutral. That combination is consistent with a stock that has cooled off without breaking down.
The bottom line is that MSG Entertainment delivered an accelerating, margin-expanding quarter and raised the tone of its bookings commentary. Even so, the GAAP beat leaned on a tax benefit, and the quarter was flattered by a marquee residency that will not recur. With the Christmas Spectacular set up favorably, the near term looks solid. The real test is whether second-half Garden pacing, theater softness and the eventual Styles comparison prove to be timing noise or the leading edge of normalization, a question that the souring of pre-report sentiment suggests investors are already asking.
Read our earnings preview for Madison Square Garden Entertainment Corp.: https://www.earningswhispers.com/article/MSGE/22443
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-01 | |
| Oct-29 | |
| Sep-30 | |
| Sep-23 | |
| Sep-21 | |
| Sep-21 | |
| Aug-17 | |
| Aug-14 | |
| Aug-14 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 |
