Flowers Foods Faces A Volume Test As Guidance Leans On Unproven Fourth-Quarter Recovery
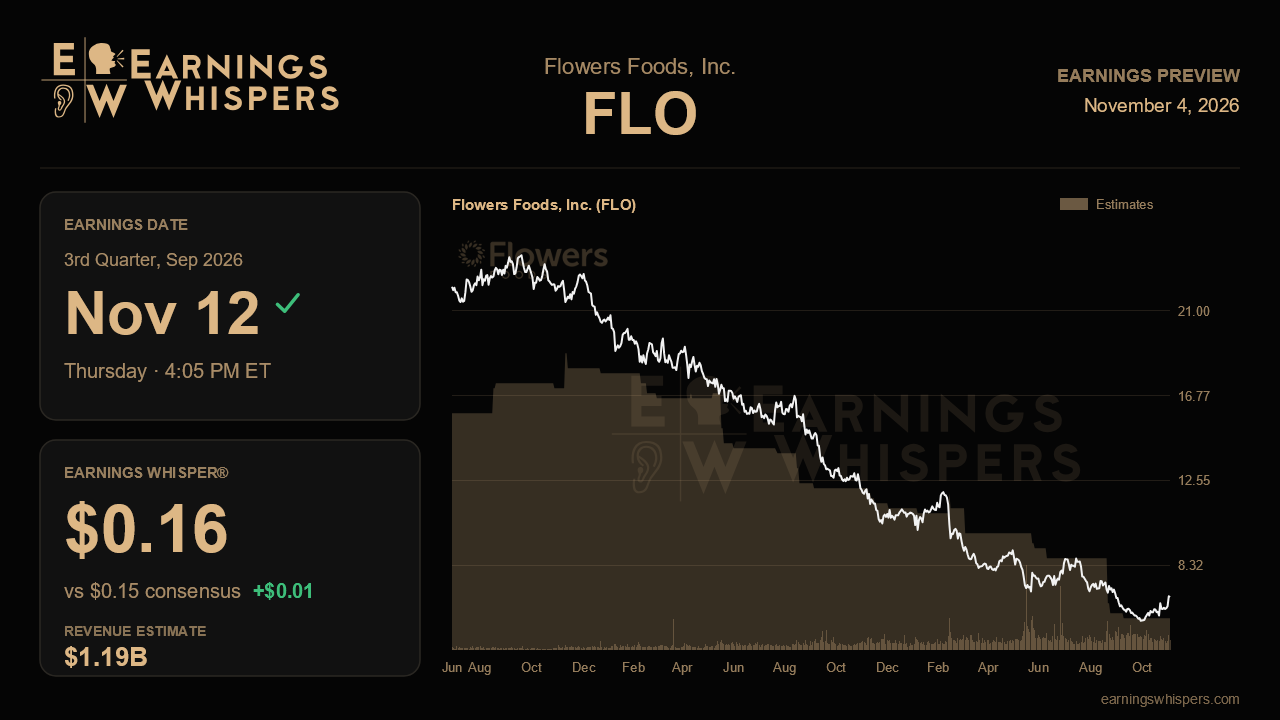
Flowers Foods heads into its third-quarter report with a credibility problem more than a numbers problem. Management already told investors this quarter would decline from a year ago, so a weak print is not the surprise. The real question is whether anything in these results suggests the self-help story built around new business wins, a relaunched Nature's Own brand and a fresh innovation pipeline is beginning to show up in volumes, or whether the bakery is still losing ground faster than it can cut costs.
The Street expects earnings of $0.15 per share on revenue of about $1.19 billion. That compares with $0.23 and $1.23 billion in the same quarter last year, implying a roughly 35% drop in profit on a 3% revenue decline. That gap is the story in miniature: modest sales erosion is translating into outsized earnings damage because lower volumes leave fixed plant and distribution costs spread over fewer loaves. The Earnings Whisper sits at $0.16, a penny above consensus, which hints that some traders see room for a small beat, but the difference is too slim to signal real optimism.
Guidance adds an awkward wrinkle. Flowers cut its 2026 outlook to $0.75 to $0.85 per share on revenue of $5.070 billion to $5.142 billion, down from $0.80 to $0.90 and $5.163 billion to $5.267 billion. Full-year consensus of $0.85 sits at the very top of the new earnings range, and the $5.17 billion revenue estimate is actually above management's revised ceiling. Either some estimates have not fully caught up to the cut, or analysts are leaning hard on the promised fourth-quarter stabilization. Any hint that the company is gravitating toward the middle or low end of its range would likely pull those figures down.
The operating details matter more than the headline. Fresh bread volume fell 9.5% in the second quarter, the weakest figure the company has disclosed in this stretch, and management conceded that consumer preferences for sourdough, protein and half-loaf formats moved faster than its product pipeline. Competitors also declined to follow Flowers' late-2025 price increases, while promotional intensity rose. To validate the recovery narrative, investors need to see the rate of volume decline narrow, evidence that away-from-home and retail branded wins are starting to ship ahead of their heavier fourth-quarter ramp, and early sell-through from the Nature's Own campaign. Gross margin is the tell on fixed-cost absorption; another meaningful step down would suggest the roughly $200 million in prior cost cuts and the newer $20 million of actions are being overwhelmed. Commentary on 2027 inflation in commodities, diesel and packaging, now that pricing can no longer carry the full load, will shape how investors think about next year. Progress on deleveraging toward the sub-3x target, helped by the dividend reset, also deserves attention given how close leverage sat to covenant limits earlier.
Sentiment has soured sharply. Readings show roughly 37% bearish, compared with about 6% bearish ahead of the last report. The stock has slipped 2.6% since then, trailing the S&P 500 by about a point, and at $6.72 it trades well below its 200-day moving average of $7.98. The entire post-earnings range of $5.40 to $7.36 sits below the prior quarter's $6.93 to $8.92 band, a clear downward reset, though shares have recovered meaningfully off the lows. Low expectations offer some cushion, but they have been earned.
Ultimately, this report hinges on whether Flowers can show that its decline is bottoming. A third-quarter dip was promised; what investors need is evidence that volumes, wins and new products are lining up to deliver the fourth-quarter stabilization embedded in guidance. Without that, the Street's estimates near the top of the range look exposed, and the turnaround narrative risks becoming another reset.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Oct-28 | |
| Oct-24 | |
| Oct-02 | |
| Sep-11 | |
| Aug-28 | |
| Aug-27 | |
| Aug-21 | |
| Aug-21 | |
| Aug-21 | |
| Aug-20 | |
| Aug-20 | |
| Aug-13 | |
| Aug-11 |
