NNN REIT Beats On Record Occupancy, But A Held Outlook And Stalled Acquisitions Expose A Cost-Of-Capital Problem
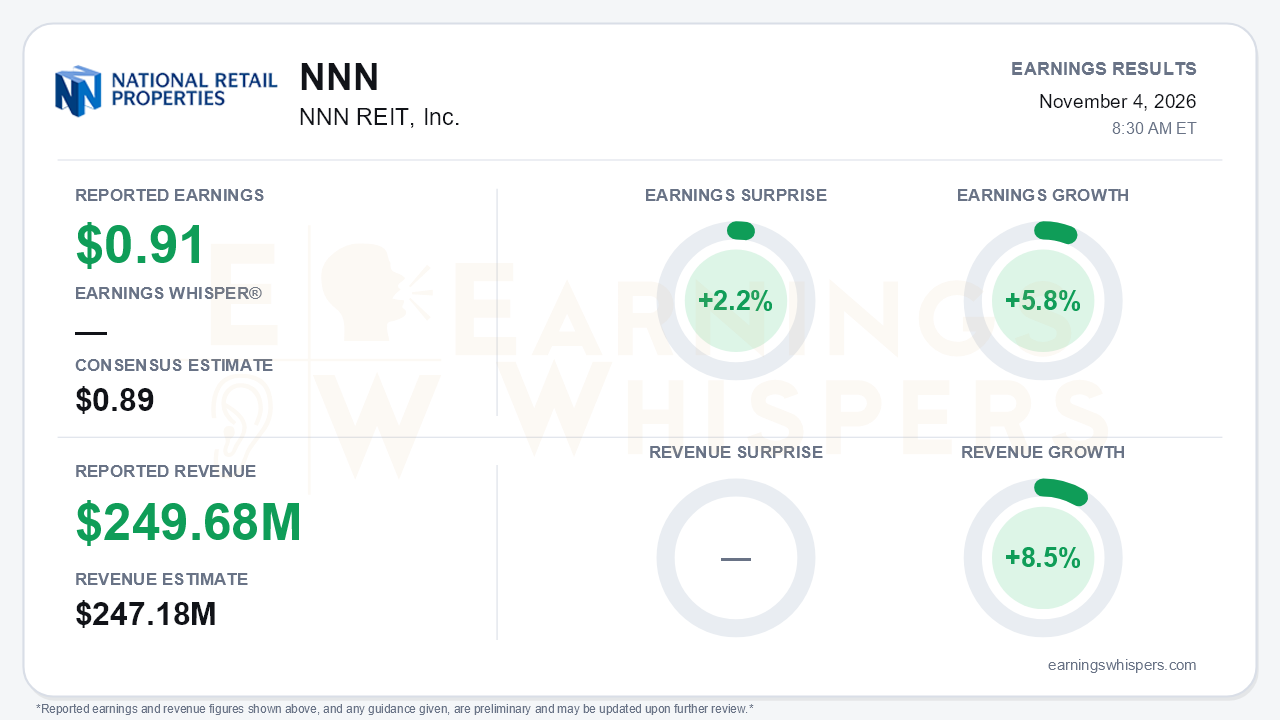
NNN REIT delivered another clean operating quarter, but the more important development was what management did not do. The net-lease REIT reported AFFO of $0.91 per share, beating the $0.89 consensus by 2.2% and growing 5.8% year over year. Revenue of $249.68 million topped estimates by 1.0% and grew 8.5%. Yet after raising AFFO guidance in each of the first two quarters, management held the 2026 range at $3.55-$3.59. That is the central tension: the portfolio has rarely looked healthier, while the external-growth engine that drives NNN's per-share compounding is slowing as its cost of capital rises.
The operating metrics leave little to criticize. Occupancy rose to 99.2%, up from 99.1% in the second quarter and 97.5% a year ago. Annualized base rent climbed 6.8% to $974.0 million. The NOI margin improved to 96.7%. Renewals came in at 105% of prior rent, and re-leasing recaptured 132%. Management cut full-year bad-debt expectations again, to about 25 basis points of ABR from 40 basis points last quarter and an initial 75 basis points, and said the watch list was unchanged. GAAP earnings rose to $0.57 per diluted share from $0.51, and Core FFO reached $0.90 versus $0.85. Still, the quality of the beat deserves some scrutiny. The quarter included roughly $1 million of nonrecurring settlement and land-sale income plus $1.4 million of lease-termination fees. Together those items were worth about a penny per share, or roughly half of the two-cent beat, and management does not expect them to recur.
The call revealed where the momentum is fading. A mid-September rate shock forced NNN to reprice its pipeline, and some sellers walked away rather than accept higher cap rates. Third-quarter acquisitions fell to $221.7 million at a 7.3% cap rate, down from about $290 million in the second quarter. With $658 million closed year to date against an unchanged $750 million midpoint, the guidance implies only about $90 million of fourth-quarter investment. Dead-deal costs and true-ups pushed G&A guidance up $1 million. The holding of AFFO guidance also implies fourth-quarter AFFO no better than the third quarter's pace. Management's tone shifted from last quarter's confident push toward the high end to an emphasis on discipline.
There is an offsetting catalyst. Cap rates on fourth-quarter deals are running 30-40 basis points higher, and 50-60 basis points higher on some transactions. Management expects further expansion in early 2027, which should lift initial yields on new investments. That reverses the cap-rate compression management anticipated in the second quarter. NNN is also exploiting bonus-depreciation buyers to sell convenience stores and car washes at low cap rates, and it raised disposition guidance to $160-$180 million. The balance sheet is a genuine asset in this environment. NNN has $1.4 billion of liquidity, a 9.8-year weighted average debt maturity, and 2.3% floating-rate exposure, and pro forma leverage fell to 5.3x. However, refinancing the $350 million 3.6% bond due in December at roughly 5.6%-6.1% creates a clear 2027 interest headwind.
Bears also have legitimate ammunition on tenant credit. Management flagged Dave & Buster's, at 3.5% of ABR, for ratings pressure and distressed debt. Camping World, at 3.3% of ABR, posted a 62% drop in adjusted EBITDA. Management also noted consumer strain across quick-service and full-service restaurants and entertainment, plus softer convenience-store traffic and in-store margins. None of this has shown up in occupancy or bad debt yet, which is why it reads as a forward risk rather than a current problem.
The market has been pricing in the capital-cost problem. Shares closed at $41.69 before the report, 12.9% below the opening price after the August release and 13.2% under the $48.01 inter-earnings high set the following day. The stock bottomed at $39.59 on October 8 and has recovered only 5.3% from that low. It also sits 5.8% below its 200-day moving average of $44.27. That decline lifted the dividend yield to about 6% from roughly 5.3% in the second quarter. A higher yield raises NNN's equity cost, and recent forward sales were struck at $47.28, well above today's price. Investor sentiment remains negative but improved meaningfully, from -0.26 to -0.13. The Earnings Whispers trend readings are mixed, with sequential growth and momentum positive while price and AVWAP trends remain negative.
The bottom line is that NNN's third quarter strengthened the defensive case and weakened the growth case. Record occupancy, falling bad debt, and a fortress balance sheet make the 6% dividend look secure. But the end of guidance raises, an implied sharp drop in fourth-quarter acquisitions, and a costlier 2027 refinancing mean per-share growth now depends on whether wider cap rates outrun NNN's rising cost of capital. Investors should watch whether deal volume recovers in early 2027 and whether watch-list tenants stay current.
Read our earnings preview for NNN REIT, Inc.: https://www.earningswhispers.com/article/NNN/21720
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 13 hours | |
| 13 hours | |
| Oct-27 | |
| Oct-26 | |
| Oct-15 | |
| Sep-23 | |
| Aug-17 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-31 | |
| Jul-15 | |
| Jun-25 | |
| Jun-23 |
