UWM Beats Easily, But A Shrinking Origination Engine And Costly Rescue Capital Are The Real Story
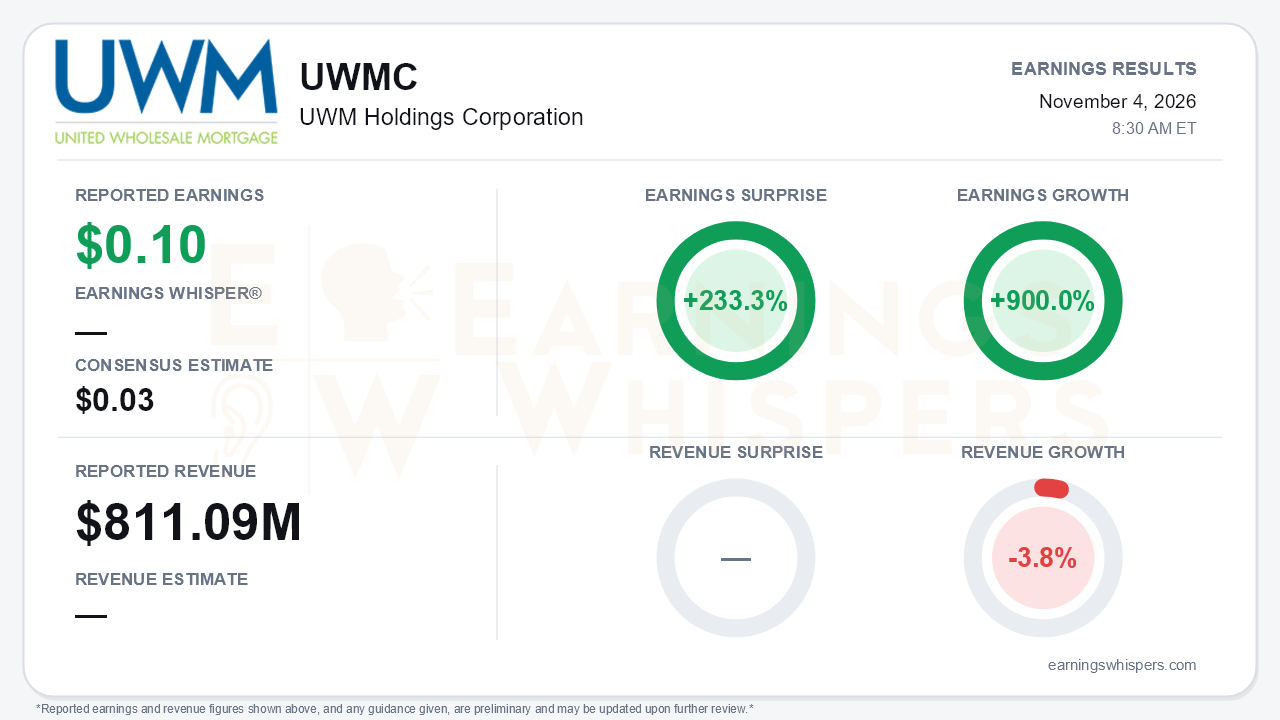
UWM Holdings delivered a headline beat that looks far better than the business underneath it. Adjusted earnings of $0.10 per share topped the $0.03 consensus by 233.3% and grew 900.0% from a year ago. GAAP results swung to $212.6 million of net income from a $451.9 million loss in the second quarter, with diluted EPS of $0.09 versus a $0.24 loss. Revenue, however, fell 3.8% year over year to $811.1 million and slid from $888.0 million in the prior quarter. The central tension is that UWM's profit recovery came mainly from the absence of a hedging disaster, not from a stronger franchise. Origination volume, gain margins and production income all moved the wrong way.
The quality of the beat deserves scrutiny. Second-quarter results were crushed by $725.9 million of net other losses, driven by a $603.2 million derivative loss. In the third quarter, a $470.3 million MSR fair-value gain almost exactly offset a $481.5 million derivative loss, leaving only an $11.2 million net drag. The operating core weakened. Originations fell to $33.4 billion from $39.7 billion in the second quarter and $41.7 billion a year ago. Refinance volume dropped by a third sequentially to $10.6 billion, and total gain margin compressed to 124 bps from 133 bps. Loan production income fell to $415.0 million from $527.2 million. Adjusted EBITDA slipped to $178.3 million from $185.9 million and $211.1 million a year earlier. The cushion came from two places:
- Servicing income rose to $246.6 million from $169.0 million a year ago.
- Total expenses fell about $59 million sequentially to $576.2 million.
The call explained what the press release only hinted at. Management acknowledged a capital "hole" tied to its MSR hedging, saying the company had been over-hedged. It filled that hole with expensive Oaktree capital, structured as preferred and junior preferred stock alongside a rights offering with CEO participation. The balance sheet shows the result:
- $1.5 billion of redeemable preferred stock, carrying a combined redemption value of $2.31 billion.
- $26.1 million in quarterly preferred dividends, now sitting ahead of common holders.
- Net non-funding debt to equity of 1.77x, down from 5.65x in the second quarter.
Management indicated the Oaktree money cannot be repaid for two years, and the warrants and rights offering bring dilution. UWM also plans large fourth-quarter MSR sales to raise cash and reduce leverage toward a 1.5x to 2x target. That reverses the earlier strategy of building the servicing book through in-housing and the Two Harbors deal, which went unmentioned on the call. Selling MSRs will also erode the servicing income that held this quarter together.
The forward picture is defensive. Management said fourth-quarter volume will not be higher than the third quarter's $33.4 billion and cited "a lot of headwinds." The tone has shifted sharply from a year ago, when management promised an "even more dominant 2026" with a "big tailwind." This call opened with a "very tough backdrop." Analysts raised competitors cutting price to win wholesale share and asked about a broker defection reportedly representing $12 billion.
There are credible offsets:
- Gain-on-sale is guided to a steady 115 to 130 bps.
- UWM says it handles roughly 13% of refinances despite holding about 2% of servicing.
- Servicing is now fully in-house without Mr. Cooper.
- A new hedging chief has been hired and the MSR hedging approach revised.
- Management endorsed a roughly $2.1 billion 2027 expense target versus a $2.3 billion third-quarter run rate, crediting AI and technology savings.
- Buybacks to offset warrant dilution are under board discussion.
Investor sentiment remained negative but improved, rising from -0.39 to -0.26. That is a meaningful thaw, not a reversal. The stock has rallied hard off the post-second-quarter collapse. Shares opened at $1.14 after that report and hit a 52-week low of $0.93 the same day. They closed at $1.59 on the eve of this release, up 39.5% since that opening and only 4.8% below the inter-earnings high of $1.67. Even so, the stock sits 42.5% below its 200-day moving average of $2.77. The rebound reflects relief that the capital hole was plugged, not a re-rating of the business. The AVWAP trend has turned positive, but other trend readings are largely neutral.
The bottom line is that UWM's quarter was a balance-sheet repair story disguised as an earnings beat. The Oaktree deal and MSR sales appear to have bought stability, and the cost program is real. But common shareholders now sit behind expensive preferred capital and face dilution. They also own a lender whose volume is shrinking and whose management expects no fourth-quarter improvement. Until originations stabilize and margins hold against price competition, bears retain legitimate ammunition.
Read our earnings preview for UWM Holdings Corporation: https://www.earningswhispers.com/article/UWMC/22426
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Oct-28 | |
| Oct-28 | |
| Oct-23 | |
| Oct-09 | |
| Oct-08 | |
| Oct-07 | |
| Oct-05 | |
| Oct-01 | |
| Sep-28 | |
| Sep-22 | |
| Sep-21 | |
| Sep-18 | |
| Sep-14 |
