Relmada's Q3 Report Is A Test Of Whether NDV-01's Year-End IND Timeline Holds
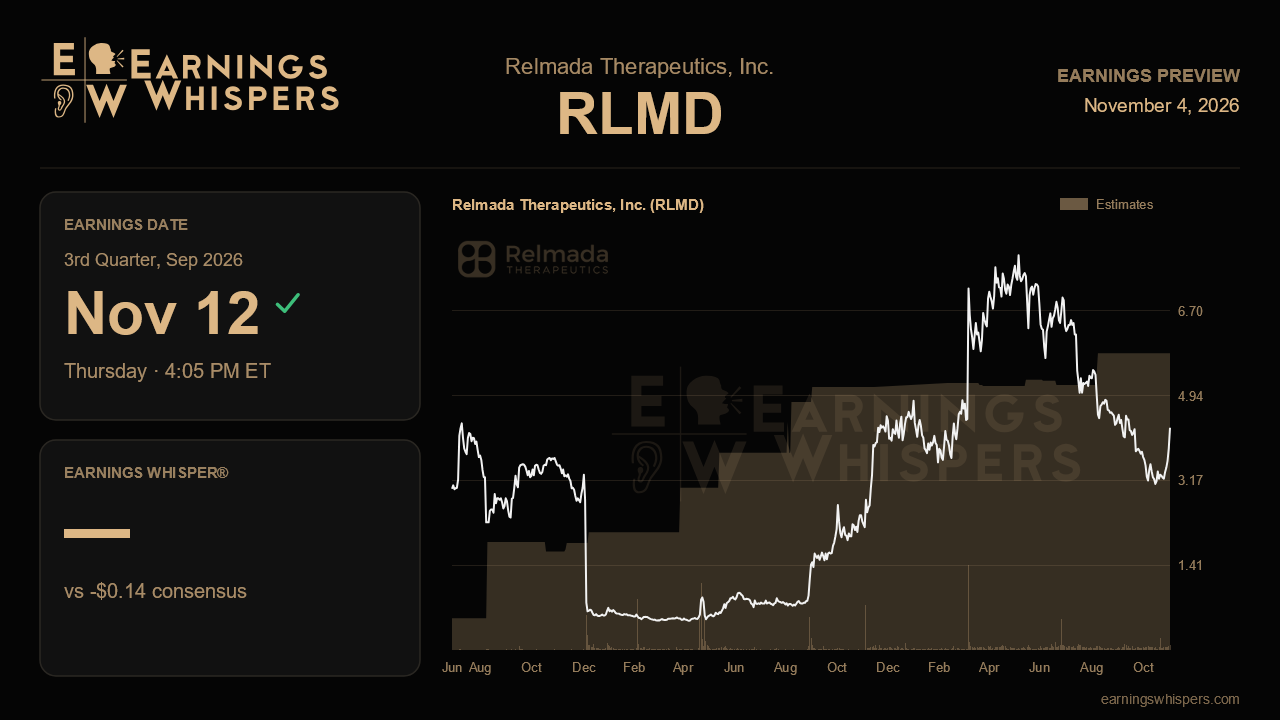
For a clinical-stage company with no product revenue, Relmada Therapeutics' third-quarter report is less about the loss per share than about the calendar. Last quarter, management moved its lead bladder cancer program, NDV-01, back a full step. The Phase III RESCUE program had been expected to begin by mid-2026. The new goal is only an investigational new drug filing by year-end, with enrollment starting about 30 days after FDA clearance. When the company reports after the close on November 12, the main question is whether that reset date is holding or starting to slip again.
The Street expects a loss of 14 cents a share. That is about 53% narrower than the 30-cent loss a year ago, but wider than the 11-cent loss reported last quarter. The sequential increase fits what management described. R&D spending jumped to $8.4 million in the second quarter from $2.8 million a year earlier, driven by manufacturing and storage costs as Relmada builds supply for a pivotal trial. A modestly larger loss would mostly confirm that the CMC work is moving forward. A sharp swing either way matters more. A much smaller loss could mean manufacturing activity stalled. A much larger one would raise questions about cost discipline, even though the balance sheet is strong. Cash stood at $217.7 million at the end of June, down from $234 million a quarter earlier, and management says that funds operations through 2029.
The operating story depends on manufacturing. Management said the NDV-01 formulation and scalable process are locked and the analytical work is complete. That leaves securing a GMP production slot at Piramal and generating the stability data an IND requires. Two things would support the year-end target. One is confirmation that the production run is scheduled or finished. The other is evidence that stability testing is underway. Any vague language about timing, or a shift from year-end to early 2027, would challenge the narrative. This program has already slipped from first-half 2026 to mid-2026 to an IND-only target, so the company has little room to stretch the timeline again.
Secondary items also deserve attention. The Prader-Willi syndrome study of cepranolone slipped in the same way, from a mid-2026 start to a year-end IND filing, and depends on a pre-filled syringe delivery system. The first three-month complete response data in BCG-unresponsive patients was pushed toward the first half of 2027 or later, and management has not decided how it will disclose those results. Clarity on either point would help. So would signs that new Chief Business Officer Bipin Dahlia, who has led an intravesical bladder cancer launch before, is shaping the commercial plan. The absence of former clinical spokesperson Dr. Raj Pruthi from the last call left an open question about clinical leadership, and the company could address it this time.
Sentiment has improved even as the stock has fallen. Bearish sentiment eased to 4.4% from 24.4% heading into the last report, which suggests the worst of the frustration may have passed. Shares, however, have dropped 21.7% since the last report, trailing the S&P 500 by about 19.5 percentage points. At $4.27, the stock sits below its 200-day moving average of $5.35. It trades in the middle of its post-earnings range of $3.07 to $5.55, a range that is noticeably lower than last quarter's $4.85 to $7.66 band. The market has already priced in the delay. What it has not priced in is a second one.
The Phase II data has been consistent across several quarters, including a 95% complete response rate at any time and 76% durable at twelve months, and the scientific case has not been questioned. The issue is execution. If Relmada shows concrete manufacturing progress that keeps the year-end IND credible, the reset timeline becomes believable and the stock's discount looks excessive. If the company hedges on that date, the story moves from a temporary manufacturing delay to a pattern of missed timelines.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Sep-01 | |
| Aug-07 | |
| Aug-06 | |
| Jul-28 | |
| Jul-16 | |
| Jun-29 | |
| Jun-11 | |
| May-28 | |
| May-13 | |
| May-12 | |
| May-06 | |
| May-05 |
