Once Upon A Farm's Margin Trough Meets A Stock That Has Already Lost 40%
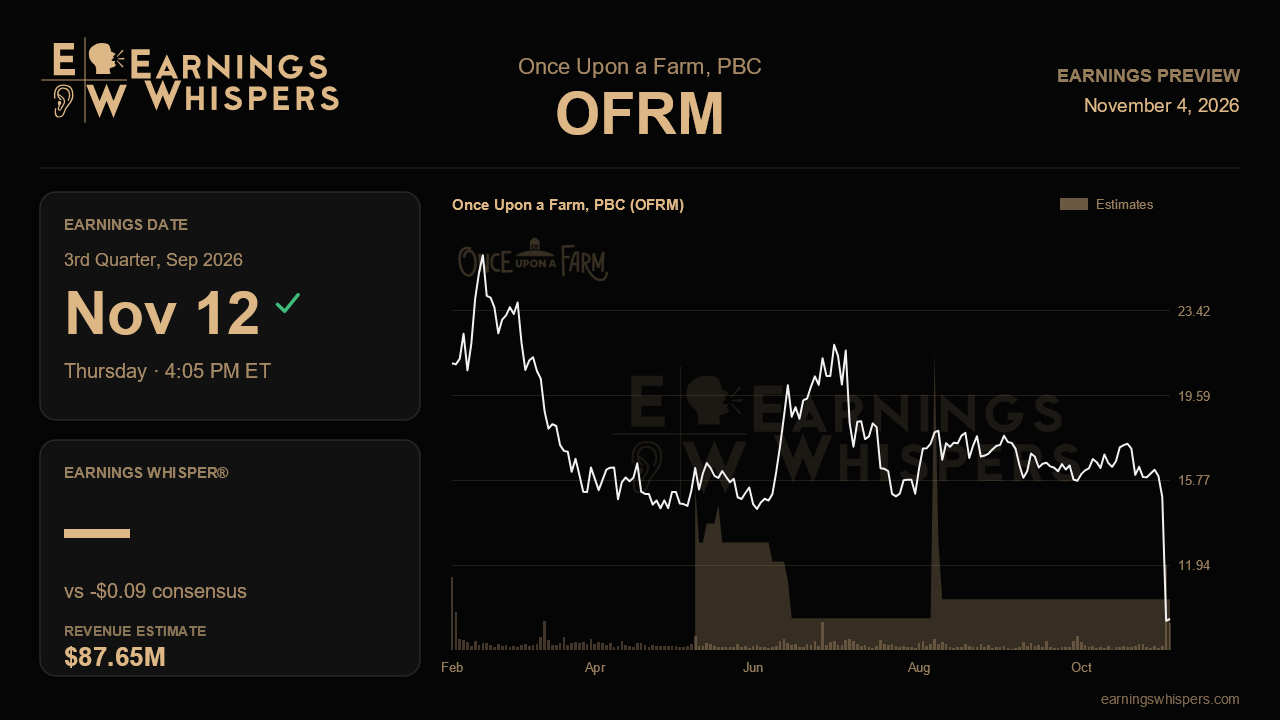
Once Upon a Farm heads into its third-quarter report with an unusual setup. Management raised its sales outlook for the second straight quarter and openly predicted meaningful profitability expansion in 2027, yet the stock has fallen 42.7% since that call, trailing the S&P 500 by more than 40 percentage points. The market appears to have focused on the other half of the message: a lower gross margin bar and a warning that the third quarter would look no better on profitability than the second. This report will show whether that warning marked the bottom or was only the start.
Wall Street expects a loss of $0.09 per share on revenue of about $87.7 million, a modest step up from the $85.4 million and $0.12 loss posted last quarter. The revenue figure looks conservative against management's own outlook. The company now targets 2026 sales of $327 million to $335 million, up from a prior range of $313 million to $323 million, while full-year consensus of roughly $318 million sits below even the bottom of the new range. Either the Street doubts the raise or its models have not caught up. In either case, a clear top-line beat this quarter would carry weight, because the guidance implies a stronger second half than many forecasts reflect.
The earnings side is less clean. Management guided third-quarter gross margin to roughly match the second quarter's 35.9%, which was down nearly 500 basis points from a year earlier, and said adjusted EBITDA would post a loss slightly worse than the $1.7 million deficit in the second quarter. The causes were spelled out: a faster-growing mix of lower-margin baby snacks, trade spending on a second national club program, and higher freight, fuel and tariff costs. A narrower per-share loss estimate sits a little awkwardly beside that guidance, so investors should judge the quarter by whether margins land where management said they would rather than by the headline EPS figure alone. A gross margin meaningfully below 36% would suggest cost pressures are spreading. A result at or above it would support the claim that this is a deliberate, temporary mix trade-off.
The demand story is where the bull case either holds or breaks. Management pointed to a large step-up in baby pouch distribution in the third quarter after cooler-reset timing slowed that business sequentially, so baby sales need to reaccelerate. Household penetration climbed from 5.1% to 6.2% over three quarters and repeat rates kept rising, and further gains would show the club program is converting trial into loyal buyers. Early reads on the new functional kid pouches, the protein baby pouches that management described as largely incremental, and the low single-digit snack price increase taking effect in late September will also matter. Inventory, which rose almost 48% to $51.9 million, should begin to look proportionate to sales rather than ahead of them.
Sentiment has warmed considerably even as the share price collapsed, with bearishness easing from about 32% heading into last quarter to near neutral today. At $9.52, the stock trades far below its 200-day moving average of $17.41 and sits closer to its post-earnings low of $8.83 than its high of $18.40. That suggests the price already discounts considerable disappointment, though it does not guarantee a rebound.
The central question is whether this quarter proves to be the margin trough management described. If sales run ahead of the pace implied by the raised guidance, baby distribution expands as promised, and gross margin holds near 36% with the full-year target of about 40% intact, the story of volume-led growth funding future profitability stays credible. Another margin slip or a stall in the baby business would give the market's skepticism stronger grounds.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-08 | |
| Nov-05 | |
| Nov-04 | |
| Nov-02 | |
| Nov-02 | |
| Oct-31 | |
| Oct-30 | |
| Oct-29 | |
| Oct-22 | |
| Oct-19 | |
| Oct-05 | |
| Oct-05 | |
| Oct-05 | |
| Sep-03 | |
| Aug-20 |
