SmartRent's In-Line Loss Masks Its Strongest Quarter In Two Years, But Software Monetization Lags The Hardware-Driven Rebound
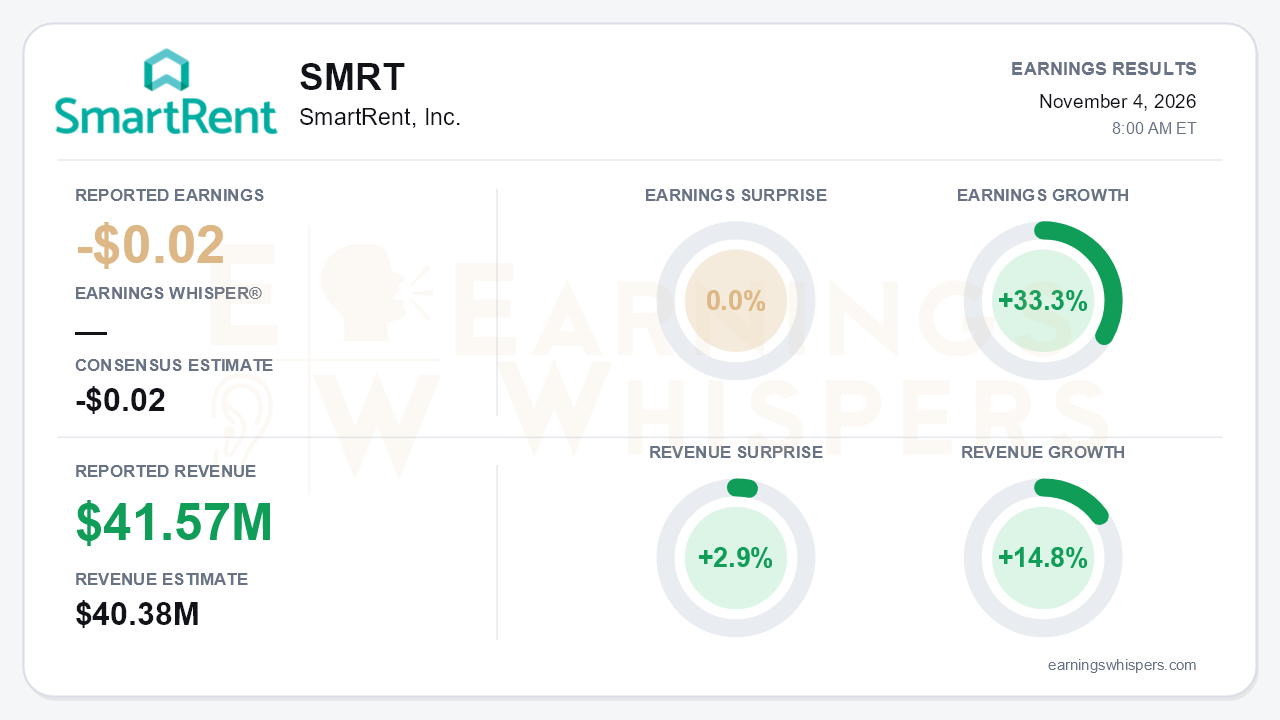
SmartRent (NYSE: SMRT) reported a third-quarter loss of $0.02 per share, matching the consensus estimate. Earnings grew 33.3% year over year. Revenue of $41.57 million beat expectations by 2.9% and grew 14.8%. The in-line bottom line understates the quarter. Management called it the strongest financial and operating performance in over two years, and the trajectory supports that claim. Core revenue growth stepped from roughly flat in Q1 to 14% in Q2 and 24% in Q3. Gross margin expanded 1,470 basis points to 41.2%, and SmartRent offered explicit quantitative quarterly guidance for the first time. The central tension is the source of that acceleration. It is coming mainly from hardware and margin repair, while the recurring software engine is slowing.
The gap between 15% total revenue growth and 24% core revenue growth comes from legacy hub amortization rolling off. That non-cash revenue fell to $0.9 million from $3.4 million a year ago, so core revenue is the cleaner read on volume. Within that figure, hardware did the heavy lifting. Hardware revenue rose 61% to $18.5 million, helped by shipments staged ahead of fourth-quarter deployments. Access control revenue grew 171% to $4.7 million. Profitability gains were real. Gross profit rose 79% to $17.1 million, and SaaS gross margin reached 74.6%. Adjusted EBITDA swung to $1.1 million from a $2.9 million loss, extending its sequential climb from $0.2 million to $0.4 million to $0.7 million to $1.1 million. The GAAP net loss narrowed to $3.9 million from $6.3 million, and operating cash flow turned positive at $2.9 million. Operating expenses are climbing, however. They rose to $21.9 million from $16.6 million, or about 15% excluding a $2.5 million accrual reversal that flattered the prior-year period. Management is spending on sales capacity, technology and AI rather than letting gross-margin gains fall through to earnings.
The call made the demand story more credible. Trailing-twelve-month units booked rose 44% to 122,510, accelerating from 40% growth in Q2. Booking dollars rose 29% to about $144 million. Installed units reached 941,977, and management reaffirmed its target of passing one million units in the first half of 2027. Management's tone moved from Q1's talk of cautious customers and market headwinds to describing a meaningfully positive inflection point. Guidance shifted from vague "second half stronger than first" language to concrete Q4 targets:
- total revenue growth of 15% to 20%
- core revenue growth of 20% to 25%
- adjusted EBITDA growth of 450% to 650%
The EBITDA percentage is eye-catching, but it comes off a small $0.2 million base, so the dollar improvement is modest. Earnings Whispers characterized the outlook as in line.
Bears still have legitimate ammunition, and most of it sits in the recurring revenue base. SaaS revenue grew 11%, slower than the 13% pace in Q2. ARR of $62.9 million slipped sequentially from the roughly $65 million cited last quarter. Management attributed the decline to churn in its Smart Operations maintenance product and expects the pressure to persist for a couple more quarters. Units Booked SaaS ARPU fell 18% to $7.09, so the booking surge carries less software value per unit than a year ago. Trailing hardware units shipped fell 6% and new units deployed fell 13%, which means price and mix, not volume, drove much of the hardware gain. Upgrade-and-refresh hardware and installation revenue grew only 6.3% despite the emphasis on refresh demand. Field installation capacity must scale to convert the backlog. Management described the multifamily capex environment as still "not great" and declined to guide 2027. Cash slid to $89.2 million from $93 million in Q2 and $99 million in Q1, partly because of $3.4 million in buybacks. An undrawn $75 million credit facility provides cushion.
Investor sentiment remained negative but improved, moving from -0.51 to -0.42 between reports. That is a meaningful thaw, not a reversal of skepticism. The stock has behaved similarly. Shares rose 19.1% from the $1.15 open after the August report to $1.37 heading into this release. That puts them just 2.2% above the 200-day moving average and about 21% above the September 18 low of $1.13. They remain nearly 10% below the August 14 high of $1.52, so the stock has recovered from its trough without reclaiming its post-report peak. Earnings Whispers momentum and AVWAP trend readings are positive, while the price trend is neutral.
The bottom line is that SmartRent delivered a genuinely improved quarter. Core growth is accelerating, gross margin has been rebuilt, cash flow is positive, and Q4 guidance is concrete. Even so, the in-line EPS and still-negative sentiment reflect unresolved questions. Until ARR stabilizes and SaaS growth reaccelerates, the rebound rests more on hardware shipments and cost discipline than on the recurring software model that ultimately has to carry the investment case.
Read our earnings preview for SmartRent, Inc.: https://www.earningswhispers.com/article/SMRT/21742
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-14 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-29 | |
| Jul-15 | |
| Jul-06 | |
| Jun-16 | |
| Jun-08 | |
| May-12 | |
| May-06 | |
| Apr-27 |
