AFG's Record Quarter Leans On A One-Time Gain As Pricing Accelerates And Underwriting Margins Thin
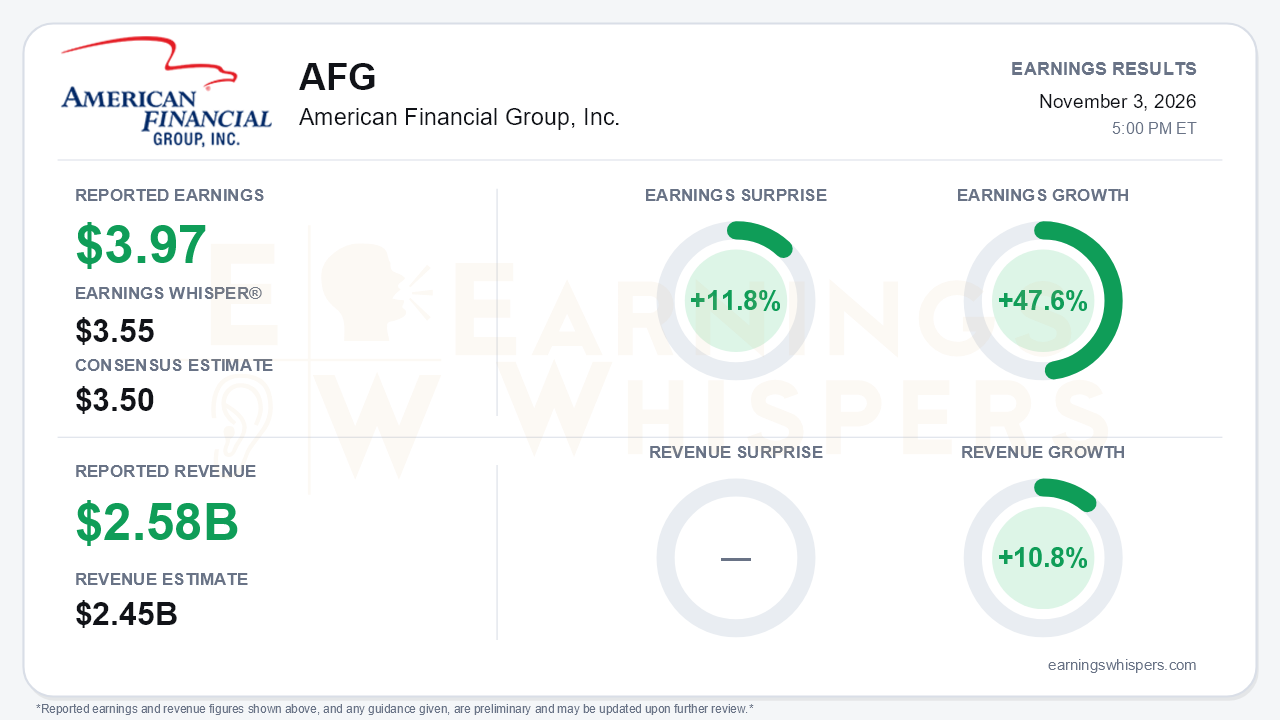
American Financial Group (NYSE: AFG) reported record third-quarter core net operating earnings of $3.97 per share. That was 11.8% above the $3.50 consensus estimate and ahead of the $3.55 Earnings Whisper number. Earnings grew 47.6% from a year ago, and revenue of $2.583 billion rose 10.8% and topped the $2.45 billion consensus by 5.4%. The headline needs context, though. The August sale of Charleston Harbor Resort & Marina generated $126 million in pretax net investment income and contributed $1.21 per share to core earnings. Management had flagged roughly that amount on the prior call. Without it, core earnings were about $2.76, only modestly above last year's $2.69 and below the $2.82 earned in the second quarter. That is the central tension. AFG's top-line and pricing momentum is accelerating, but the underwriting engine produced less profit than it did earlier in the year.
The quality of the beat deserves scrutiny on several fronts. The Specialty P&C combined ratio was 93.8%, which was 0.8 points worse than a year ago. It was also well above the 91.5% in the second quarter, the 90.3% in the first quarter, and the roughly 92.5% plan. Underwriting profit slipped to $133 million from $139 million. Favorable prior-year reserve development was 1.5 points, slightly better than a year ago but sharply below the 3.4 and 4.4 points that flattered the first two quarters. The biggest drag was Specialty Financial, where an isolated large fire and business-interruption loss in Europe cut underwriting profit to $23 million from $51 million. GAAP earnings of $3.40 per share were also pressured. They absorbed $0.34 of realized losses and a $0.23 special charge for environmental exposures tied to former railroad and manufacturing operations. The P&C run-off A&E review itself produced no reserve change.
The growth story, by contrast, strengthened meaningfully. Net written premiums rose 9%, accelerating from 6% in the second quarter and 3% in the first, well above the 3% to 5% plan set at the start of the year. Renewal pricing excluding workers' compensation improved to roughly 6% from about 5%, a level it had held for the prior three quarters. Specialty Casualty pricing jumped about 2 points to 6% excluding comp. Specialty Financial moved to +4% from slightly negative. Commercial auto liability posted a third straight quarterly underwriting profit on about 15% rate increases. Management also noted that its social-inflation-exposed casualty lines developed favorably on a net basis, which it acknowledged has not always been the case.
The investment side adds a second leg of support. Excluding the Charleston sale, P&C net investment income grew 10%. AFG deployed about $1.5 billion into fixed maturities at roughly 6% yields, up from 5.5% last quarter, and extended P&C duration to 3.6 years from 3.1. That should provide a more durable earnings tailwind than the real estate gain. Bears still have legitimate ammunition:
- Specialty Casualty gross written premiums grew less than 1%, slowing from 5%, as California non-renewals bit.
- The accident-year loss ratio in that group rose to about 65% from 63.5% in the first half.
- California workers' comp remains a loss-maker on cumulative trauma claims, prompting a 9.1% rate filing.
- Alternative investments returned 6.7%, below both the prior quarter and the 8% plan.
- The multifamily recovery is arriving more slowly than the second-half timing management previously outlined.
Capital return escalated sharply. The board declared a $3.50 special dividend, about $290 million, compared with $1.50 in February, after a 10.2% increase in the regular dividend. Book value excluding AOCI grew 5.5% with dividends in the quarter. Reported book value per share, however, slipped to $57.12 as rising rates widened AOCI losses to $428 million.
Investor sentiment remained negative but improved noticeably, rising to -0.11 from -0.28 at the prior report. Expectations have warmed, though they are not yet enthusiastic. Shares have gained 5.9% since the open after the August report and closed at $153, about 12% above the 200-day moving average of $136.62. The Earnings Whispers trend signals are mostly positive, with sequential growth neutral, consistent with a stock that has been steadily rewarded rather than re-rated aggressively.
The bottom line is that AFG delivered a beat built partly on a pre-announced asset sale, while its core underwriting margin weakened from an exceptionally strong first half. What genuinely improved is the forward setup. Premium growth and pricing are accelerating, reinvestment yields are climbing, and excess capital is flowing back to shareholders. Whether combined ratios settle back toward plan as reserve releases normalize will determine whether that growth translates into earnings once the Charleston windfall rolls off.
Read our earnings preview for American Financial Group, Inc.: https://www.earningswhispers.com/article/AFG/21539
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-26 | |
| Oct-13 | |
| Oct-01 | |
| Aug-31 | |
| Aug-27 | |
| Aug-20 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-14 | |
| Jul-01 |
