Timken Beats And Raises A Third Time, But Slowing Organic Growth And Tariff Refunds Complicate The Story
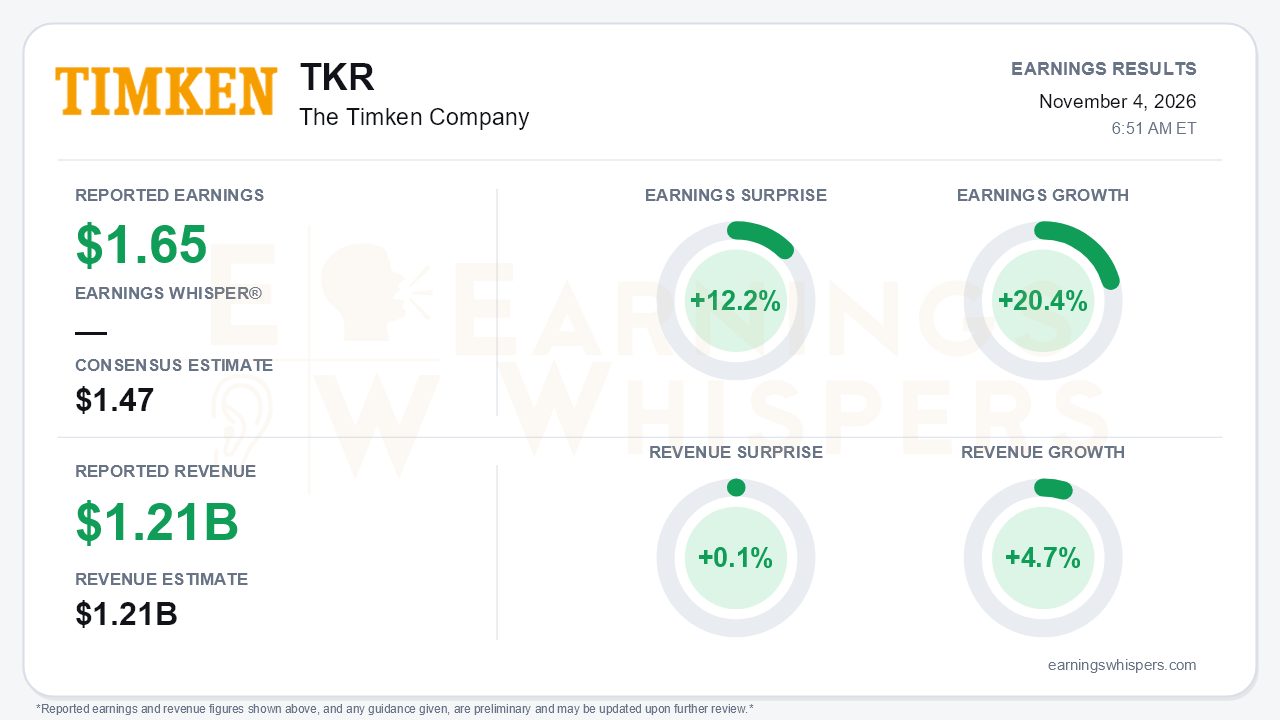
Timken delivered another beat-and-raise quarter, reporting third-quarter adjusted EPS of $1.65. That topped the $1.47 consensus by 12.2% and grew 20.4% from a year ago. Revenue of $1.211 billion was essentially in line, beating consensus by just 0.1% and rising 4.7%. Management raised full-year adjusted EPS guidance for the third consecutive quarter, to $6.35-$6.50 from $6.05-$6.35. The central tension is that earnings power keeps improving while top-line momentum is softening. Organic growth slowed to 2.8% from 4.4% in the second quarter and 4.3% in the first, and part of the beat came from a non-recurring source.
The quality of the beat deserves scrutiny. Adjusted EBITDA included a $12.4 million net benefit from IEEPA tariff refunds, worth roughly $0.13 per share, up from about $0.08 in the second quarter. Stripping that out, the quarter still would have cleared consensus, so the beat is not illusory. It is, however, less impressive than the headline suggests. The same caveat applies to the Engineered Bearings segment, whose adjusted EBITDA margin expanded to 20.2% from 18.8%. The release credits that improvement primarily to the tariff refund, along with price/mix and currency, while segment sales rose only 0.7%. Elsewhere, the GAAP picture was cleaner. Diluted EPS rose to $1.34 from $0.99, aided by the absence of last year's CEO transition costs. Cash generation was the most unambiguous strength: operating cash flow of $256 million and free cash flow of $221 million, up from $164 million a year ago and roughly $80 million in the second quarter.
Beneath the consolidated numbers, the two segments are moving in opposite directions.
- **Industrial Motion** carried the quarter. Sales rose 12.4%, organic growth was 7.3%, aerospace and defense grew about 20%, and automation and robotics grew by double digits.
- **Engineered Bearings** grew just 0.5% organically on flat volumes. China wind declined by double digits, and management expects another sequential decline in the fourth quarter.
- **Regionally**, EMEA swung to a 3% organic decline from a 5% gain in the second quarter, with August notably weak.
Industrial Motion's strength also came with a margin wrinkle. Its adjusted EBITDA margin of 19.8% improved from 19.0% a year ago but fell sharply from 23.3% in the second quarter on unfavorable regional and product mix. Management also flagged aerospace and defense capacity investments and labor inflation as cost headwinds.
The guidance package was genuinely mixed, which explains why the EPS raise does not settle the debate. On the positive side, management:
- lifted the adjusted EBITDA margin outlook to mid-18% from low-18%;
- raised the automation and industrial solutions sector outlook;
- trimmed expected interest expense, worth about $0.08 per share.
On the other side, it:
- cut the power and electrification outlook because of China wind;
- reduced the expected M&A revenue contribution to 0.75% after the belts sale;
- only reaffirmed revenue guidance of roughly 5.5% total and 3.5% organic.
Put simply, the EPS raise reflects margin, refunds, currency, and lower interest expense more than stronger volume.
The forward-looking catalysts are what preserve a credible growth story. CEO Lucian Boldea offered a preliminary 2027 view of mid-single-digit organic growth. That would be an acceleration from 2026's roughly 3.5%, and management said it is net of the automotive OE exit, whose volume headwind falls mostly in 2028. Several other developments support that view:
- **Backlog** rose sequentially and grew by mid-single digits year over year.
- **Pipelines** in aerospace and defense and in automation and robotics are up strong double digits.
- **Marine defense projects** that are large and long-cycle are in final bidding, with revenue expected in 2027.
- **The belts divestiture**, completed at quarter-end, is expected to add more than 200 basis points to Industrial Motion's margin, or about 60-70 basis points consolidated, in 2027.
- **Balance sheet and buybacks:** net leverage fell to 1.7x from 2.0x at year-end, and repurchases stepped up to about 505,000 shares, giving management room to keep returning cash.
The market has not been rewarding the earnings momentum. Heading into the report, shares were down 11.9% since the open following the August release, closing at $115.66. That left the stock 14.3% below its August 17 inter-earnings high of $134.96 and only 8.9% above its October 23 low of $106.25. The stock also sat about 1.4% below its 200-day moving average of $117.32. Price-based trend readings remain negative, consistent with that drawdown. Investor sentiment was essentially unchanged, edging from 0.0364 to 0.0356, a barely positive reading that suggests expectations were muted rather than euphoric. That is not a stretched setup, but bears have legitimate ammunition. Organic growth has decelerated, wind exposure is worsening, EMEA is soft, and tariff refunds are flattering results.
The bottom line is that Timken is executing well on margins, cash flow, and portfolio cleanup, and the third straight guidance raise plus an early 2027 growth outlook give the bull case real support. However, the quarter's earnings strength outpaced its revenue strength, and a meaningful slice of the beat came from refunds that will not recur. Whether the stock can recover from its post-August slide likely depends on evidence that the backlog and defense and automation pipelines translate into the reaccelerating organic growth management is now promising for 2027.
Read our earnings preview for The Timken Company: https://www.earningswhispers.com/article/TKR/21749
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-14 | |
| Oct-02 | |
| Sep-29 | |
| Sep-29 | |
| Sep-28 | |
| Sep-05 | |
| Sep-01 | |
| Sep-01 | |
| Aug-26 |
